Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
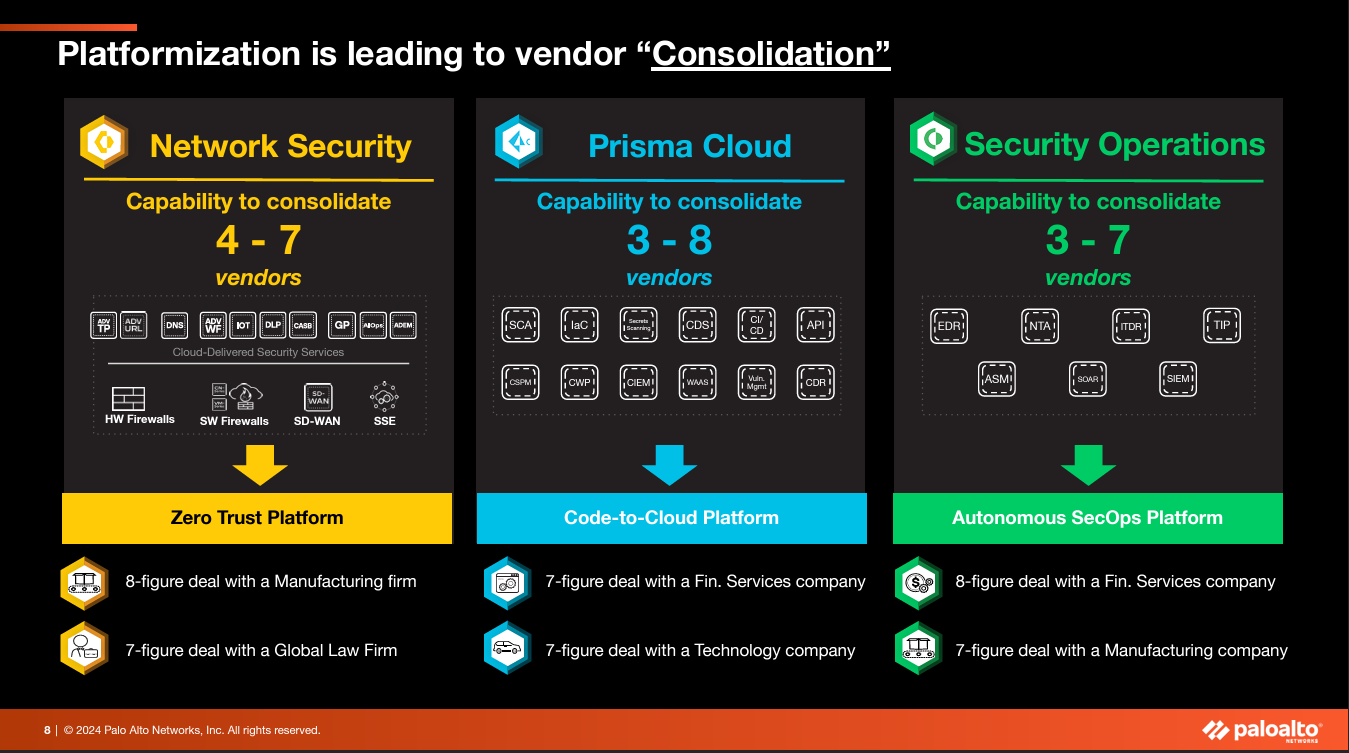
Palo Alto Networks is changing its strategy to entice enterprises to spend on its security platform as customers consolidate security vendors. Palo Alto Networks' bet is to accelerate security vendor consolidation by offering platform deals with introductory offers and deferred payments to grab share.
When Palo Alto Networks reported its second quarter earnings it handily topped expectations. The outlook, however, was light. Palo Alto Networks projected fiscal 2024 billings between $10.1 billion to $10.2 billion, down from the earlier range of $10.7 billion to $10.8 billion. Revenue for fiscal 2024 will be between $7.95 billion and $8 billion, down from $8.15 billion to $8.2 billion.
The efforts to gain share will impact revenue growth for about 12 months to 18 months, but Palo Alto Networks CFO Dipak Golechha said the security vendor has internal expense levers to preserve operating margins. Rest assured that other cybersecurity platforms—namely CrowdStrike and Zscaler will offer enterprise deals and incentives too.
CEO Nikesh Arora said customers are seeing spending fatigue and optimizing security budgets to see returns on investment.
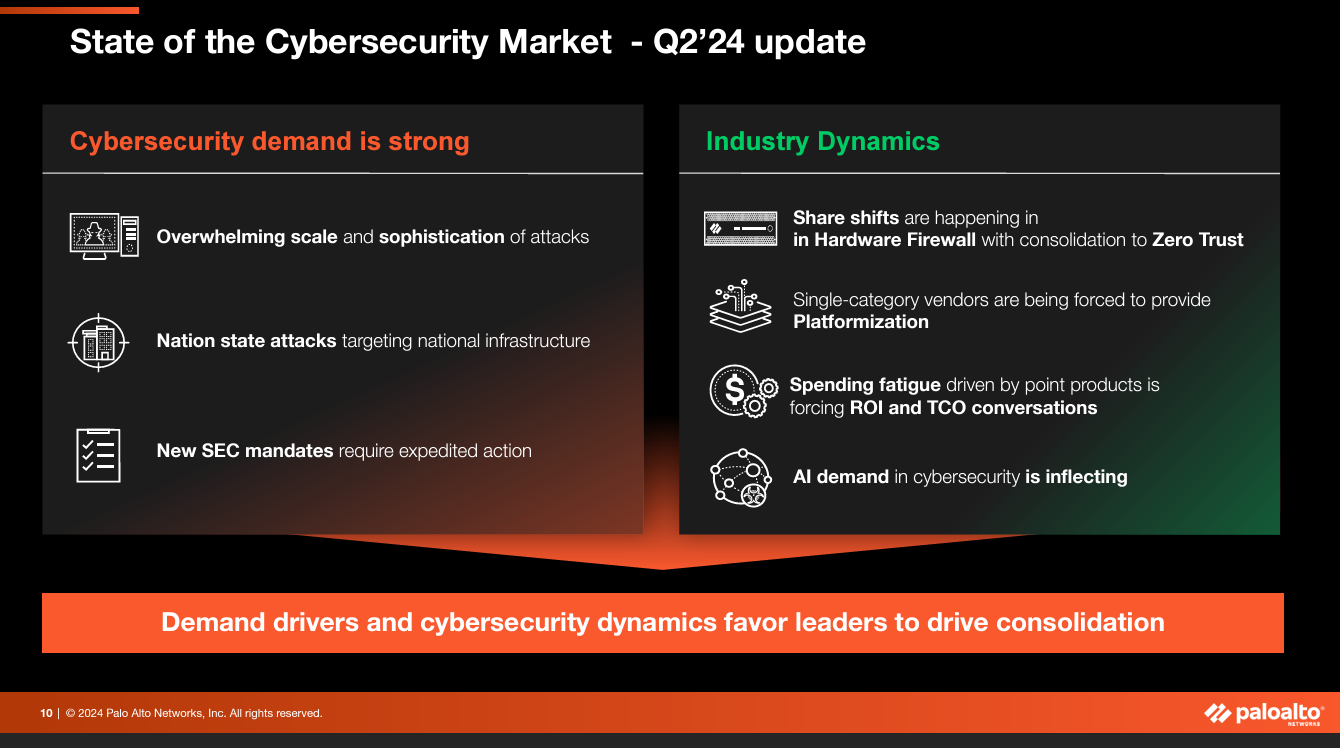
Here's Arora's assessment of enterprise security spending on Palo Alto Networks' earnings call.
"Most of our customers have ended up spending more on cybersecurity than they wanted to. As a consequence, they're feeling like the budget for cybersecurity keeps going up in double digits every year and you see the number of breaches continue to rise. So, customers are sitting down and saying if I spend more money, then show me how I get a lower total cost of ownership across my enterprise. How do I spend less on the services that I have to deploy? How do I get better ROI? It's more about optimizing their current cybersecurity budgets. Demand continues to be very strong, but customers are demanding more for the money allocated to cybersecurity. That's where platform consolidation kicks in."
Palo Alto Networks said it will offer programs to trade in legacy vendors, no cost deals, introductory offers and product add-ons and incentives to convince enterprises to standardize on Palo Alto Networks.
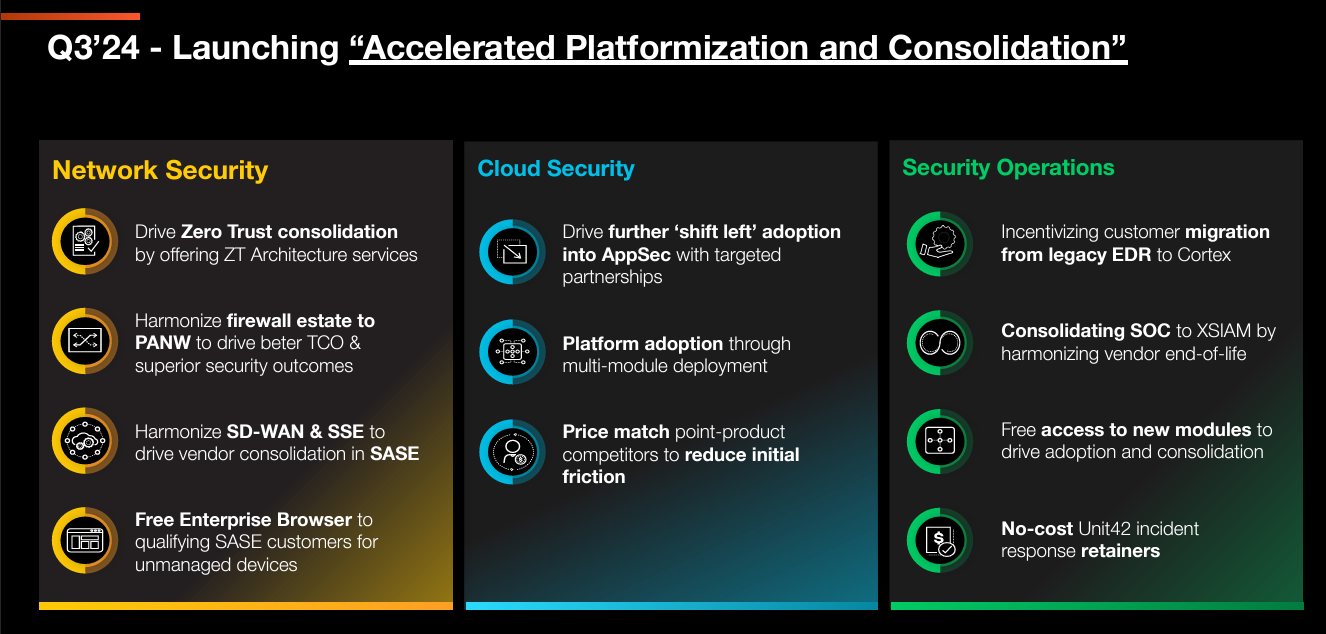
Arora said the programs and offers are designed to address customers' economic concerns and Palo Alto Networks "must bear the cost of the transition to lower upfront financial outcomes."
As a result, customers entering a platform transaction won't pay Palo Alto Networks for a time period. Over time, customers will migrate to full billing and revenue contribution.
"We believe we can sustain high growth rates for longer aspire to by sticky and broad platform relationships and incremental customers, allowing us to aspire the goal of $15 billion in next generation security in 2030," said Arora.
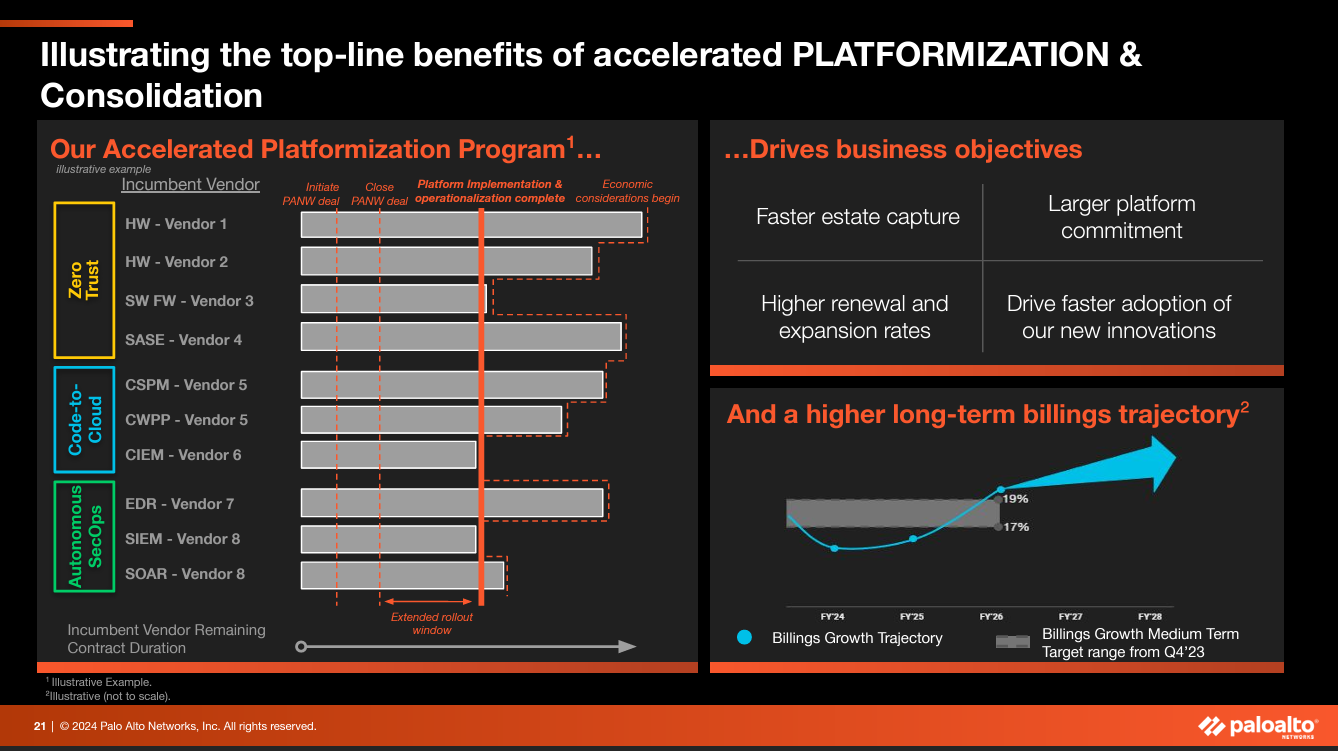
He added that as Palo Alto Networks puts more customers on its platform it'll gain as AI gains as a use case for cybersecurity in the years ahead. said Golechha. "Once a customer deploys the platform, it's easier to continue to consolidate vendors and adopt new innovations. We expect this to drive a significant increase in our overall revenue mix that is occurring," said Golechha.
For the second quarter ending Jan. 31, Palo Alto Networks had non-GAAP earnings of $1.46 a share on revenue of $2 billion. Wall Street was looking for earnings of $1.30 a share on revenue of $1.97 billion.
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Hitachi Vantara named Ayman Abouelwafa as its new chief technology officer as it continues to build out its executive team.
Abouelwafa, who was previously CTO of Hewlett Packard Enterprise's storage group, lands at Hitachi Vantara just weeks after the hybrid cloud infrastructure company named Octavian Tanase as chief product officer. Tanase was previously at NetApp.
Like Tanase, Abouelwafa will report to Hitachi Vantara CEO Shiela Rohra. Abouelwafa will also serve on Hitachi Vantara's executive committee. In a statement, Rohra said Abouelwafa will bring a deep understanding of emerging technologies and market trends as Hitachi Vantara aims to become a leading hybrid cloud company.
At HPE, Abouelwafa was responsible for commercializing next-generation data storage platforms and software as well as strategic research.
Here's more on Hitachi Vantara, a Constellation Insights underwriter.
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Walmart's purchase of smart TV maker Vizio for $2.3 billion to expand its Walmart Connect advertising business highlights how chief marketing officers have more options than ever. Amazon has a booming advertising business and has become No. 3 behind Google and Facebook. Uber sees advertising as a big growth business. So does Lyft.
For publishers, media companies and traditional ad players, the marketing landscape doesn't look so great. For everyone else--especially companies with first-party data and relationships with customers--advertising is great.
Seth Dallaire, executive vice president and chief revenue officer, Walmart U.S., said: "We believe Vizio's customer-centric operating system provides great viewing experiences at attractive price points. We also believe it enables a profitable advertising business that is rapidly scaling. Our media business, Walmart Connect, is helping brands create meaningful connections with the millions of customers who shop with us each week."
Vizio also brings more than 500 direct advertiser relationships to Walmart's ad business, which had annual revenue of $3.4 billion, up 28% from a year ago.
Walmart isn't the only advertising giant in the making. Amazon CEO Andy Jassy said the company's ad business was up 26% in the fourth quarter to $14.65 billion. "Our advertising growth remains strong, up 26% year-over-year, which is primarily driven by our sponsored ads. We've recently added Sponsored TV to this offering in the U.S. a self-service solution for brands to create streaming TV campaigns with no minimum spend, putting this advertising within reach of any business," said Jassy.
And then there's Uber, which is leveraging its data platform to create a flywheel that'll drive advertising. "The power of our advertising platform stems from what Uber users tell us every time they use our apps where they want to go and what they want to get. And as a result, we've got the unique ability to bring together both location based and shopping data with closed loop attribution across our mobility and delivery channels for both performance and brand campaigns," said Iber CEO Dara Khosrowshahi.
How we got here
If you look at those aforementioned three companies advertising moves, they have common assets. Walmart, Amazon and Uber have scale, first party data and strong relationships with their customers.
Simply put, first party data is everything. Google's move to depreciate cookies, which enabled tracking across the web, only makes first party data more important.
Constellation Research analyst Liz Miller recently walked through the long-awaited end of cookies by the third quarter of 2024. Miller said big brands and advertisers have been evaluating alternatives to cookies.
She said:
"I think a lot of marketers have gotten really smart about those first party data requirements, building those direct relationships and building those consent-based relationships. We're having more open value exchange conversations as we should be. This is really about the best practices about how we want to engage. This is really about how we're choosing to personalize how we're choosing to collect data, how we're choosing to engage that through a digital channel."
Miller also had the following recommendations for the post-cookie world:
Audit site for all third-party cookies and trackers. Understand what is being collected and used.
Use Google's auditing tools as well as manual searching to fully identify third party cookies.
Ask third party providers about their plans for cookies and privacy sandbox.
Move away from or phase out advertising-related cookies. Transition to consent-based data collection.
If site functionality breaks from cookie deprecation, apply for exemption by April 1, 2024.
Implement alternatives for measurement, targeting and personalization without third party cookies.
A volatile time for CMOs
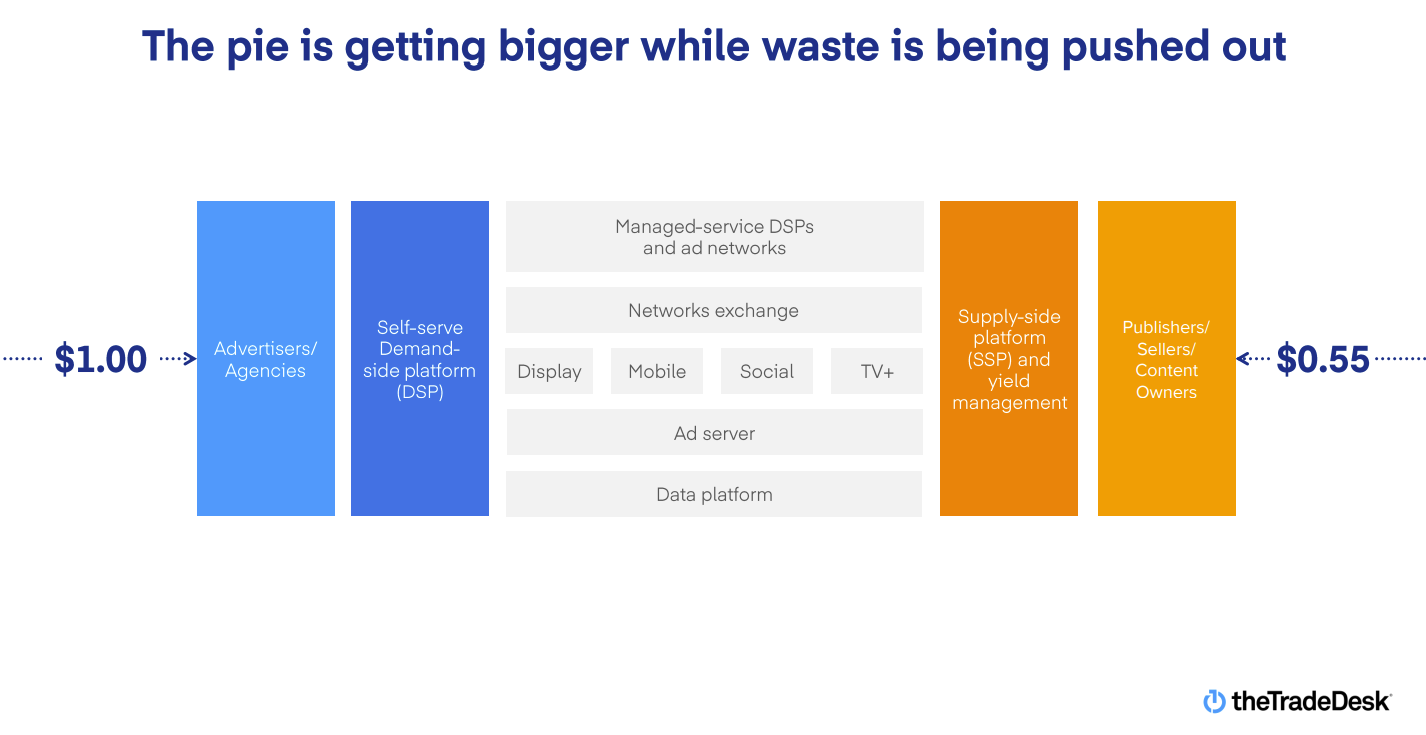
Jeffrey Green, CEO of The Trade Desk, recently served up perspectives on the global advertising market and said it shifts just like the economy or any other market.
"The current shifts will help companies with authenticated users and traffic, which also sit next to large amount of advertiser demand. These macro changes hurt those, especially content owners and publishers who don't have authentication," said Green, who added that 2024 will be a year of volatility and big winners and losers.
Green cited Unified ID 2.0, a cookieless identity platform, as an alternative as well as retail ad channels. He cited HP as a reference customer that used first-party data that consumers consented to when making a purchase combined with UID2 used for campaigns on Disney+ and Hulu, and its data platform to segment groups and measure specific product campaigns with accuracy.
The Trade Desk CEO argued that the ad industry is being rewired. "For nearly all of 2023, there was uncertainty, particularly around economic growth rates and recessionary fears. In that environment, CMOs become much more reliant on their CFOs, and CFOs needed to make sure that every dollar spent was in service of growth. Which means CMOs had to focus more than ever on where they could achieve efficacy and deliver strong and provable return on ad spent," said Green.
Given that economic backdrop it's not surprising, streaming, audio and retail media fared well because they had authentication and precision measurement.
Green said it's no surprise that retail platforms and Uber are faring well. The game is to connect experience, identity, advertising to real-world actions. "Retail media has become one of the fastest growing areas of our business, and we expect this to continue in 2024. Retail partnerships and retail media are revolutionizing the way many advertisers think about connecting advertising to actual consumer actions," said Green.
Constellation Research's take
Miller said there's upside ahead despite the volatility. She said:
"There is an incredible upside to the deprecation of the Cookie that in the throws of the past several years of bemoaning the Cookiepocalypse some seem to have overlooked: It appropriately right sizes advertising back into being a TOOL in the CMO's far more expansive toolkit. Advertising has never been the whole pie for marketing no matter how often people want to use the terms interchangeably! Walmart's pick up of a presentation layer opens opportunity as a content provider and advertising network. In an age of headless content delivery and AI powered ad engagement capabilities, this deal could kick start a whole new level of contextual content delivery, be that advertising or programmed content."
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Nvidia's ability to stay ahead of the curve is fascinating. Nvidia has dominated generative AI with GPUs that until recently were the only game in town for accelerated computing, but should a new buzzword turn up CEO Jensen Huang will be riding that wave too.
The company reported fourth quarter revenue of $22.1 billion, up 265% from a year ago, with earnings of $4.93 a share. Non-GAAP earnings for the fourth quarter were $5.16 a share. Wall Street was looking for Nvidia to report fourth-quarter non-GAAP earnings of $4.64 a share on revenue of $20.62 billion. For a bit of perspective, Nvidia quarterly revenue is approaching what it used to put up a year. In fiscal 2023, Nvidia revenue was $26.97 billion.
But it's worth noting how well Nvidia's previous bets have paid off--even the ones you probably already forgot about like the company's networking business, which is now on a $13 billion annual revenue run rate. I started thinking about Nvidia's bets after checking out Arista Networks' results. Arista Networks reported a strong quarter (as it usually does) and CEO Jayshree Ullal noted that generative AI will change networking infrastructure.
It's worth doing a long excerpt from Ullal just to outline the moving network parts with AI workloads. He said (emphasis mine):
"AI at scale needs Ethernet at scale. AI workloads cannot tolerate the delays in the network, because the job can only be completed after all flows are successfully delivered to the GPU clusters. All it takes is one culprit of worst-case link to throttle an entire AI workload.
Three improvements are being pioneered by Arista and the founding members of the Ultra Ethernet Consortium to improve job completion time. Number one, packet spraying. AI network topology needs packet spraying to allow every flow to simultaneously access all parts of the destination. Arista's developing multiple forms of load balancing dynamically with our customers.
Two is flexible ordering. Key to an AI job completion is the rapid and reliable bulk transfer with flexible ordering using Ethernet links to optimally balance AI-intensive operations, unlike the rigid ordering of InfiniBand. Arista is working closely with its leading vendors to achieve this.
Finally, network congestion. In AI networks, there's a common congestion problem whereby multiple uncoordinated senders can send traffic to the receivers simultaneously."
Simply put, the pilots in the network today will be in production in 2025. The network will be revamped in the near future. Companies like Cisco, Arista and Juniper Networks should benefit—unless Nvidia’s networking business gets a piece of the AI pie.
For instance, Arista said it won a handful of big deals, but one customer decided to stick to InfiniBand.
Remember InfiniBand, which was championed by Mellanox? Well, Mellanox was acquired by Nvidia in 2020 for $7 billion. The deal was announced in 2019. Here's what Huang said when the Mellanox deal closed: "With Mellanox, the new NVIDIA has end-to-end technologies from AI computing to networking, full-stack offerings from processors to software, and significant scale to advance next-generation data centers."
Nvidia also offers Ethernet gear as well as DPUs (data processing units) under its BlueField brand. Nvidia offers a set of networking gear and software for AI workloads in addition to its InfiniBand routers, gateways and switches.
Here's the big question: Will customers go the path of least resistance with AI-induced networking upgrades and a Nvidia bundle? Or will customers stick with networking specialists?
Today, Nvidia's Mellanox purchase probably wouldn't have been approved by regulators. The argument would be that Nvidia would have full-stack AI offerings. Can you imagine if Nvidia bought Arm like it wanted to?
Nvidia's networking was also a hot topic on Cisco's earnings call. Cisco and Nvidia have partnered on integrated AI systems. However, analysts were wondering whether Cisco's networking technology would be used in integrated systems. Robbins said the deal "would include our Ethernet technology with their GPUs" when connecting multiple clusters instead of Nvidia’s networking stack.
Robbins added that Nvidia is hoping to gain from Cisco's channel and go-to-market scale. Analysts were clearly worried about Cisco being threatened by Nvidia's Spectrum-X networking platform. Nvidia networking business appears to be in co-opetition with established networking vendors. Chalk it up as another bet that paid off for Nvidia.
Huang talked a bit about Nvidia's networking business, notably Spectrum-X. Spectrum X Ethernet has adaptive routing congestion control, noise isolation and traffic isolation. Huang said Spectrum X Ethernet will be an AI optimized system and InfiniBand will be an AI dedicated networking option. Simply put, Nvidia is going to get some of the AI-optimized networking pie too. Huang said on Nvidia's conference call:
"We're ramping Spectrum-X. We're doing incredibly well with Spectrum-X. It's our brand-new product into the world of ethernet. InfiniBand is the standard for AI-dedicated systems. Ethernet with Spectrum-X --Ethernet is just not a very good scale-out system.
But with Spectrum-X, we've augmented, layered on top of ethernet, fundamental new capabilities like adaptive routing, congestion control, noise isolation or traffic isolation, so that we could optimize ethernet for AI. And so InfiniBand will be our AI-dedicated infrastructure."
Nvidia is too often in the right place at the right time for it to be coincidence. Is it luck? A crystal ball? Time travel? Who knows, but consider:
Nvidia was a blockchain darling for a bit as demand for GPUs surged for bitcoin mining.
The metaverse--which was huge, then dead and likely to be huge again--is also powered by Nvidia.
Digital twins? Yep Nvidia.
Growth of the video game industry. Nvidia again.
Robotics. Nvidia.
Automobiles that will ultimately be autonomous. Huang can riff on the auto industry for days.
I could go on, but you get the idea. What's next? Quantum computing. Nvidia is building a stack for hybrid quantum computing featuring accelerated computing. Nvidia sees a world where GPUs and QPUs (quantum processing units) will work together. Rest assured Nvidia will ride the QPU wave too.
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
VMware acknowledged that customers are disgruntled, chafing against a switch to subscription licensing and annoyed that account contacts may change. You have to cut through a lot of VMware mansplaining--delivered via a Valentine's Day blog post--to get those takeaways.
In a lengthy blog post, Prashanth Shenoy, VMware Vice President Marketing, Cloud Platform, Infrastructure, and Solutions, tried to address the elephant in the VMware ecosystem--the changes since Broadcom closed the VMware deal have rattled customers.
Meanwhile, VMware customers are actively looking at alternatives. VMware customers will likely be a huge topic when rival Nutanix reports earnings. Members of the Constellation Research BT150 have already noted that they have mapped out VMware exit strategies. By the way, VMware partners aren't pleased either.
With that backdrop, you almost feel sorry for Shenoy. Here are a few excerpts and a quick translation.
"Since the completion of Broadcom’s acquisition of VMware, we have been all about change. For the VMware Cloud Foundation division, all of this change was necessary to transform our business to deliver faster innovation with more value to customers, and even better profitability and market opportunity for our partners."
Translation: VMware has received enough pushback that it's worry about its numbers.
From there, Shenoy notes that VMware's transition to subscription licensing has been done before. A simplified portfolio will make it easier on customers and standardization will drive value.
Translation: VMware is forcing customers to buy a bundle of stuff wrapped into VMware Cloud Foundation and some of it won't be used.
"Subscription is the model all major enterprise software providers are on today. Subscription software is the right model for fueling continuous innovation for customers. This past quarter we finalized the switch fully to subscription software, just like everyone else. We immediately turned this transformation into net new value for our customers. How? Do you want to have deployment flexibility? Now you can. When you purchase VMware Cloud Foundation, you get license portability."
Translation: Yes, we're mansplaining that you'll most likely be spending more than you used to. We'll allow you to take your licenses to hyperscalers, but so far only Google Cloud is signed up.
Shenoy then noted that VMware has consolidated product teams and R&D and lumped them into VMware Cloud Foundation. While that move is nice for Broadcom's costs, VMware will have to show customers the innovation payoff. Shenoy added that automation tools for data services, load balancing and private AI as examples.
VMware customers aren't happy, but partners in the channel aren't pleased either. Shenoy devoted a subhead to channel changes. Again, VMware does a bit of mansplaining and noted that Broadcom is taking the big accounts.
"It makes business sense for Broadcom to have close relationships with its most strategic VMware customers to make sure VMware Cloud Foundation is being adopted, used and providing customer value. However, we expect there will be a role change in accounts that will have to be worked through so that both Broadcom and our partners are providing the most value and greatest impact to strategic customers."
Translation: VMware is taking big accounts and partners will have to figure something out.
Finally, VMware customers get to the kicker. Shenoy said that VMware feels customer pain.
"Broadcom identified things that needed to change, and as a responsible company, made the changes quickly and decisively. The changes that have taken place over the past 60+ days were absolutely necessary. We understand this massive transformation and simplification of the portfolio and our business model has raised many questions and concerns as you continue to evaluate how to maximize value from your VMware software investments. We are proactively working with the sales teams and channel partners to help customers make this transition and encourage customers to engage them to work through the best approach for their businesses."
Translation: Embrace the pain. These changes are happening anyway. We'll figure it out and you'll stick with VMware because it's too hard this minute to migrate off of our platform. You're stuck until proven otherwise.
Shenoy ended with "it will only get better" in a statement that seems to assume customers will stick around. It remains to be seen whether customers reply with "it only takes one to end a relationship."
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Google Cloud said Google's new Gemini 1.0 models, Gemini 1.0 Pro and Gemini 1.0 Ultra are generally available to enterprises and an private preview is available for Gemini 1.5.
Vertex AI customers will have access to Gemini 1.0 Pro, which is optimized for content generation, editing, classification and summaries. Gemini 1.0 Ultra will give Vertex AI customers a model for coding, reasoning and multi-language use cases.
Google Cloud also said Gemini 1.5 Pro will be available in private preview for Vertex AI in Google AI Studio. This model is midsized and optimized for multiple use cases. It performs at a similar level to Gemini 1.0 Ultra.
According to Google Cloud, Gemini 1.5 Pro gives enterprises the ability to analyze an entire code library in one prompt, reason across long documents, compare and analyze hours of video content, enable chatbots to hold long conversations with memory and personalize experiences without fine-tuning.
Gemini models will be available to enterprises via the Gemini API in Vertex AI and available to Vertex AI Search and Vertex AI Conversation.
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Informatica is planning on riding digital transformation, which is still a work in progress for enterprises, a need to integrate data across vendors, clouds and on-premises and generative AI in 2024.
The data management and governance company hit its stride in the fourth quarter with strong results. Informatica CEO Amit Walia said the company is benefiting from customers that are getting their data houses in order as well as a vendor agnostic approach. Walia said:
"Customer spending more than $1 million in subscription ARR increased 17% year-over-year to 240 customers. We had a record number of customers spending more than $5 million in subscription ARR, which grew 57% year-over-year. We pride ourselves on being the Switzerland of data and have accelerated ecosystem co-selling with Microsoft Azure, AWS, Google Cloud, Snowflake and Databricks and announced a new strategic partnership with MongoDB."
As enterprises focus more on data platforms to fuel digital transformation, automation and generative AI plans, Informatica stands to gain. Informatica does appear to be at an inflection point and topped the high-end of its guidance for the fourth quarter and year.
In the fourth quarter, Informatica reported net income of $64.26 million, or 21 cents a share, on revenue of $445.18 million. The company has been migrating customers from licensing to a cloud subscription model, but still has a sizable on-premises installed base.
For 2023, Informatica reported a net loss of $125.3 million on revenue of $1.59 billion. Informatica has also been able to pay down its debt ahead of schedule and is now under a 2x leverage ratio.
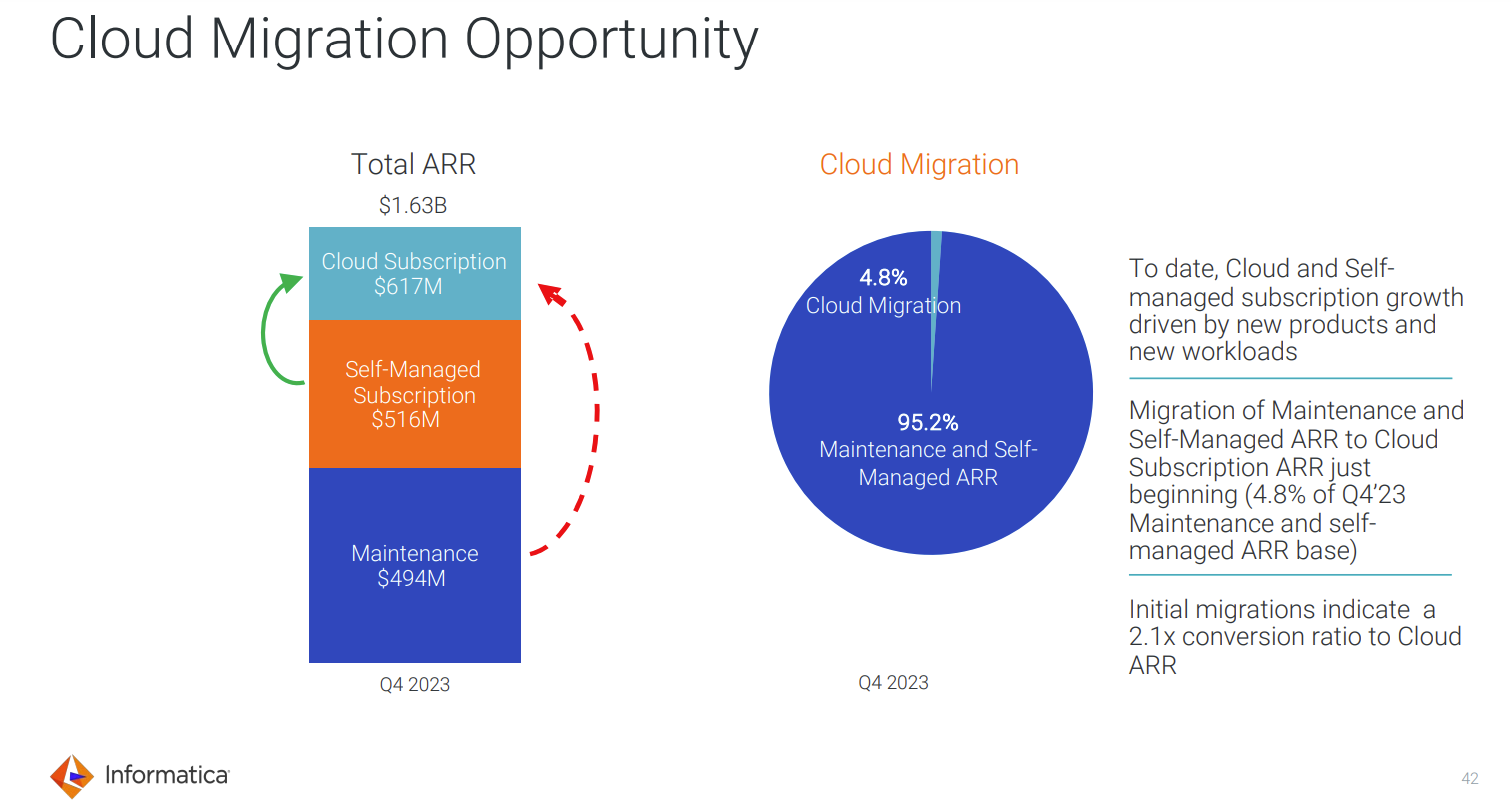
Informatica also passed the $1 billion mark in subscription annual recurring revenue for the fourth quarter and year. Cloud subscription ARR in the fourth quarter was up 37% from a year ago to $617 million. Informatica also said it processed 86 trillion cloud transactions per month in the fourth quarter.
Walia said 75% of new cloud bookings came from new workloads and expansion by customers. Informatica's updates to its platforms, led by its CLAIRE AI, have been coming at a steady cadence. In addition, the company is on track to integrate the data access management tools acquired in the Privatar acquisition.
Informatica, which cited Royal Caribbean, Pella and enGEN as key customer wins in the quarter, said first quarter revenue will be between $375 million to $395 million, up 5.4% from a year ago. Cloud subscription ARR, which is what Wall Street is watching closely, will be up 34.5% in the first quarter. For 2024, Informatica is projecting $1.68 billion to $1.7 billion.
Holger Mueller, Constellation Research analyst, said that Informatica's ability to move to double-digit growth rates for cloud and subscriptions is notable. The company still has to pay down debt and build on its product roadmap. Mueller said:
"Informatica for the first time broke the $1 billion in revenue milestone with software revenue now running at double the size of maintenance and professional service revenue, an improvement over the past. Informatica is more valuable. What is weighing hard on Informatica is interest expense, roughly at 10% of revenue, dragging the vendor into the red, more than doubling losses per share. It will be key for Amit Wallia and team to address this in the coming fiscal year. Informatica needs to keep product innovation and strategic partnerships (a 2023 highlight) going."
Constellation Research analyst Doug Henschen added:
"Informatica hit an important milestone in reaching $500 million in cloud subscription revenue in 2023, representing 50 percent of total subscription revenues. That percentage will only increase as cloud subscriptions continue to drive the company's growth."
Walia said future growth will come from the following key trends:
Enterprises need a neutral platform that can handle multiple vendors and clouds.
Digital transformation efforts require modern data stores and integration tools. "Enterprises need to move away from bespoke tactical tools and adapted end-to-end data management platform that treats data strategically to drive digital transformation," said Walia.
Informatica customers are migrating to the cloud and there are plenty of migrations coming. The company still has $1 billion in on-prem maintenance and self-managed revenue.
Generative AI is landing Informatica new customers. "There is no Gen AI without data. And for data to have value, it needs core data management such as holistic data, clean data, govern data, accessible data," said Walia.
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Twilio projected first quarter revenue growth of 2% to 3% to $1.025 billion to $1.035 billion, below expectations of $1.05 billion.
The company also projected non-GAAP earnings of 56 cents a share to 60 cents a share. Wall Street was looking for 55 cents a share. The outlook came as Twilio reported its fourth quarter earnings. Twilio's results were the first with new CEO Khozema Shipchandler at the helm.
Shipchandler said Twilio is entering 2024 "from a position of strength and the team is focused on further delivering on our customer engagement vision for our customers."
Twilio's outlook was light, but its fourth quarter results handily topped estimates. The company reported fourth-quarter non-GAAP earnings of 86 cents a share on revenue of $1.08 billion, up 5% from a year ago. Wall Street was looking for earnings for 58 cents a share on revenue of $1.04 billion.
Communications revenue in the fourth quarter was up 5% from a year ago and Segment revenue was up 4%.
For 2023, Twilio reported a net loss of $5.54 a share on revenue of $4.15 billion, up 9% from a year ago. Non-GAAP earnings for the year were $2.45 a share.
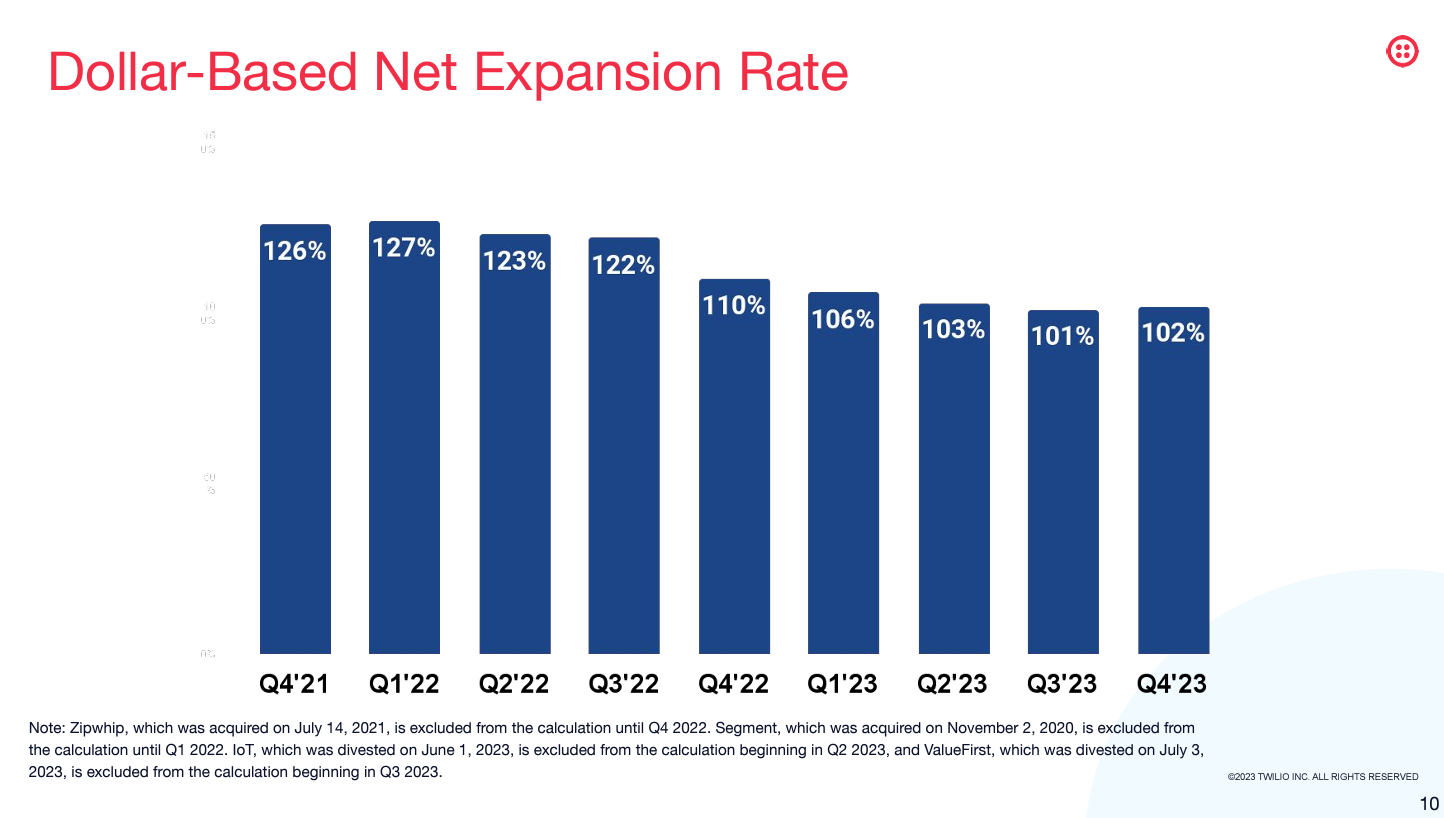
Twilio ended the quarter with 305,000 active customer accounts, up from 290,000 a year ago. Dollar-based net expansion rate was 102%, but that was down from 110% a year ago.
According to the company, the Segment unit is being evaluated to "identify the appropriate path forward for improved execution and profitable growth." Segment revenue was $295.2 million for 2023 and $75 million in the fourth quarter.
Segment was a major topic on Twilio's earnings conference call. Analysts were peppering Shipchandler with questions about whether Segment fit. A few key quotes to note from Shipchandler about Segment.
"Twilio Segment is not performing at the level it needs to and I've already begun to take a closer look at this business to see how we can deliver improved performance."
"Over the past five weeks, I've been working with the team to conduct an extensive operational review of Segment, and this work is ongoing. We plan to do a read-out of these results in March at which time I'll be ready to share our findings, path forward, and any changes to Twilio's financial framework as a result."
"Some of the indicators that we're looking at is sequential bookings, and we did see improvement in Q4, but as we alluded to, it's not exactly where we'd like it to be. And I think just the overall pace of the improvements that we were anticipating and that we would expect of ourselves, they're just kind of not meeting our expectations."
"I think that we do see a lot of opportunity there in terms of our ability to combine our data offering with our Communications offering. And we've started to launch a handful of products that do exactly that, bring together kind of all of the best capabilities of Twilio within single offerings. You see that today, for example, in our Flex Unify offering, which has been announced relatively recently."
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Cisco said it will cut 5% of its global workforce in a bid to "realign the organization and enable further investment in key priority areas." The company outlined the restructuring as it reported its second quarter results.
The networking giant reported second quarter revenue of $12.8 billion, down 6% from a year ago, with earnings of 65 cents a share. Non-GAAP earnings were 87 cents a share.
Wall Street was expecting fiscal second quarter earnings of 84 cents a share on revenue of $12.7 billion. The biggest concern going into Cisco's report was the weak demand for networking gear as customers deploy systems that have been purchased.
For the third quarter, Cisco said revenue will be $12.1 billion to $12.3 billion with non-GAAP earnings between 84 cents a share to 86 cents a share. Analysts had expected adjusted earnings of 92 cents a share on $13.09 billion in sales. For fiscal 2024, Cisco said revenue will be between $51.5 billion to $52.5 billion with non-GAAP earnings of $3.68 a share to $3.74 a share.
Cisco said that it will take charges of $800 million for the layoffs and most of the hits will be recognized in the third quarter.
Chuck Robbins, CEO of Cisco, said the second quarter was solid, but the company has to focus its investments on future growth. "Our innovation sits at the center of an increasingly connected ecosystem and will play a critical role as our customers adopt AI and secure their organizations," he said.
Robbins said:
"We're seeing a greater degree of caution and scrutiny of deals given a high level of uncertainty. As we discussed last quarter, and subsequently saw in other technology provider results, customers are starting to deploy the elevated levels of products shipped in them in recent quarters. This is taking longer than our initial expectations."
Robbins added that telecom and cable companies are pulling back on spending. He said that customers will take another quarter or two to digest shipments already received. "Our team is also partnering closely with customers to assist with this heightened focus on deployments at Cisco equipment on hand," said Robbins.
The Cisco CEO said he's optimistic about AI workloads boosting demand, but noted that "we're still in the early stages of AI workloads."
Constellation Research analyst Chirag Mehta said Cisco's future growth is pegged the the acquisition of Splunk, which could close in the third quarter.
"With the acquisition of Splunk, Cisco is poised to elevate the cybersecurity landscape, potentially merging their respective portfolio of products, and enhance them with advanced AI capabilities. This strategic move not only amplifies Cisco's commitment to cybersecurity but also paves the way for unparalleled benefits to a vast spectrum of its customers. As networks and security converge, Cisco's focus on cybersecurity will be paramount to unlock sustained growth in an ever-evolving digital landscape."
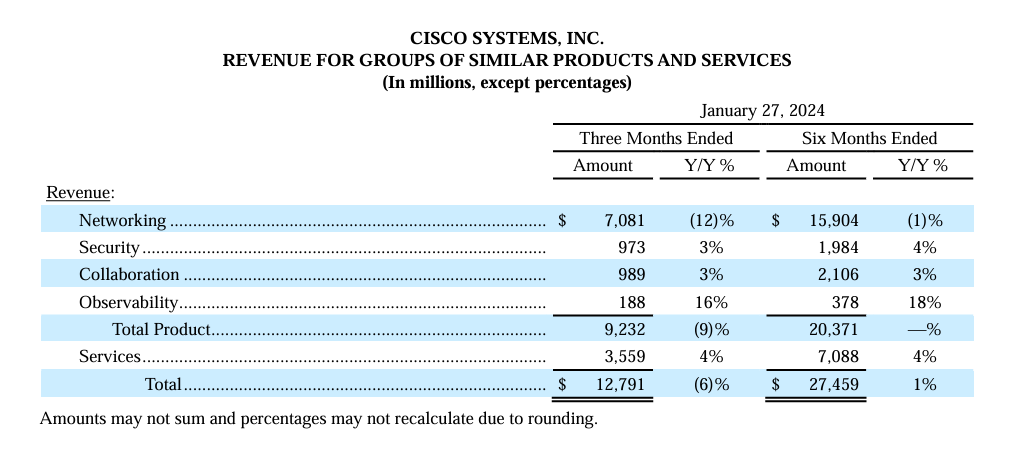
Cisco's second quarter networking revenue was down 12% from a year ago with security and collaboration up 3% each. Observability revenue was up 16%, but from a smaller base. Services revenue was up 4%.
Cisco’s results land a few days after Arista Networks reported fourth quarter earnings, which were strong. Arista Networks, which counts Meta Platforms and Microsoft as its largest customers, reported fourth quarter revenue of $1.54 billion, up 21% from the same period last year. Net income was $613.6 billion, or $1.92 a share. Non-GAAP earnings were $2.08 a share.
Arista Networks CEO Jayshree Ullal noted that generative AI will create a networking infrastructure upgrade cycle. “AI at scale needs Ethernet at scale. AI workloads cannot tolerate the delays in the network, because the job can only be completed after all flows are successfully delivered to the GPU clusters. All it takes is one culprit of worst-case link to throttle an entire AI workload,” said Ullal.
Editor in Chief of Constellation Insights
Constellation Research
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Uber has leveraged its technology stack and data architecture to create a flywheel that can expand into multiple new markets. Uber is data incorporated and likely a glimpse into future business models.
At Uber's Investor Day, CEO Dara Khosrowshahi and the company's executive team outlined the company's growth plans, a $7 billion buyback and its data flywheel.
Here are some key takeaways from Uber's 90-minute session with analysts.
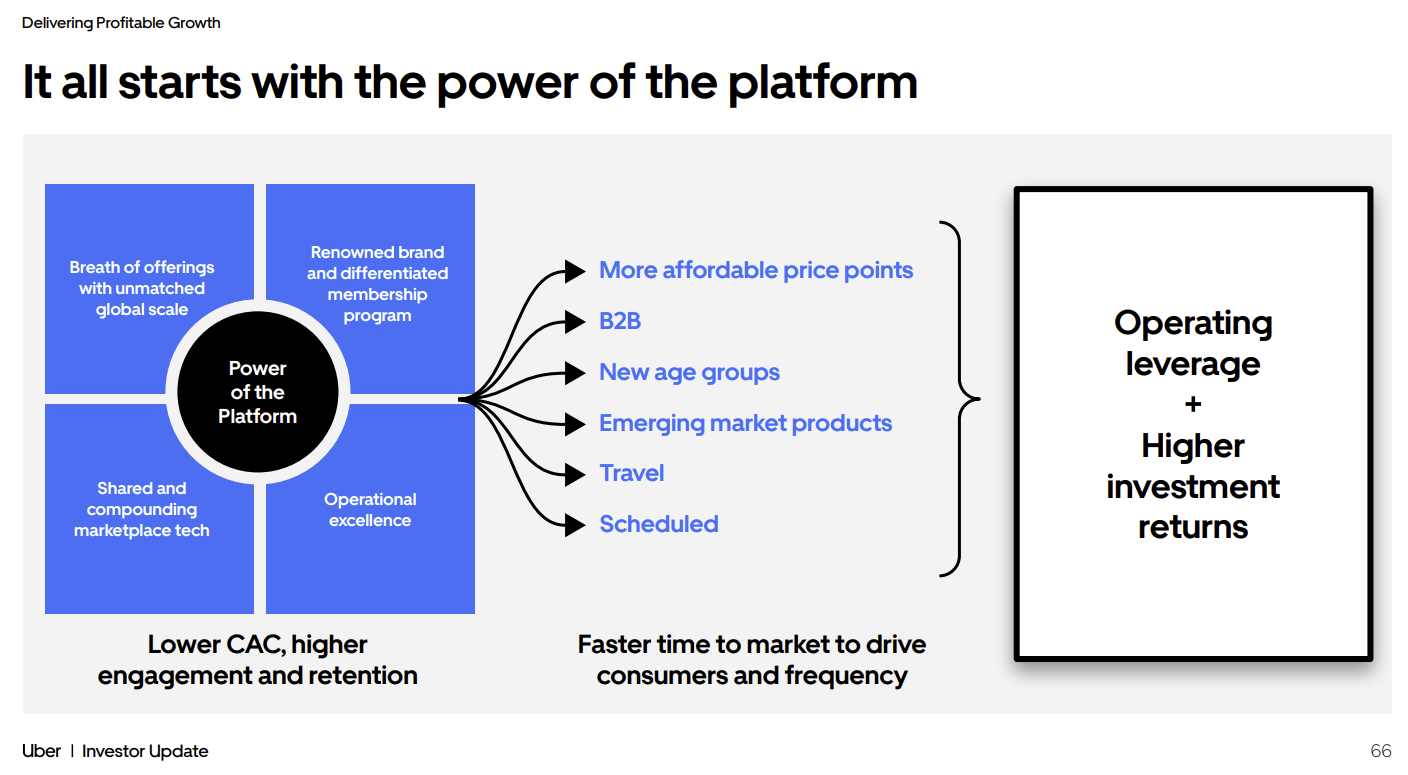
Uber's technology stack is its secret sauce. Khosrowshahi said the technology stack is the company's biggest advantage.
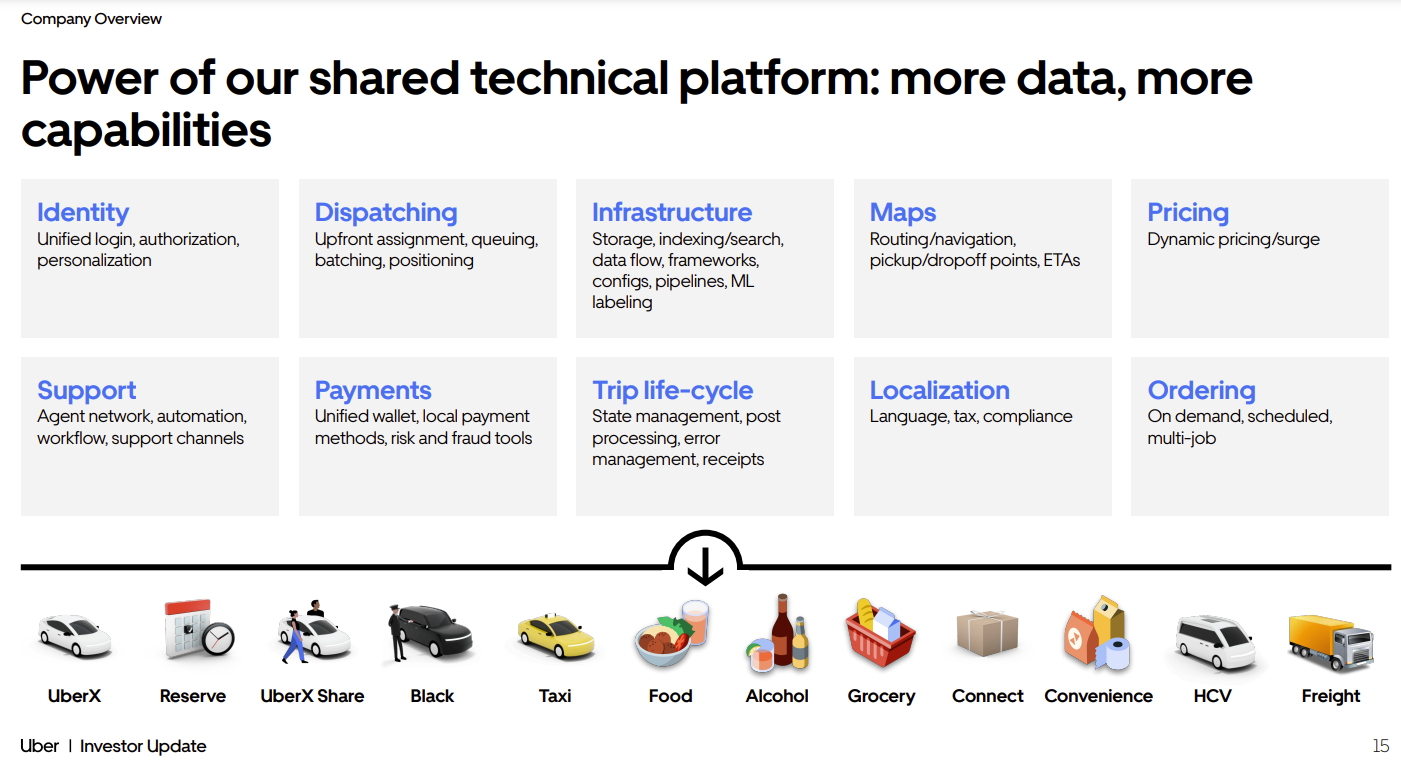
"While it may not always be visible to the casual user or investor, this really is our secret sauce. Whether you're ordering a ride or delivering much of the underlying tech and tech enabled operations, identity maps payments, fraud detection, ordering, dispatching, pricing and more. They're all shared across Uber," he said. "In fact, around 75% of our engineering resources are focused on these shared elements. This advantage is also self-reinforcing as the lessons we learn in one business can be applied elsewhere and technical investments we make in one area accrue to the whole platform."
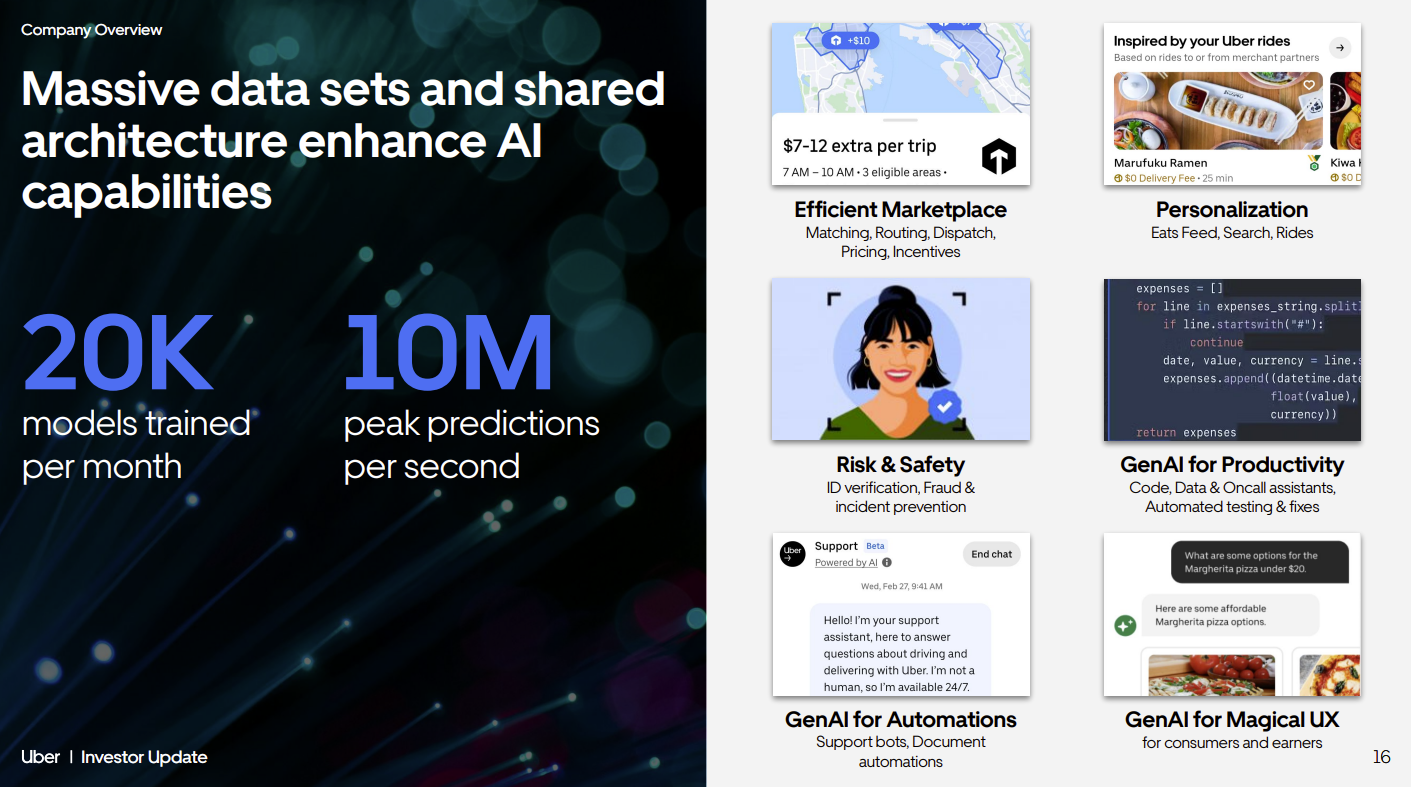
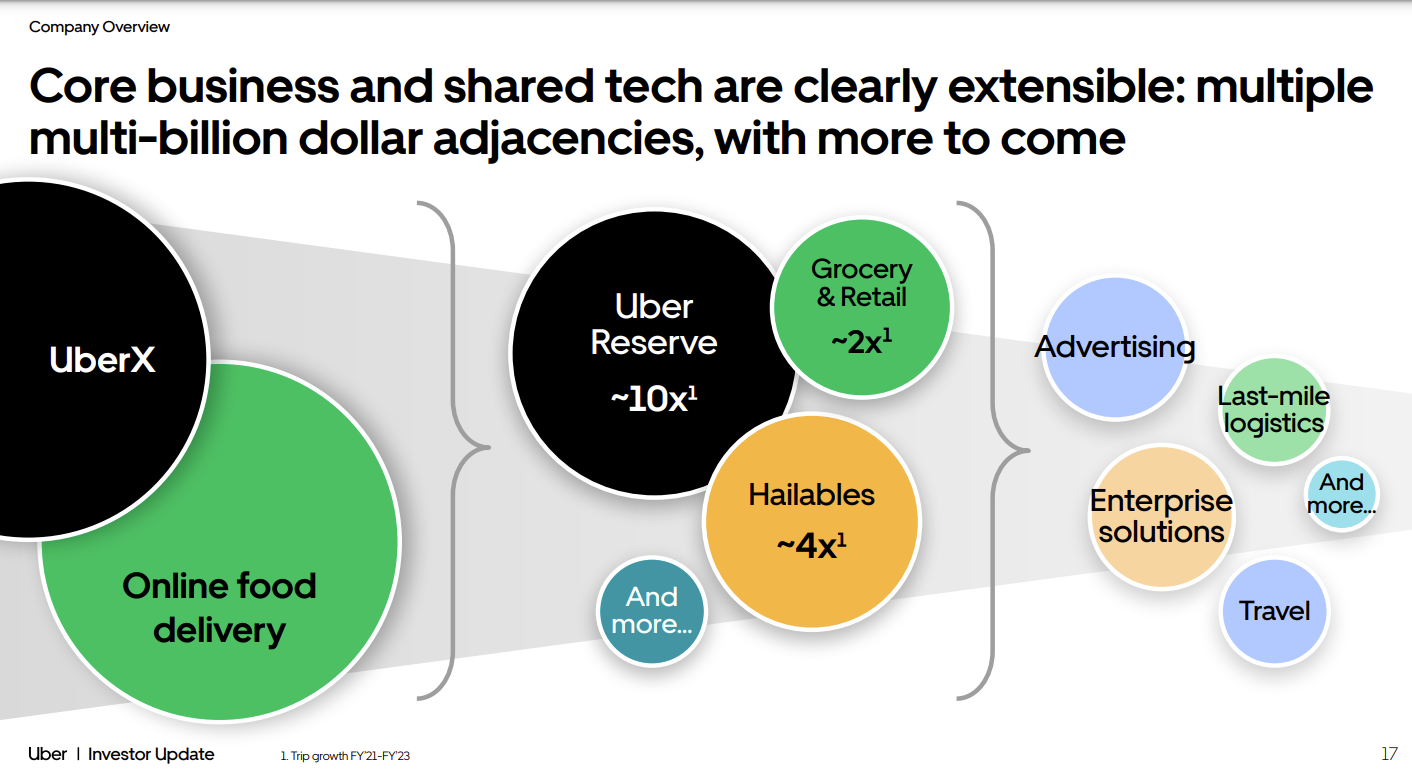
The tech stack and platform drive the datasets that drive AI. Khosrowshahi said Uber's shared architecture and platform drives the data loop that enables it to build predictive models, personalized offers, generative AI assistants and tools that can be used in new markets including advertising, travel, last mile delivery and enterprise.
Disruptive technologies are nice but keep the business goals in front. Khosrowshahi said the company's strategy is simple: "To build best in class products and then amplify them with the power of the platform."
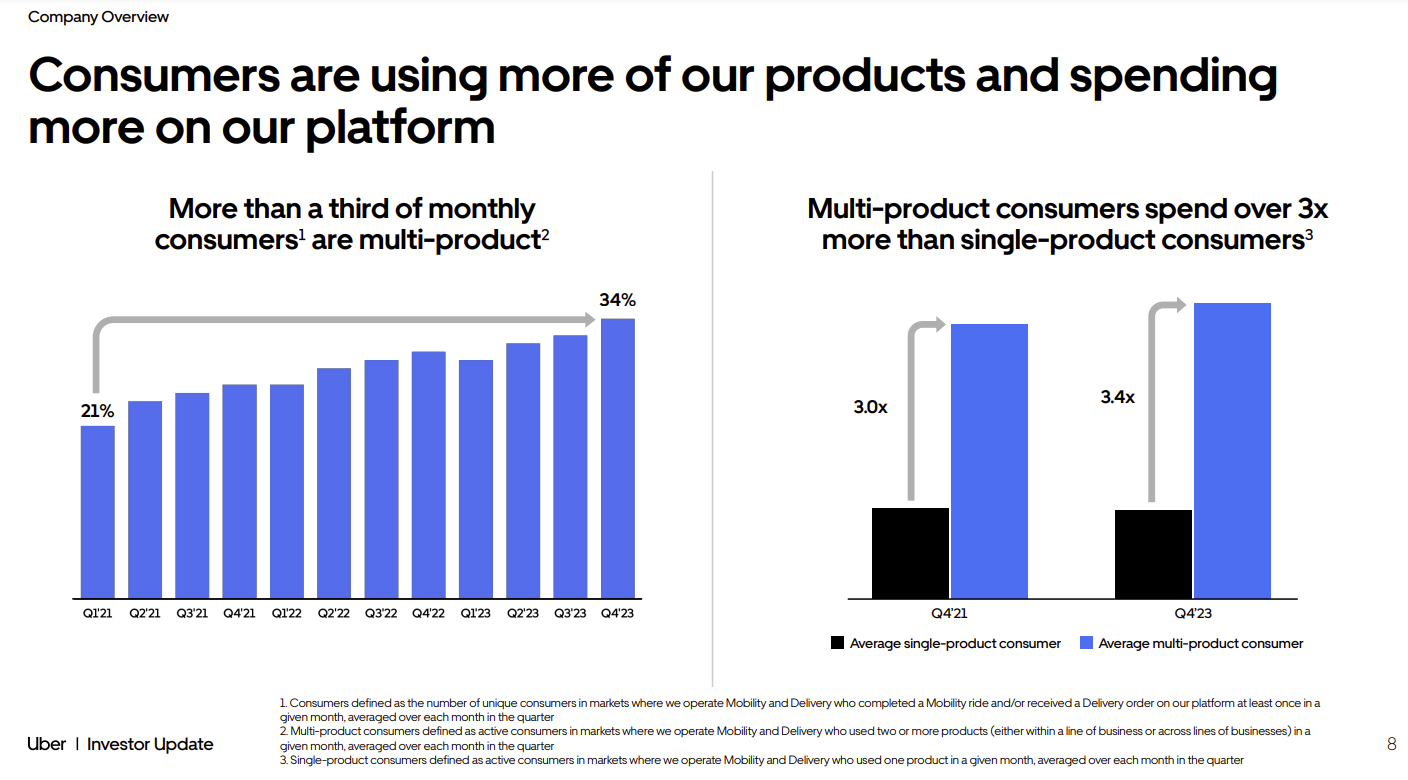
He added that Uber can acquire customers at a lower cost and generate higher customer lifetime values. "We want to bring in new consumers through our mobility and delivery apps and then convert them into Multi Product consumers both within and across segments," said Khosrowshahi.
Data and customer experience drives multi-product usage. Khosrowshahi said that more than a third of Uber users now use multiple products. "The mathematical advantage for Uber lies in the fact that consumers who use multiple products on average spend 3.4 times more than those who don't," he said. The simple truth is that in the end, math wins, and compounding only amplifies the win."
Khosrowshahi said:
"The more products and services we add to the platform, the more data we have and the more opportunities we have to make that particular pitch really compelling for the consumers at the right time. With the right incentives. And with shared identity and payments across all of our apps we can make it super simple, super easy to move from one app to the other, or one service to the other."
Loyalty programs also play into multi-product usage. Uber One now has 19 million members. Those members not only drive the data flywheel, but also spend more--3x more.
Simply put, frequency matters and Uber's growth depends on using multiple products and membership.
Khosrowshahi said:
"We have a product team that is focused on driving essentially AI driven offers to put in front of consumers. In the morning it might be coffee. In the evening, it might be dinner. If we see you reserve an on-demand trip to an airport we may say you can reserve next time. All of this is going to be driven by AI so we just have more shots on goal than anyone else."
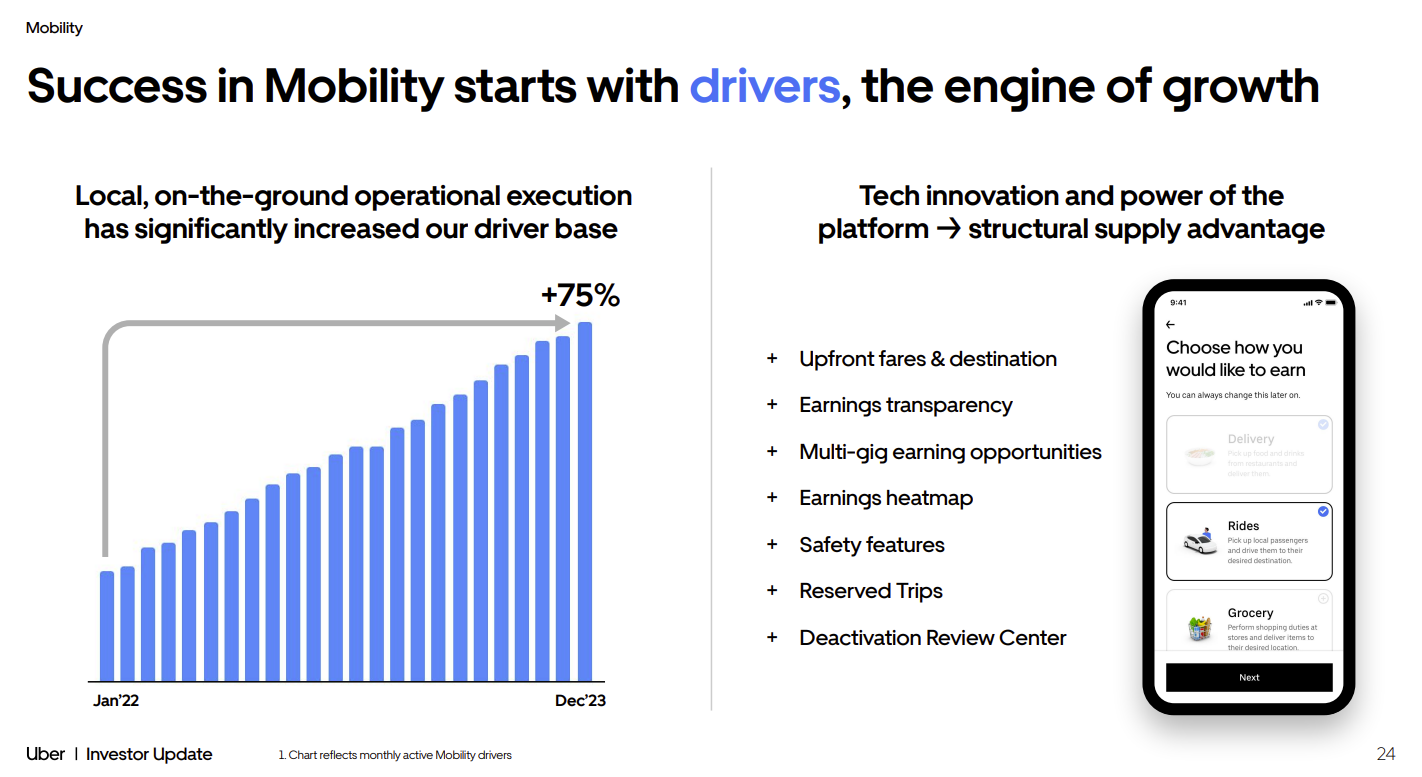
The platform and data strategy also drives the supply side of the equation. The running theme throughout Uber's Investor Day is that it needs to continue to recruit drivers organically on its own platform on multiple services. "The platform gives us a much more cost-efficient way of finding drivers than through external channels," said Khosrowshahi. "So, for example in the US, converting an existing courier into a driver is about half the cost of finding a new driver through third parties. This is a huge opportunity. In fact today 20% of first time drivers in the US have come from a courier pool."
This organic recruitment across multiple services is critical since Uber is expanding into healthcare transportation as well as a bunch of other areas.
Andrew MacDonald, Senior Vice President of Uber's Mobility and Business Operations, said the driver experience on the platform is critical. "Our tech teams have shipped hundreds of improvements to improve the driver experience," said MacDonald.
Uber's expansion into advertising is just starting. "The power of our advertising platform stems from what Uber users tell us every time they use our apps where they want to go and what they want to get. And as a result, we've got the unique ability to bring together both location based and shopping data with closed loop attribution across our mobility and delivery channels for both performance and brand campaigns," said Khosrowshahi.
In fact, Uber is combining consumer signals with its AI to automate offers on the fly.
Khosrowshahi said Uber will follow the data to balance advertising load and customer experience. "We run a certain percentage of our audience with no ads on a long-term cohort basis. And then we compare that audience behavior to audiences who are receiving ads and we make sure that the experience there isn't significantly different," he said. "You don't want to build an ad business that penalizes the customer experience."
Continuous improvement on costs is the mantra. Uber CFO Prashanth Mahendra-Rajah said data, technology and the platform can be leveraged to drive costs out of the business. He said:
"There's a term in the Uber lexicon called operating cost structure or OCS. OCS is a collection of capturing all costs between revenue and EBITDA. There is a team within Uber to grind out incremental cost efficiencies out of that OCS. When you think of what's in that cost bucket it breaks down into variable and fixed."
Examples of how the OCS team expands margins include implementing technology to optimize routing, incentivizing customers to use different payment options, reducing fraud costs with data and AI.