Results

SAP’s Joule everywhere plan: ‘We are not developing AI just for the sake of AI”

SAP’s Joule everywhere plan: ‘We are not developing AI just for the sake of AI”

SAP said it is infusing its Joule generative AI assistant throughout its platform and applications as it made the case that the company is using AI to drive business value.
Speaking at SAP Sapphire in Orlando, CEO Christian Klein had a few missions. First, Klein had to convince customers that its Business AI innovations were worth the upgrades and more than hype. Second, Klein wanted to ensure that SAP wasn't just doing AI because everyone else is. And third, Klein had to get its customer base more excited about programs like RISE with SAP and upgrading to S4/HANA and cloud.

"The Business AI innovations we're announcing will redefine the way businesses run," said Klein, who emphasized partnerships with AWS, Google Cloud, Meta and Microsoft. He added:

"You can see that we are not developing AI just for the sake of AI. Our vision at SAP is to leverage our holistic portfolio to deliver agility at scale, increase productivity of every user and achieve more across the value chain by connecting the material, the financial and the logistic workflows across the industries."

Amazon Bedrock integrated into SAP AI Core, SAP to use AWS chips | SAP's Q1: Net loss on restructuring, cloud revenue growth of 24%

The general theme behind SAP Sapphire is that AI will be embedded throughout enterprise applications and matter to multiple CXOs role. Klein's keynote was segmented by the appeal to CIOs, CFOs, COOs and HR leaders and the theme was that SAP would deliver insights without surfacing what's underneath--like various large language models and technology like Microsoft's Copilot. SAP's Joule would be the front end that would give data context and insights while automating processes.

SAP's plan is to enable Business AI to leverage multiple models. For instance, SAP and Google Cloud will integrate Joule and SAP Integrated Business Planning for Supply Chain with Google Cloud Gemini Models. SAP will use Meta Llama 3 to generate scripts in SAP Analytics Cloud. SAP will also integrate with Amazon Bedrock and add Mistral AI models. SAP's Klein also touted partnerships with Nvidia as well as Apple.

Here's a look at what was announced at SAP Sapphire:

  • SAP's Joule copilot has been integrated into SAP S/4HANA Cloud Public Edition, S/4HANA Cloud Private Edition, SAP Customer Data Platform, SAP BTP Cockpit, SAP Build, SAP Build Code and SAP Integration Suite.
  • SAP Ariba, SAP Analytics Cloud and multiple supply chain packages will get Joule in the second half of 2024.
  • Joule will be integrated in ERP and Finance apps to close books faster, process documents and provide visualizations and insights.
  • SAP SuccessFactors will get Joule to answer questions about policies and documents.
  • The company said that Joule will roll out to SAP's process mining and automation tools. Joule copilot will be integrated with SAP Build Process Automation, Signavio and SAP Integration Suite to make it easier to automate processes and workflows.
  • SAP is rolling out ABAP Developer capabilities in Joule to generate, complete and test ABAP code. SAP said it is fine tuning models on its proprietary ABAP code.
  • Supply chain applications will get Joule analysis of supply chain planning runs, logistics and transportation management.
  • SAP Intelligent Product Recommendation will get generative AI tools that estimate parameters for products. Plant managers in manufacturing industries will also interact with a digital twin to choose the proper products.
  • Sales and marketing applications will get a suite of AI tools to enhance customer experiences. A generative AI tool builder will be available in SAP Commerce Cloud, SAP Sales Cloud and SAP Service Cloud.

SAP will use genAI to improve implementations

SAP said that it will leverage Joule for consulting functions leveraging insights from SAP product documentation, community posts and training materials.

According to the company: "This capability is especially critical for supporting customers transitioning to SAP S/4HANA Cloud as part of the RISE with SAP program, helping to accelerate implementation projects and save money." 

SAP Sapphire kicks off as Constellation Research’s BT150 CXOs have gripes about SAP’s RISE programOur BT150 CXOs aren't alone. SAP's German speaking user group takes aim at cloud contracts, BTP and more | SAP user group DSAG rips S/4HANA innovation plans, maintenance increases | SAP retools for generative AI, cuts 8,000 jobs, sets 2024, 2025 ambition

The consulting copilot, available in the second half of 2024, leverages Nvidia's NeMo Retriever microservices to generate insights.

SAP noted that Joule's consulting capabilities have been tested via SAP certification exams. PwC and Deloitte plan to deploy Joule as a consultant.

Partnerships with Accenture, McKinsey and Boston Consulting Group to use SAP Signavio and LeanIX round out the consulting theme.

In addition, SAP said it has expanded its SAP Business Transformation Center to offer a new way for customers to migrate from SAP ECC to SAP S/4HANA Cloud Private Edition.

The new capability gives customers a system to choose a "lean selective data transition" and eliminate legacy data to build a clean foundation. This scenario is included in SAP cloud subscriptions and RISE with SAP.

Constellation Research's take

Constellation Research analyst Holger Mueller said:

"SAP is making progress with its AI strategy. Like fellow multi-cloud vendor Workday, SAP is at a speed disadvantage when it comes to AI as it first needs to create an abstraction layer to be able to run AI on all key cloud partners (AWS, Azure & Google Cloud). Microsoft and Oracle have their own clouds for applications. What is still missing is a lakehouse or similar architecture to create a data foundation for AI, and again SAP needs to provide multi-cloud support. Partner support and attention is at a maximum, which is good for SAP customers – with AWS and Microsoft Azure announcing 32TB memory systems to run S/4HANA. It was disappointing that the only keynote customer reference was a SAP customer that was spun out from a larger company. SAP needs to do better to present a North American references for S/4 HANA in the cloud." 

More on genAI:

Data to Decisions Digital Safety, Privacy & Cybersecurity Innovation & Product-led Growth Tech Optimization Future of Work Next-Generation Customer Experience SAP AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer Chief Executive Officer Chief AI Officer Chief Analytics Officer Chief Product Officer

AMD outlines new GPUs, Instinct accelerators with annual cadence

AMD outlines new GPUs, Instinct accelerators with annual cadence

AMD outlined its AI GPU roadmap and moved to an annual cadence as it aims to compete with Nvidia.

A day after Nvidia outlined its GPU roadmap at Computex, AMD CEO Lisa Su outlined an annual cadence. The company also outlined new EPYC CPUs along with processors for AI PCs.

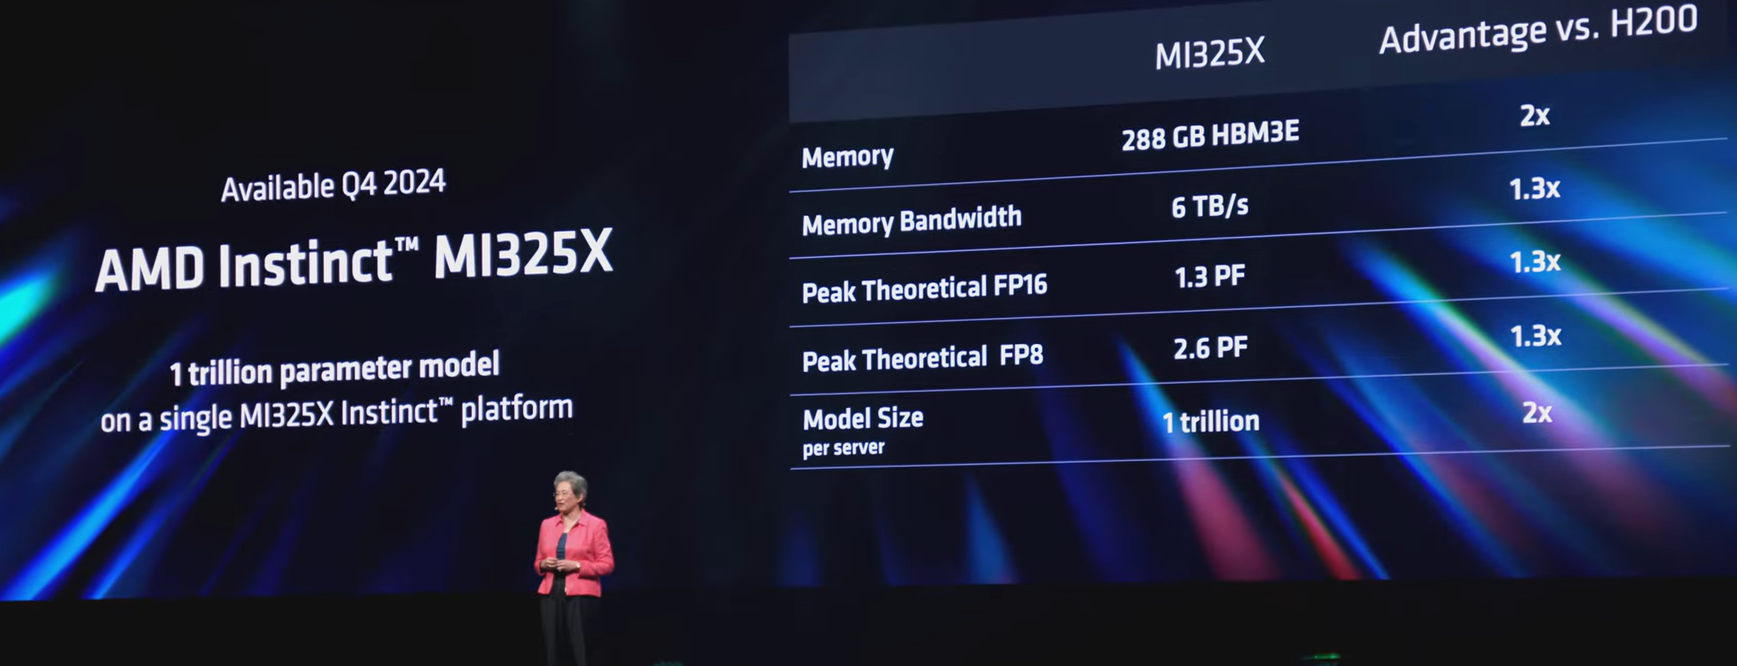
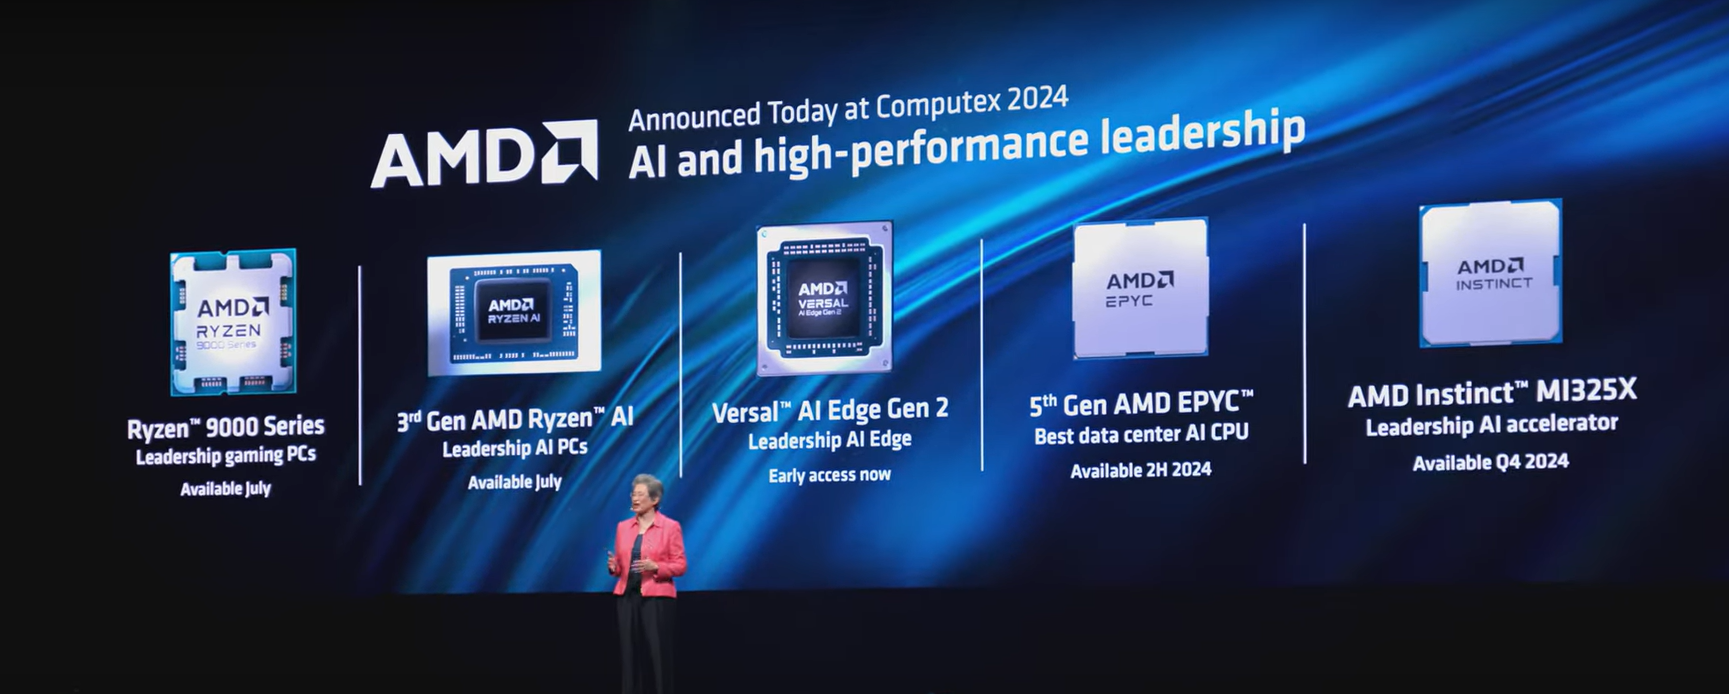
Su said the new AMD Instinct MI325X accelerator will be available in the fourth quarter with up to 288GB of HBM3E memory and 6 terabytes per second of memory bandwidth with new AMD Instinct MI350 accelerators based on AMD's CDNA 4 architecture available in 2025.

According to AMD, the AMD Instinct MI325X accelerator will bring a 35x increase in AI inference performance compared to the AMD Instinct MI300.

In 2026, the AMD Instinct MI400 series will be based on AMD CDNA "Next" architecture.

AMD's Instinct MI300X accelerators are being rolled out by Microsoft Azure, Meta and major server makers such as Dell Technologies, HPE and Lenovo.

Su also touted AMD's software ecosystem, which is playing catchup to Nvidia. AMD said its AMD ROCm 6 open software stack is developing its connections to popular AI frameworks.

Other AMD items of note at Computex include:

  • AMD previewed 5th Gen AMD EPYC server processors to launch in the second half of 2024. These processors, codenamed Turin, are designed to continue AMD's server momentum with CPUs.
  • AMD outlined the AMD Ryzen AI 300 series, the third generation of AMD AI-enabled mobile processors. These chips will be used in AI PCs and Copilot+ PCs, which are now powered by Qualcomm.
  • AMD highlighted its AMD Ryzen 9000 Series processors for laptops and desktops.
  • The company also highlighted its next-gen Zen 5 CPU core and AMD XDNA 2 NPU core.
  • AMD also announced the AMD Radeon PRO W7900 Dual Slot workstation graphics card.

More on genAI:

Data to Decisions Innovation & Product-led Growth Future of Work Tech Optimization Next-Generation Customer Experience Digital Safety, Privacy & Cybersecurity AMD Big Data AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer Chief Executive Officer Chief AI Officer Chief Analytics Officer Chief Product Officer

GenAI boom eludes enterprise software...for now

GenAI boom eludes enterprise software...for now

The great generative AI boom for enterprise software isn't happening yet as sales cycle grow longer due to platform bets, macroeconomic conditions and cost of capital crimping budgets.

What's really happening: Enterprise technology buyers aren't buying into grand enterprise software copilots, picking sides in large language models (LLMs) and platform bets that could easily equate to technology debt if they're not careful. It's also clear that generative AI projects are stealing budget dollars from enterprise software purchases.

Simply put, we're in the pick and shovel phase of the AI buildout and that means Nvidia, server makers and that's about it. Rest assured we'll see the indigestion from the AI capacity buildout too, but that's months if not years away.

The recent earnings parade from enterprise software companies highlights the big hurry up and wait approach when it comes to AI. Here's a tour.

Salesforce predicted single digit revenue growth amid longer sales cycles. CEO Marc Benioff defended the company's first quarter disappointment and played up the long game. "When you look at the power of AI, you realize the models and the UI are not the critical success factors, it's not critical where the enterprise will transform. There are thousands of these models, some open source and some closed source models, some built with billions, some with just a few dollars, most of these will not survive," said Benioff. "They are just commodities now and it's not where intelligence lies. And they don't know anything about a company's customer relationships."

Benioff added that customers are flocking to Data Cloud, which has more than 1,000 customers. Operating chief Brian Millham, however, noted that "we continue to see the measured buying behavior similar to what we experienced over the past two years and with the exception of Q4 where we saw stronger bookings."

This post first appeared in the Constellation Insight newsletter, which features bespoke content weekly and is brought to you by Hitachi Vantara.

Millham added that "customers are getting their data estate in order as a precursor to leveraging AI capabilities, and we're seeing that with the growth of Data Cloud right now."

Nutanix said sales cycles are longer and more unpredictable. Nutanix is battling VMware, but CEO Rajiv Ramaswami noted that the company is seeing larger opportunities that "tend to have longer sales cycles can involve aggressive competitive responses and exhibit great variability with respect to timing and outcome." Nutanix isn’t a direct generative AI play, but has GPT-in-a-Box and is often lumped into a broader transformation plan.

Workday said the buying cycle is choppy. Workday CEO Carl Eschenbach reiterated comments made on the company's first quarter conference call at the Jefferies Software Conference. He said: "Last year was a pretty solid year for most software companies. I think this year, people do talk about a slightly different macro that they're dealing with. They use terms like it's choppy--it's uncertain, it's uneven. And I just think when people are going to invest in technology, they're really thinking hard and deeply about where they're going to make those investments. And I think for all of us in the software space, you have to have a strong value proposition to make sure you're a priority."

MongoDB cut its outlook for second quarter and fiscal year. CEO Dev Ittycheria said, "we had a slower than expected start to the year for both Atlas consumption growth and new workload wins, which will have a downstream impact for the remainder of fiscal 2025."

Ittycheria said MongoDB still had a large opportunity to gain share and become a standard and that it will be "a substantial beneficiary of this next wave of application development" revolving around AI. For now, MongoDB saw lower consumption due to a spotty macroeconomic environment and go-to-market changes.

UiPath's first quarter had a lot of issues, but longer sales cycles were one of them. Sure, UiPath's quarter was a disaster as CEO Rob Enslin resigned, but deliberation time for purchases was also extended. Incoming CEO Daniel Dines said: "While we had a healthy start to the quarter, we saw the pace slow as we progressed through the second half of March and into April. This was primarily due to the impact of a challenging macroeconomic environment that we see persisting with mid-market customers, as well as a change in customer behavior particularly with large multi-year deals."

These enterprise software executives aren't seeing the generative AI boom yet, because the technology hasn't really hit the application layer. And when genAI drives enterprise software deals it's unclear whether buyers are going to swallow copilot upcharges. Today, the genAI spending is on infrastructure moving into tools and data platforms and then hitting applications.

In the end, enterprise software valuations moved too far too fast without anything to back them up. Constellation Research CEO Ray Wang said, "valuations without cash flow are the key issues." Wang noted the buy and sell side of enterprise tech are dealing with three factors driving the market.

  • Exponential efficiency is forced by 5% interest rates.
  • AI arbitrage as we replace human work.
  • Margin compression as new business models require a 10X improvement at 1/10 the cost.

Not every enterprise software play is struggling. C3 AI reported a better-than-expected first quarter but is showing growth on a much smaller base than the companies that were pummeled over recent quarters. C3 AI is also working a layer above the application providers seeing longer sales cycles. C3 AI CEO Tom Siebel said the genAI era will rhyme with previous technology cycles:

"The AI era will be no different and the same game is going to play out as we move forward. The bulk of the value is going to accrue to the applications that leverage the entire AI stack and deliver value to the business. Silicon will get commoditized. It always gets commoditized. Infrastructure will get commoditized. It always gets commoditized. What doesn't get commoditized in the long run are the applications and that's where C3 AI plays."

If Siebel is right--and there's no reason to think he's wrong--genAI will drive enterprise software for years to come. When this evolution plays out is anyone's guess.

More on genAI:

Data to Decisions Next-Generation Customer Experience Future of Work Innovation & Product-led Growth New C-Suite Tech Optimization Digital Safety, Privacy & Cybersecurity ML Machine Learning LLMs Agentic AI Generative AI Robotics AI Analytics Automation B2B B2C CX EX Employee Experience HR HCM business Marketing Metaverse developer SaaS PaaS IaaS Supply Chain Quantum Computing Growth Cloud Digital Transformation Disruptive Technology eCommerce Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP Leadership finance Social Healthcare VR CCaaS UCaaS Customer Service Content Management Collaboration M&A Enterprise Service GenerativeAI Chief Information Officer Chief Executive Officer Chief Technology Officer Chief Data Officer Chief Digital Officer Chief Analytics Officer Chief Financial Officer Chief Operating Officer Chief Marketing Officer Chief Revenue Officer Chief AI Officer Chief Information Security Officer Chief Product Officer

Nvidia outlines roadmap including Rubin GPU platform, new Arm-based CPU Vera

Nvidia outlines roadmap including Rubin GPU platform, new Arm-based CPU Vera

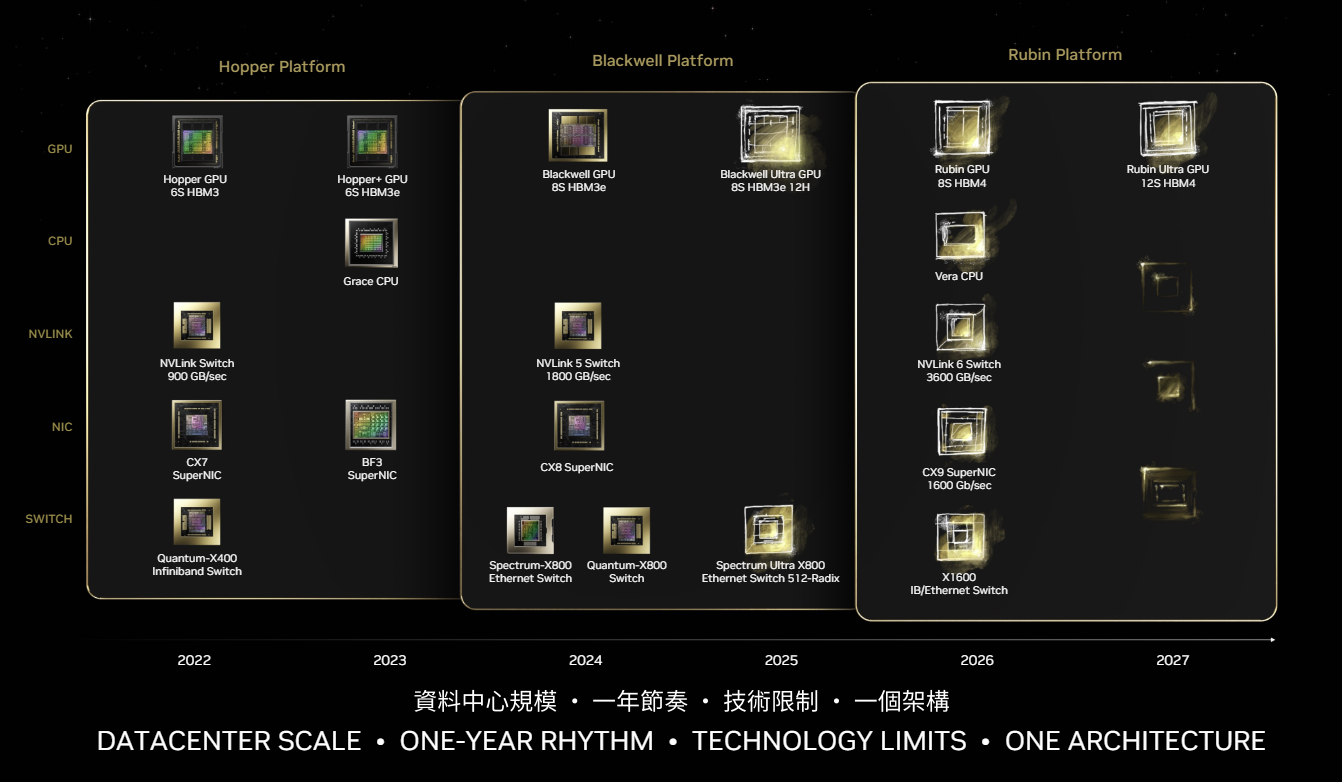
Nvidia CEO Jensen Huang outlined the company's roadmap through 2027 including a new GPU platform called Rubin, a new CPU in Vera and networking gear. Huang added that Nvidia will follow an annual cadence.

Speaking at Computex in Taipei on Sunday, Huang said, "our company has a one-year rhythm. Our basic philosophy is very simple: build the entire data center scale, disaggregate and sell to you parts on a one-year rhythm."

Huang's talk served as a sequel to his GTC keynote with some highlights for the years ahead. Nvidia’s revenue has surged amid the AI boom.

At a high-level:

  • 2025: Nvidia will launch the Blackwell Ultra GPU and Spectrum Ultra X800 Ethernet Switch 512-Radix. Nvidia has been pushing hard into AI networking with the launch of NVLink 5 Switch, CX8 SuperNIC, Spectrum-X800 Ethernet Switch and Quantum-X800 Switch.
  • 2026: The company will launch the Rubin GPU, Vera CPU, NVLink 6 Switch, CX9 SuperNIC and X1600 InfiniBand/Ethernet Switch.
  • 2027: Rubin Ultra GPU will launch along with three other-yet-to-be-named items.

In a nutshell, Nvidia is launching new platforms on even-numbered years with updates and enhancements in odd numbered years.

The move into CPUs is notable, but not unexpected. Huang said that the combination of integrated GPUs and CPUs can boost speed by 100x while only increasing power consumption by a factor of three. If this Nvidia cadence sounds familiar that's because it rhymes with how smartphone makers operate. There's a big splash in one year, followed by an incremental update and then rinse and repeat.

Here's a look at other items from Nvidia at Computex:

  • Nvidia said its Nvidia ACE generative AI microservices were available. These technologies are designed to make it easy to animate and operate digital humans that can be used in multiple industries. These digital humans could be deployed across 100 million RTX AI PCs.
  • Nvidia NIM inference microservices are available for download by developers. NIM was outlined at GTC.
  • ASRock Rack, ASUS, GIGABYTE, Ingrasys, Inventec, Pegatron, QCT, Supermicro, Wistron and Wiwynn will all build systems based on Nvidia's latest chips for everything from cloud, data center and edge systems.
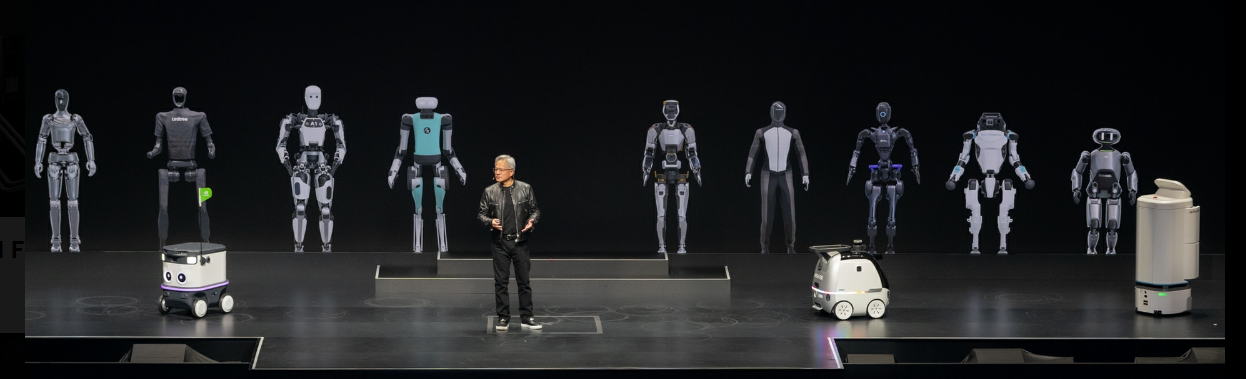
  • Delta Electronics, Foxconn, Pegatron and Wistron are using Nvidia reference designs to build, simulate and operate their robotics-enhanced facilities. Huang appeared on stage with a series of robots powered by Nvidia's platforms.


Data to Decisions Tech Optimization Innovation & Product-led Growth Future of Work Next-Generation Customer Experience Digital Safety, Privacy & Cybersecurity nvidia Big Data AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer Chief Executive Officer Chief AI Officer Chief Analytics Officer Chief Product Officer

5 technology lessons from Boston's pro sports team CIOs

5 technology lessons from Boston's pro sports team CIOs

Sports teams have unique technology requirements, vendor relationships and the challenge of melding digital and physical experiences. In the end, running the technology infrastructure is the ultimate customer service and relationship game.

DisrupTV caught up with the CIOs from the Boston Red Sox, Bruins, Celtics and New England Patriots this week.

Here are some of the takeaways from Michael Israel, CIO New England Patriots, Josh Carley, VP, Technology, TD Garden & Boston Bruins, Brian Shield, SVP, CTO Boston Red Sox and Jay Wessland, CTO Boston Celtics.

Melding the customer and digital experiences. Shield said the challenge for a ballpark like Fenway is building out technology while keeping the ballpark's legacy and appeal intact. Behind the scenes, the Red Sox want to be as predictive as possible. Shield said:

"You want to know everything that is happening at concessions and attendance, but the way we're delivering the data is much different. In the past you'd put it in a report or dashboard. Today you want AI to predict what's happening."

Wessland said technology in the NBA has moved well beyond video into every part of operations. As a result, you have to pick projects selectively with smaller teams.

Carley said that technology has to provide value to the guests. "From a leadership perspective I've had to differentiate fandom from the business. Once you disconnect them you have to reconnect them somehow for engagement," said Carley. "I want  a ring just as much as the guys on the ice do."

Learning to juggle. Israel runs IT for Gillette Stadium as well as the businesses of the Kraft Group, which includes the Patriots. Fan and customer engagement, point-of-sale experiences and how technology is used are all on the to-do list during an event. "I don't think I've watched 15 minutes of a football game in the time, I've been here," said Israel.

Shield said a sports team CIO has to blend multiple skills together including digital leadership, software engineering, product engineering and customer service.

Building teams. All of the CIOs from the Boston sports teams have relatively small staffs relative to other enterprises. As a result, team building is critical. Staff development is critical and as a team you want a core technology group, some free agents via consultants and contractors, a few hall of famers and all stars. Player development is critical. "I will meet you halfway if you're going to invest in yourself and I will be investing in you and that has been throughout my career," said Israel.

Collaboration. Sports team CIOs have unique challenges and the four leaders across the Boston sports teams frequently meet up to talk shop. That collaboration has moved down the hierarchy to staff. "There are a lot of things that apply to the average business, but there are a lot that's unique," said Wessland.

The information exchange among the teams is critical when staying ahead of emerging trends and how they would apply to the fan experience.

Vendor management and strategy. The Boston sports CIOs said they lean heavily on vendors to be more strategic partners.

"We have a lot of vendors and we're trying to make sure that we're always best of breed, and evaluating them against one another," said Shield. "It's thinking about it as sports franchise as a service across Fenway Sports Group."

Requirements for a sports franchise technology vendor include the following:

  • Implementation help in the sales process as well as usage. Implementing a tool that has 50 features and you're using three doesn't work.
  • Post sales services. Sports CIOs expect an ongoing relationship. The marriage experience has to be better than the courtship.
  • Ability to scale projects in a time frame. Sports CIOs said that the offseason is the season for technologies projects and upgrades.
  • Realizing sports teams are unique. Technology vendors often view sports teams as big wins, but it's an opportunity and a threat. The Boston sports team CIOs all noted that executives throughout the leagues all talk. If a vendor is doing a great job it can go from one club to 20 clubs quickly. If a technology vendor doesn't deliver for one team it isn't going to expand to others because all of the CIOs talk.

Wessland summed it up:

"The one rule I have about vendors is that everybody makes mistakes, everything gets into trouble. Everybody screws up. Good vendors know how to correct mistakes, get themselves out of trouble and move forward and go on. That's a partnership. A bad vendor gets into trouble and can't get themselves out. Those are the vendors you can't work with. We have vendors that are also sponsor partners and all of those combinations. The expectations are the same from a vendor standpoint. They have to be a good vendor. It's got to be good relationship."

New C-Suite Marketing Transformation Next-Generation Customer Experience Data to Decisions Innovation & Product-led Growth Future of Work Tech Optimization Digital Safety, Privacy & Cybersecurity Leadership ML Machine Learning LLMs Agentic AI Generative AI AI Analytics Automation business Marketing SaaS PaaS IaaS Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP finance Healthcare Customer Service Content Management Collaboration Chief Information Officer Chief Experience Officer Chief Executive Officer Chief Technology Officer Chief AI Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Product Officer

MongoDB cuts second quarter outlook

MongoDB cuts second quarter outlook

MongoDB cut its second quarter and fiscal 2025 outlook as the company said it saw slower than expected demand for Atlas consumption and new workloads.

The company's outlook came amid a solid first quarter. The company reported a net loss of $80.6 million, or $1.10 a share, on revenue of $450.6 million, up 22% from a year ago. Non-GAAP earnings in the first quarter were 51 cents a share.

MongoDB was expected to report non-GAAP earnings of 37 cents a share on revenue of $439.91 million.

The problem for MongoDB is that the first quarter growth for its Atlas platform was slower than expected even though it was up 32% from a year ago. In addition, MongoDB's outlook was light in the previous quarter too

CEO Dev Ittycheria said, "we had a slower than expected start to the year for both Atlas consumption growth and new workload wins, which will have a downstream impact for the remainder of fiscal 2025." He elaborated on the earnings call:

"Atlas consumption growth was below our expectations in the first quarter. We saw less seasonal improvement than expected, and this dynamic was true with customers across tenure, industry, size, and geography. We believe this indicates a more challenging macro environment than expected at the beginning of the year. A new dynamic we saw in Q1 was the growth rate of more recently acquired workloads started to slow down earlier than expected. While the macro environment had an impact, we also believe this is probably due to the go-to-market changes we instituted last year."

Ittycheria said MongoDB still had a large opportunity to gain share and become a standard and that it will be "a substantial beneficiary of this next wave of application development" revolving around AI.

As for the outlook, MongoDB projected second quarter revenue between $460 million and $464 million with non-GAAP earnings of 46 cents a share to 49 cents a share. Analysts were modeling revenue of $471.54 million with non-GAAP earnings of 57 cents a share.

Fiscal 2025 revenue will be between $1.88 billion to $1.90 billion with non-GAAP earnings of $2.15 a share to $2.30 a share.  Wall Street expected fiscal year revenue of $1.94 billion with non-GAAP earnings of $2.43 a share.

Earlier this month, MongoDB outlined its product and business strategy. The general idea is that MongoDB aims to become a standard and a platform for AI application development. That vision is on track, but enterprises are moving slower than anticipated.

MongoDB outlined a few areas it will fix. 

  • The company is focusing on workload acquisition across new and existing customers. 
  • MongoDB will increase investments in its enterprise channel. 
  • It will focus on large accounts that drive the most return. 
  • Build out the MongoDB ecosystem. The company landed Accenture as its first system integrator to join the MongoDB AI Application Program.
  • MongoDB will invest in the high-end in the market and said it was optimistic about companies accelerating legacy app modernization with AI. "We recently completed the first two Gen.AI powered modernization pilots, demonstrating we can use AI to meaningfully reduce the time, cost, and risk of modernizing legacy relational applications," said Ittycheria. "We see that AI can significantly help with analyzing existing code, converting existing code, and building unit and functional tests. Based on our results from our early pilots, we believe that we may be able to reduce the effort needed for app modernization by approximately 50%. We have a growing list of customers across different industries and geos who want to participate in this program."

Ittycheria was asked about the broader software slowdown across categories. He said:

"I have been through multiple cycles. With every cycle, when you go back all the way to the mainframe, to client server, to the internet, and now cloud and mobile, the cost of building applications went down. You saw an explosion of more apps and consequently more data. With AI, you're going to see a step-fold increase in the number of apps  being built to run businesses. But that's going to take some time. As with any new adoption cycle, the adoption happens to what people commonly refer to as S-curves. And I think we're going through one of those S-curves when I see the macro environment. Partly it's related to this technology transition, but partly it's also related that the macro environment is not great.

What we talk about in macro, remember, ultimately we're a database or a data platform and the usage of our platform is directly or very tightly correlated to the performance of the end-customer's business. If they're selling 100 widgets a week and all of a sudden now they're selling 80 widgets a week, that will mean that they're using the database less intensely. So when we see broad-based slowdown across different customer cohorts of different sizes, across different industries and across different geos, that strikes us as pretty much a macro issue.

We have close to 50,000 customers, so we have a pretty good feel for what's happening right now. And that's why we feel that there's definitely a macro element to it. With regards to AI essentially crowding out new business, we definitely think that that's plausible."
 

Data to Decisions Innovation & Product-led Growth Future of Work Tech Optimization Next-Generation Customer Experience Digital Safety, Privacy & Cybersecurity mongodb AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Executive Officer Chief Technology Officer Chief AI Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Product Officer

Dell Technology sees Q1 AI-optimized server demand surge

Dell Technology sees Q1 AI-optimized server demand surge

Dell Technology reported better-than-expected first quarter results and said it saw strong demand across traditional and AI optimized servers.

The company reported first quarter net income of $955 million, or $1.32 a share, with revenue of $22.24 billion, up 6% from a year ago. Non-GAAP earnings in the first quarter were $1.27 a share.

Dell was expected to report first quarter earnings of $1.26 a share (non-GAAP) on revenue of $21.64 billion.

Dell Technologies goes all-in on AI factories

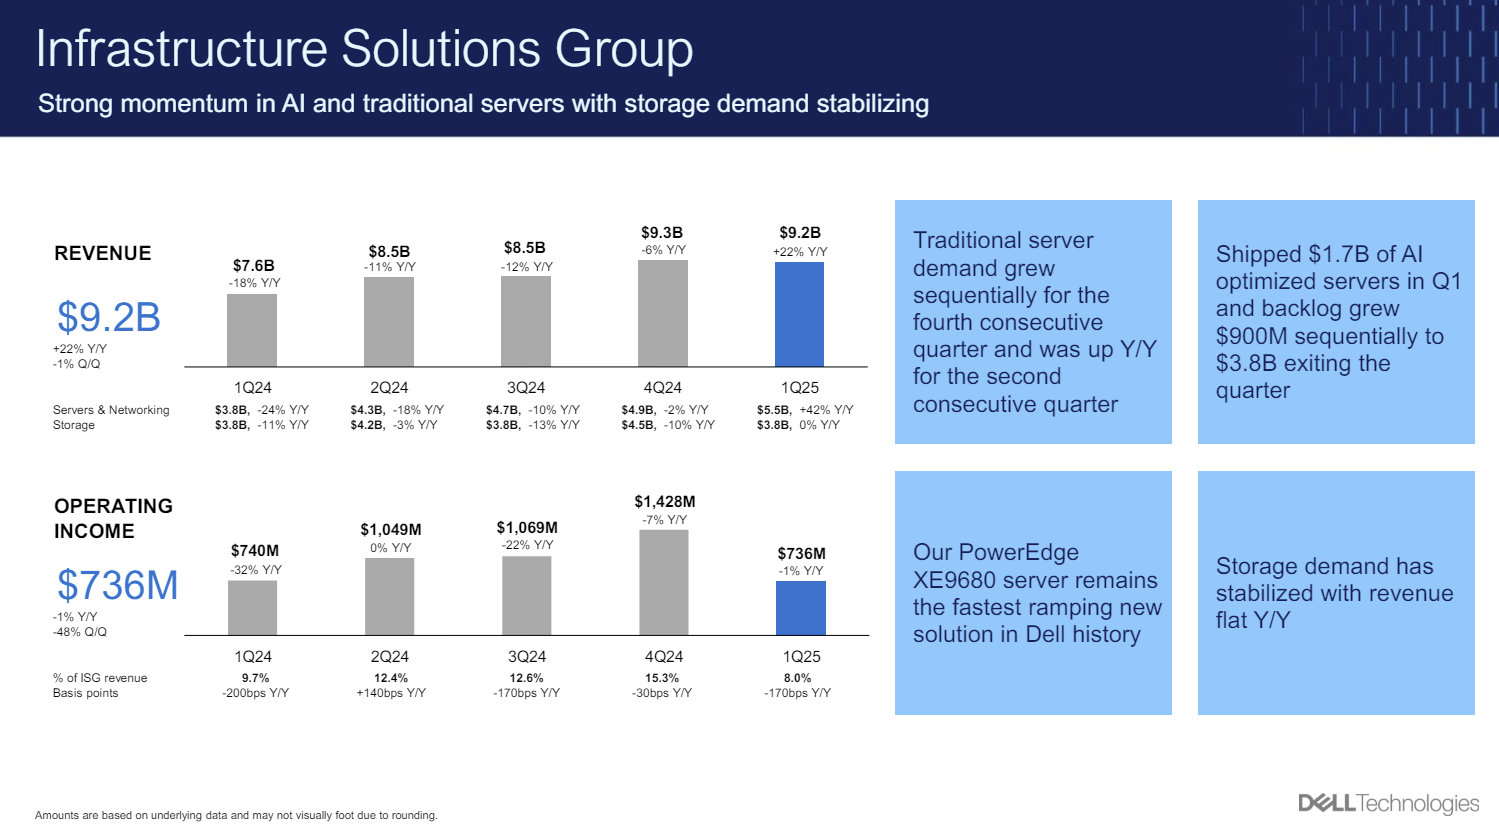
By unit, Dell said its infrastructure solutions group (ISG) had revenue of $9.2 billion, up 22% from a year ago. Server and networking revenue was a record $5.5 billion, up 42% from a year ago. The company said that it saw strong demand for AI and traditional servers. Storage revenue was flat at $3.8 billion.

ISG had first quarter operating income of $732 million.

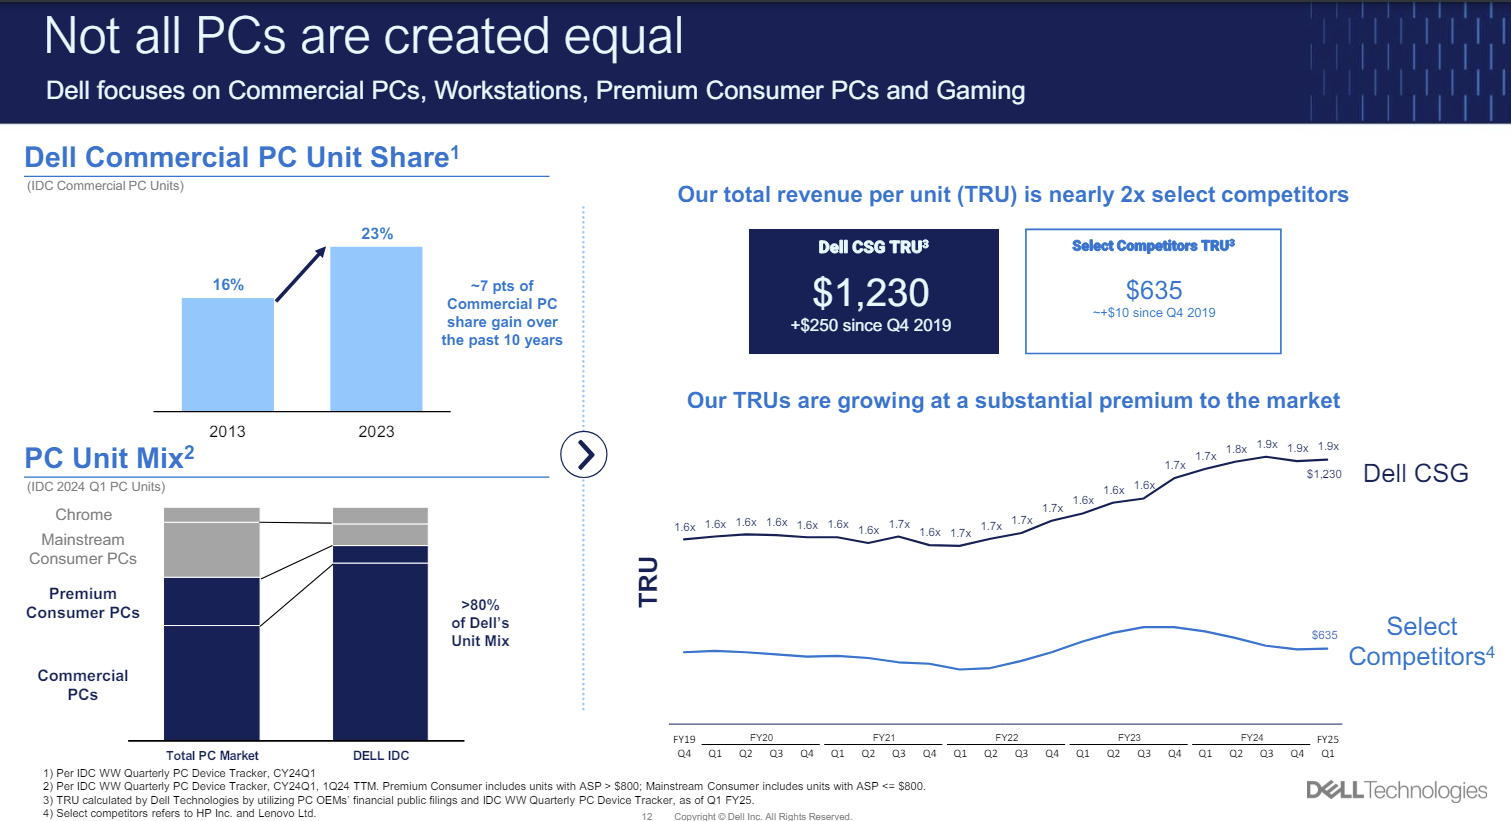
For the PC unit, Dell reported first quarter revenue of $12 billion, flat from a year ago. Commercial revenue was $10.2 billion, up 3% from a year ago, and consumer sales were $1.8 billion, down 15%. Operating income in the quarter was $732 million.

Jeff Clarke, Chief Operating Officer, said AI-optimized server orders were $2.6 billion with shipments up more than 100% to $1.7 billion. Dell added that backlog for AI-optimized servers were up 30% in the first quarter to $3.8 billion.

In prepared remarks, Clarke said the company has "seen an expansion in the number of enterprise customers buying AI solutions." He added that commercial PC demand has stabilized.

The company gave a mostly in-line outlook for the second quarter and fiscal year:

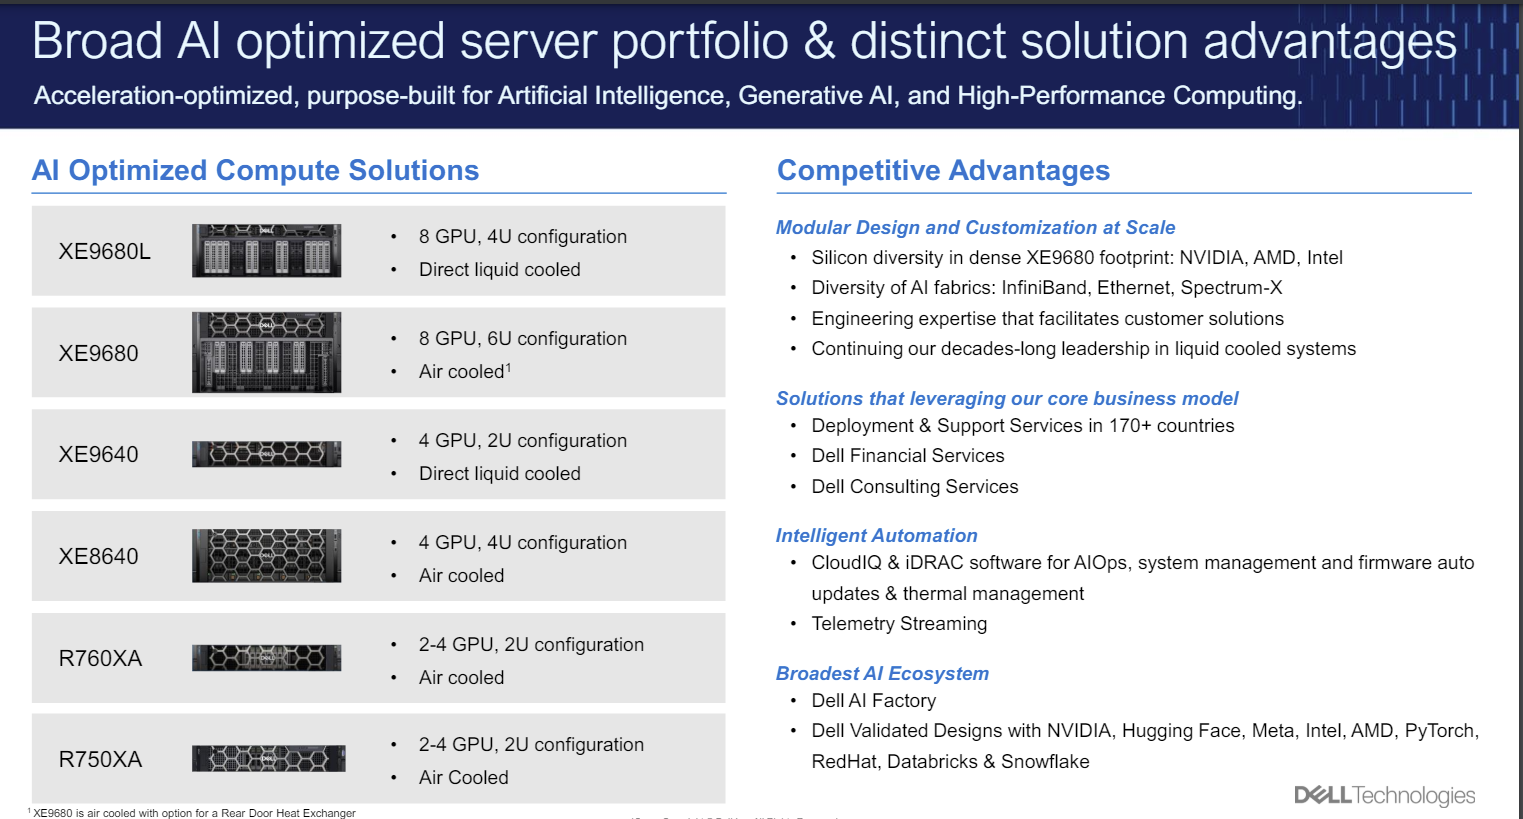
  • AI momentum will continue and modular AI optimized servers are scaling with customers. 
  • "The macro environment is still dynamic" and "indicators point toward a stabilization."
  • Dell sees fiscal 2025 revenue between $93.5 billion and $97.5 billion, up 8% at the midpoint. 
  • Infrastructure solutions group revenue will grow more than 20%. 
  • Non-GAAP earnings for fiscal 2025 will be about $7.65 a share, give or take 25 cents a share. 
  • For the second quarter, Dell projected revenue between $23.5 billion and $24.5 billion with non-GAAP earnings of $1.65 a share, give or take 10 cents a share. 
     

Speaking on the earnings call, Clarke said the AI-optimized servers for now are mostly Nvidia-based systems. He said:

"The lead times on our product varies and is complicated. We have product transitions from H100 to H200, outselling GB200 and B200. Those are customer allocated. So to say that there's an average lead time for our product is very dependent on the customer, what technology we're talking about. But in average, if it was just looking at the availability of parts, the H100 lead time is better. Those products are in full production. NVIDIA is meeting demand, and they'll have availability of the H200 on schedule towards the second or the latter part of Q2. So it's in production, as is the B200. So that's where the backlogs slash lead times are. When you look at the composition of our backlog, it's primarily NVIDIA-based."

Clarke also said that each AI-optimized server sold will drive revenue for Dell Technologies' other products. That halo effect hasn't played out just yet though. 

"We think there's a large amount of storage that sits around these things. These models that are being trained require lots of data. That data has got to be stored and fed into the GPU at a high bandwidth, which ties in network. The opportunity around unstructured data is immense here, and we think that opportunity continues to exist. We think the opportunity around NICs and switches and building out the fabric to connect individual GPUs to one another to take each node, racks of racks across the data center to connect it, that high bandwidth fabric is absolutely there and needed. We think the opportunity to extend in doing deployment of the rack itself is an opportunity, installing whether that's cables, heat exchangers, rear door heat exchangers, cooling units, power units, et cetera, the cabling. We think the deployment of this gear in the data center is a huge opportunity."

There are also a bevy of services Dell can sell to implement, manage and scale systems.

Data to Decisions Tech Optimization dell Big Data Chief Information Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer

Nvidia's 10Q filing sets off customer guessing game

Nvidia's 10Q filing sets off customer guessing game

Nvidia filed its first quarter 10-Q and set off the customer guessing game.

Nvidia counts two types of customers. A direct customer is an original equipment manufacturer, system integrator, original device manufacturer and distributors. The other type of customer is indirect and buy through direct customers. Indirect customers are public cloud providers, consumer internet companies, enterprises, public sector and startups.

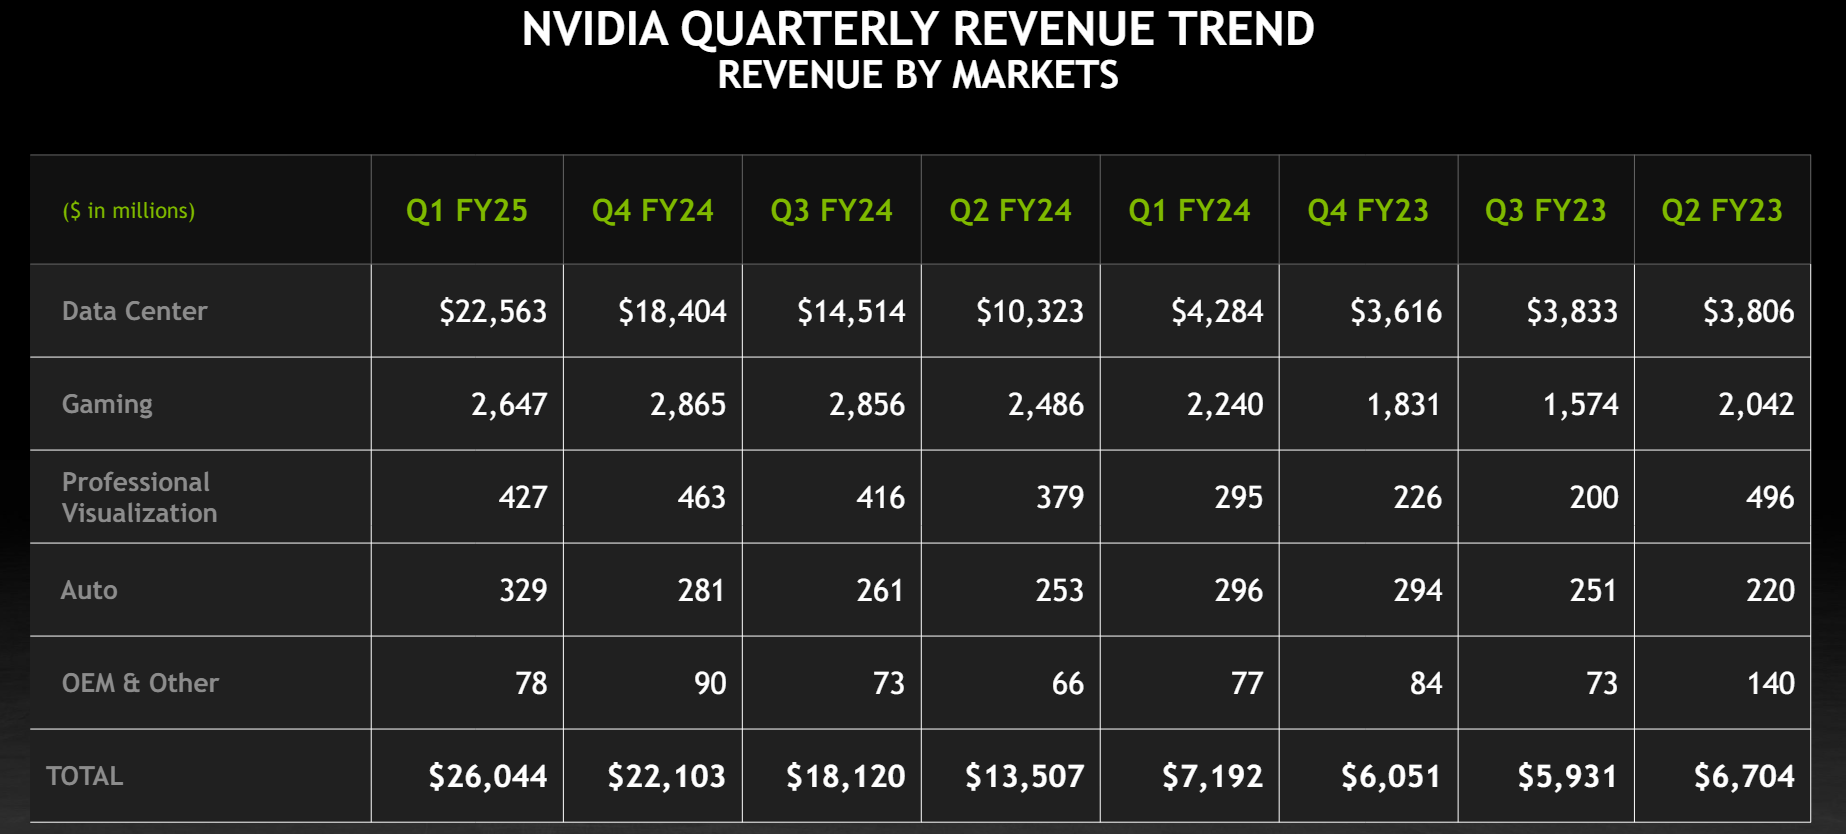
In the filing, Nvidia said one direct customer was 13% of revenue in the first quarter and another direct customer was 11% of sales. If I'm going to guess, I'm thinking Dell Technologies and Supermicro are in the running with perhaps HPE in the mix somewhere. It's obvious that Nvidia and Dell are tight partners.

Two indirect customers were 10% or more of total first quarter revenue each. This cohort could be a bevy of players, but my two favorite guesses would be Microsoft and Facebook. Other big indirect customers could include AWS, CoreWeave, which has raised billions of dollars in funding, and maybe Google or Oracle.

Nvidia also noted that one of the two indirect customers bought through the second direct customer that was 11% of sales.

The company's first quarter revenue was $26 billion

Data to Decisions Tech Optimization nvidia Chief Information Officer

Nutanix winning deals vs. VMware, but Broadcom punching back with pricing

Nutanix winning deals vs. VMware, but Broadcom punching back with pricing

Nutanix is learning that larger deals--including the wins from Broadcom's VMware--take longer to nail down and implement due to CXO approvals and Broadcom discounting when business is at stake. Nevertheless, Nutanix appears to have the tools required to win in the trenches vs. VMware.

The company's third quarter financial results and comments from Nutanix CEO Rajiv Ramaswami didn't often address VMware. But it's clear VMware was the elephant in the room. Ramaswami noted that Nutanix won an eight-figure deal with a North American Fortune 50 financial services company. It also won a North American Fortune 500 consumer packaged goods company.

Nutanix product additions, partnerships designed to capitalize on VMware customer angst | What VMware customers are doing through the lens of Nutanix

Ramaswami said:

"This customer, whose data center footprint has historically been split between Nutanix and a competitor was looking to standardize their automation and self-service capabilities on a single platform.

Going forward, this customer plans on swapping out the competitive software in their existing footprint and also utilizing Nutanix cloud platform for all of their expansion needs. We see these wins as a testament to our ability to both land significantly and expand within the largest companies. And we are encouraged by the substantial increase in the number of customers and partners engaging with us, including some of the world's largest companies.

However, these larger opportunities tend to have longer sales cycles, can involve aggressive competitive responses and exhibit great availability with respect to timing and outcome."

Translation: Nutanix is winning VMware customers, but don't expect the wins to be quick or easy. 

Nutanix reported a fiscal third quarter net loss of $15.6 million, or 6 cents a share, on revenue of $524.6 million, up 17% from a year ago. Non-GAAP earnings were 28 cents a share. Wall Street was looking for third quarter earnings of 17 cents a share.

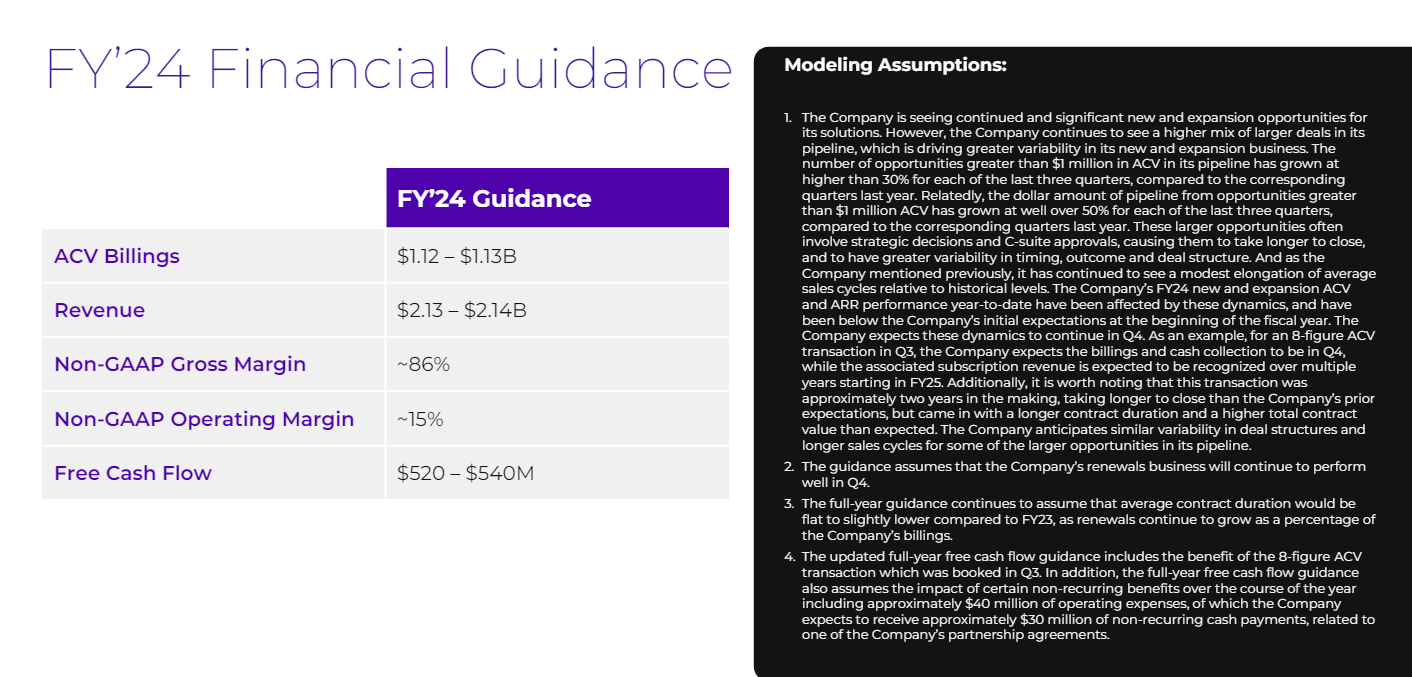
As for the outlook, Nutanix projected fourth-quarter revenue of $540 million to $540 million. For the fourth quarter, analysts were modeling earnings of 16 cents a share on revenue of $548.12 million. For the fiscal year, Nutanix projected revenue of $2.13 billion to $2.14 billion.

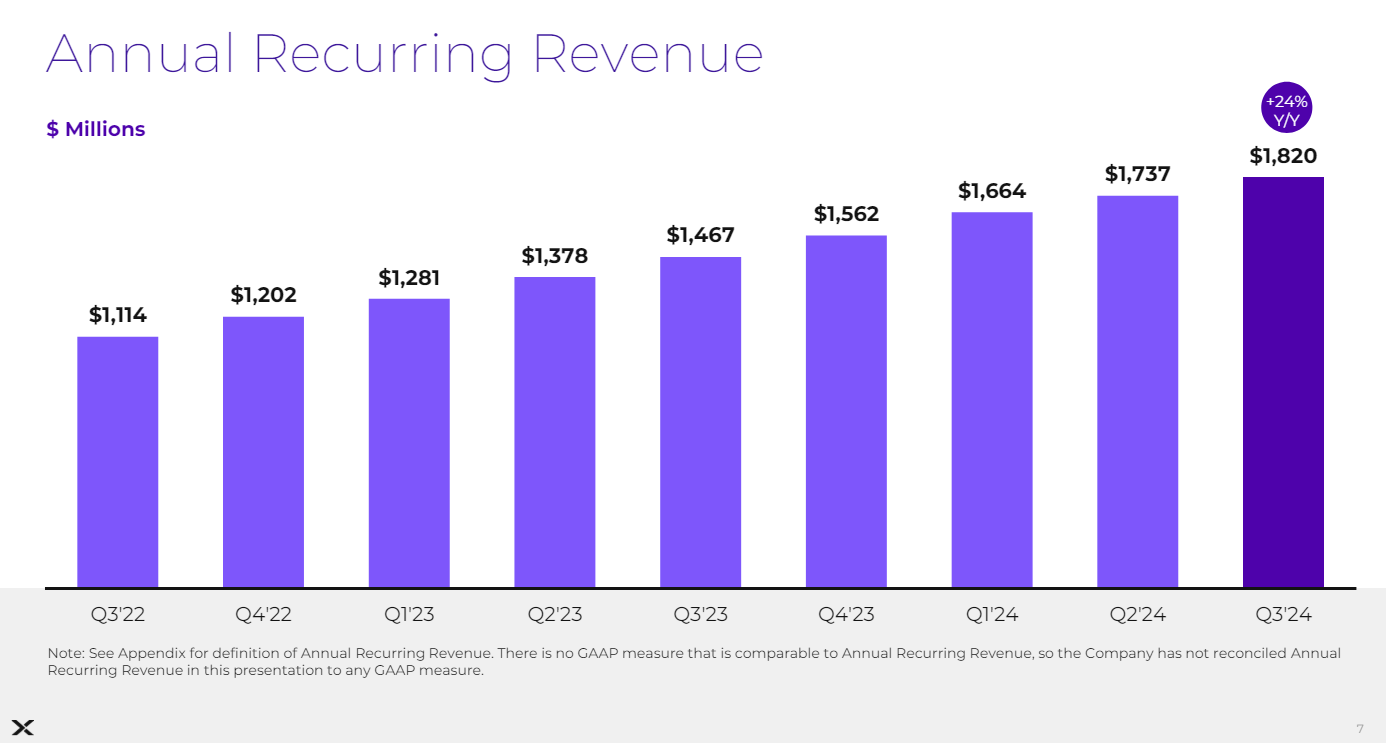
Nutanix said its annual recurring revenue (ARR) in the third quarter was $1.82 billion, up 24% from a year ago.

The results come a week after Nutanix launched a series of products to make it easier for enterprises to adopt generative AI. The most notable announcement from Nutanix .NEXT was a partnership with Dell Technologies. Nutanix will be sold via Dell Technologies hyper-converged systems later this year. Nutanix already has a big partnership with Cisco.

The battle

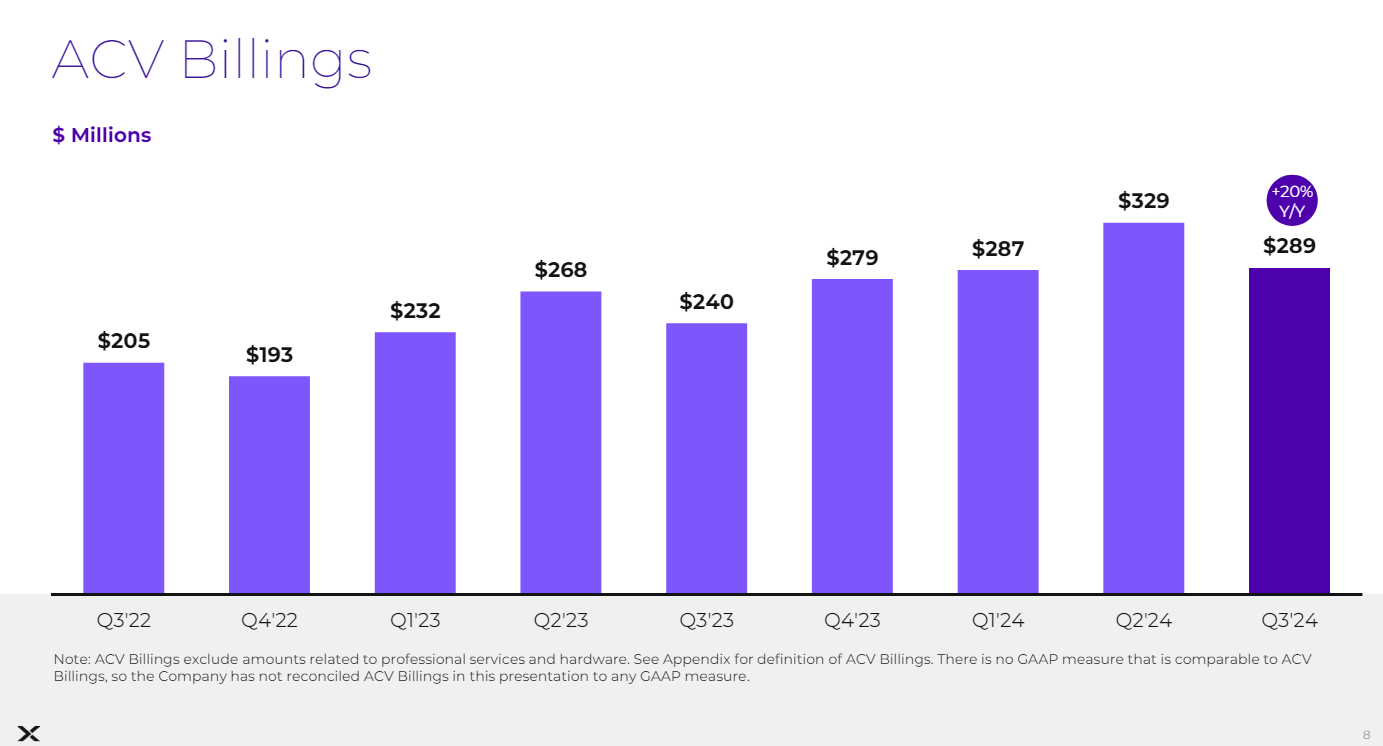
Nutanix CFO Rukmini Sivaraman said the company continues to see "continued and significant new and expansion opportunities" as well as opportunities greater than $1 million in ACV.

The problem? "These larger opportunities often involve strategic decisions and C-suite approvals, causing them to take longer to close and to have greater variability in timing, outcome and deal structure," said Sivaraman. "And as we mentioned previously, we have continued to see a modest elongation of average sales cycles relative to historical levels."

For instance, that eight-figure deal landed in the quarter will have billings and cash collection in the fourth quarter with subscription revenue recognized in fiscal 2025 and beyond. That deal also took two years to land. 

Ramaswami said Nutanix has deals that take longer to close, but interest from enterprises and partners is surging. Nutanix is now more strategic as a vendor.

The battle with VMware will take a while. Ramaswami noted that VMware customers have signed multiple year deals before the Broadcom purchase. The installed base also requires a hardware refresh. And VMware will cut prices to keep customers.

Ramaswami noted:

"We've seen Broadcom display a lot of flexibility with respect to their pricing, they are packaging changes, especially when they are faced with the probability of losing some of their larger customers are responding to push back from the market and from the customer base."

The short version: Broadcom has raised VMware's prices in many respects, but will discount heavily if large customers are at risk.

"The situation with respect to what Broadcom is doing is also evolving rapidly. They've tried a bunch of things. They're stepping back on some of the things that they've tried. Of course, for the competitive situation, this is quite dynamic on that front."

The timeline since Broadcom closed its VMware purchase features a good bit of turmoil.

My take

This Nutanix vs. VMware battle will go on for years for all of the reasons stated above. The other reality is that migrations take years. If you want a crystal ball into how this will play out for VMware it's worth looking at an example of Broadcom's purchase of CA. CA is a smaller mainframe software provider, but the Broadcom playbook is roughly the same.

I caught up with a CIO this week to chat about a migration away from mainframes. Initially, I thought the migration would be about better access to data, modernization and prepping for generative AI applications. But the migration was really driven by Broadcom’s CA unit squeezing more revenue out of this large enterprise.

In negotiations with CA, it became clear that costs were going to go higher to manage legacy infrastructure. Costs were going to go high enough that it made sense to leave mainframes entirely because there are only so many options to choose from (CA, BMC, IBM).

Sound familiar VMware customers? Today, enterprise buyers are noticing the Broadcom software playbook because VMware is more visible. Turns out all we had to do was look at CA’s approach post Broadcom acquisition to know what would happen.

VMware customers are seeing more options as they evaluate their next moves, but these migrations take time. Rimini Street said it will offer support to VMware customers and Nutanix launched a series of updates that add up to poaching VMware customers.

Tech Optimization Data to Decisions Future of Work Innovation & Product-led Growth New C-Suite vmware ML Machine Learning LLMs Agentic AI Generative AI Robotics AI Analytics Automation B2B B2C CX EX Employee Experience HR HCM business Marketing Metaverse developer SaaS PaaS IaaS Supply Chain Quantum Computing Growth Cloud Digital Transformation Disruptive Technology eCommerce Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP Leadership finance Social Healthcare VR CCaaS UCaaS Customer Service Content Management Collaboration M&A Enterprise Service Chief Information Officer Chief Executive Officer Chief Technology Officer Chief Data Officer Chief Digital Officer Chief Analytics Officer Chief Financial Officer Chief Operating Officer Chief Marketing Officer Chief Revenue Officer

Salesforce's Q2 outlook disappoints, Q1 mixed

Salesforce's Q2 outlook disappoints, Q1 mixed

Salesforce’s second quarter outlook missed expectations, but the company said it is still early innings for generative AI demand. Nevertheless, Salesforce is projecting single-digit growth for the quarter ahead.

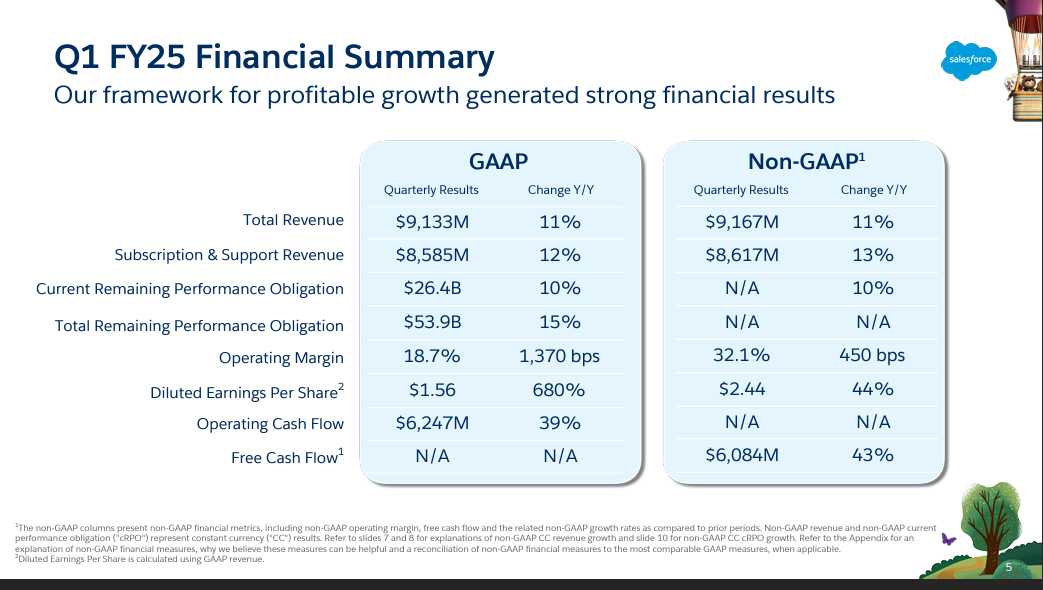
The company projected second quarter revenue of $9.2 billion to $9.25 billion, up 7% to 8%, with non-GAAP earnings of $2.34 a share to $2.36 a share. Wall Street was expecting earnings of $2.40 a share on revenue of $9.35 billion.

For fiscal 2025, Salesforce said sales will be between $37.7 billion and $38 billion, lower than the $38.05 billion estimate. The company said non-GAAP earnings for the year will be $9.86 a share to $9.94 a share, above the $9.80 s share.

Salesforce launches Einstein 1 Studio, Data Cloud enhancements | Salesforce Reinvents Itself Again With Einstein 1

That outlook followed a mixed first quarter. Salesforce reported non-GAAP earnings of $2.44 a share on revenue of $9.13 billion. GAAP earnings in the first quarter were $1.56 a share. Wall Street was expecting Salesforce to report first quarter earnings of $2.37 a share on revenue of $9.15 billion.

CEO Marc Benioff said the company is “at the beginning of a massive opportunity for our customers to connect with their customers in a whole new way with AI.” The company’s remaining performance obligations in the first quarter were $52.9 billion, up 15% from a year ago.

Amy Weaver, CFO of Salesforce, said the company was disciplined with expenses and its capital return program.

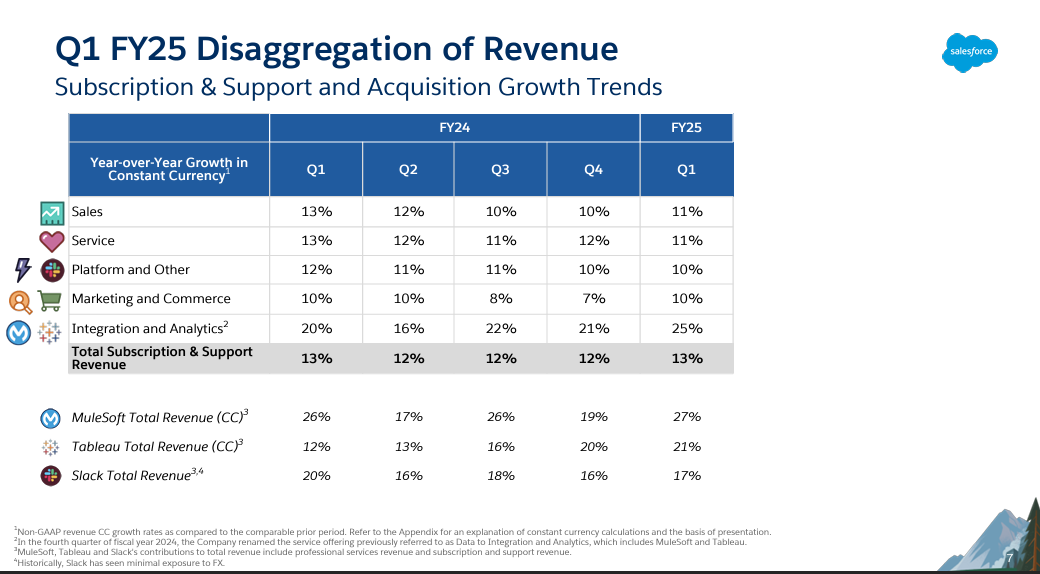
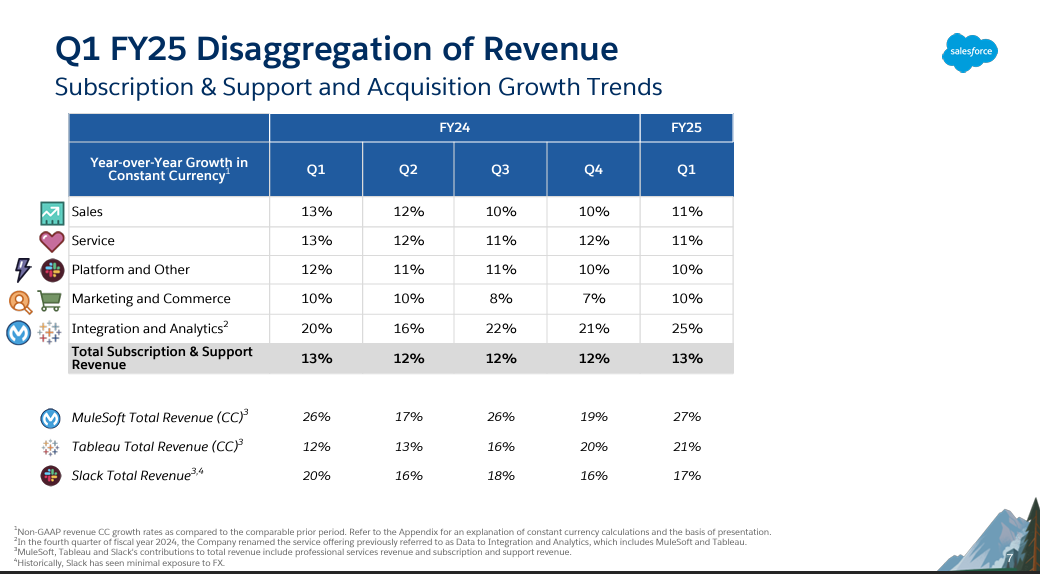
By cloud, Salesforce’s Sales Cloud revenue was up 11% in the first quarter as was Service Cloud. Platform and other and Market and Commerce had revenue growth of 10% each. Integration and Analytics (Tableau and Mulesoft) saw revenue growth of 25%.

On a conference call with analysts, Benioff put a positive spin on the outlook and first quarter results. He said large language models (LLM) are becoming a commodity and the enterprise value will be customer data and metadata. He noted that Salesforce manages more than 250PB of customer data. 

Benioff said:

"Every company in the world across every industry is being transformed by AI in the next few years. And when you look at the power of AI, you realize the models and UI are not the critical success factors. There are 1,000s of these models, some open source and some closed source models. Most of these will not survive. They're just commodities now. They don't know anything about a company's customer relationships. Each day hundreds of petabytes of data are created that AI models can use for training and generating output. But the one thing that every enterprise needs to make AI work is their customer data, as well as the metadata that describes the data. Customer data and metadata are the new gold for these enterprises."

The Salesforce CEO, who seemed a bit wound up by the aftermarket reaction to the results, touted Data Cloud, the uptake of multiple clouds by customers and partnerships with Amazon, Databricks, Snowflake and other players. "Customers can access this live data from anywhere in data cloud without copying or moving it. It's the engine of our future growth and this is the engine of our future artificial intelligence growth as well," said Benioff. 

Brian Millham, Salesforce's operating chief, said the company did see longer sales cycles. He said:

"We continue to see the measured buying behaviors similar to what we experienced over the past two years and with the exception of q4, where we saw stronger bookings, the momentum we thought q4 moderated in q1 and we saw elongated deal cycles do compression and high levels of budget scrutiny. In Q1 as part of our ongoing transformation, we made some intentional changes in our go to market organization to drive long term productivity and create better customer experiences."

Executives asked about whether genAI was taking budget from other software platforms. Benioff said genAI will drive software growth in the future, but many customers were focusing on data. Millham followed up:

"GenAI benefit will come from the front office and we're really feeling that right now. I do think customers are getting their data estate in order as a precursor to leveraging AI capabilities. We're seeing that with the growth of Data Cloud right now. I think it's actually a step process for many of our customers."

Benioff was also asked about acquisitions amid the Informatica rumors. He said:

"We will continue to look at products inorganically. But as we've committed to you, if we're looking at a large scale acquisition, we're going to make sure that it is not dilutive and has the right metrics. And we're also going to be quick to walk away from things that we are not totally confident in."

But yes, Salesforce will go shopping if it fits into its framework. 

Marketing Transformation Matrix Commerce salesforce Chief Information Officer