Results

Oracle CEO Mark Hurd's OpenWorld Keynote: Highlights and Analysis

Oracle CEO Mark Hurd's OpenWorld Keynote: Highlights and Analysis

Oracle CEO Mark Hurd’s OpenWorld keynote on Monday featured the expected heavy sales pitches and claims of Oracle’s leadership in the cloud, but also provided some bold predictions and interesting perspectives from large customers. Here’s a look at some of the highlights.
 

The 2025 Vision

Hurd listed five things Oracle believes will be true by 2025: 

1. Eighty percent of production apps will be in deployed in the cloud.

2. Two suite providers will own 80 percent of the SaaS market. Only 20 percent of the SaaS market will be held by point providers.

3. All new testing and development will be done in the cloud. Today, 30 to 40 percent of IT spending is on these areas, making them attractive cloud targets thanks to cost savings, according to Hurd.

4. By 2025, virtually all enterprise data will be stored in clouds. The rationales: Better economics, easier access and real-time availability, Hurd said.

5. To that end, enterprise clouds will be the most secure environments in the world. Oracle’s is more secure than anyone, he claimed.

POV: Hurd’s prediction regarding dev and test is the easiest one to agree with, since that segment is fairly mature already with options from many vendors, large and small.

As for a SaaS market dominated by two suite companies, such a scenario probably depends on a lot of consolidation between now and 2025. One key factor for customers would be how well each vendor integrates and harmonizes the pieces into their suites. 

Finally, Hurd didn’t spend a lot of time on the data and security predictions, but both topics will be up for deeper discussion on Tuesday during CTO Larry Ellison’s second OpenWorld keynote. 

General Electric's Journey to the Cloud

Hurd’s keynote featured discussions with high-profile customers, including General Electric CIO Jim Fowler. GE is undergoing a far-reaching move to the cloud as part of a transition into digital lines of business.

Fowler provided a succinct and telling example of the cloud’s multiple benefits. One GE division moved a configurator application off-premises to the cloud and in doing so, the cost to run it went from $65,000 to $6,000. But the real benefits were global scale and the resulting ability to push more orders and quotes through the system, he said.

GE is taking a deliberate approach to what it buys in the cloud, which includes Oracle’s Taleo recruitment software, according to Fowler. “I want to buy things that don’t differentiate me in the market,” he says. It makes more sense to buy those products from specialists like Oracle, and use in-house talent to build out unique IP, Fowler said.

POV: Just a few weeks ago, Fowler appeared at Amazon Web Services’ re:Invent conference and declared the company “all in” with AWS as part of a far-reaching digital transformation. 

GE is planning to move 9,000 application workloads to AWS over the next few years, reducing its data center footprint from 34 to four. 

This subject unsurprisingly didn’t come up during Hurd’s discussion with Fowler. Oracle is touting its ability to offer customers the cloud at all three levels—IaaS, PaaS and SaaS—but it’s got some catching up to do, particularly in the first category. The good news for customers considering both options is that Ellison has publicly stated Oracle will compete aggressively with Amazon on IaaS pricing. 

CONSTELLATION INSIGHTS 
Constellation Insights provides members with daily analysis of breaking news across the enterprise. Insights will be available in November 2015. Learn more about Constellation Insights. 

Data to Decisions Future of Work Tech Optimization Chief Executive Officer Chief Financial Officer Chief People Officer Chief Information Officer

Oracle OpenWorld: 3 Takeaways from Day 1 Keynote

Oracle OpenWorld: 3 Takeaways from Day 1 Keynote

We have the opportunity to attend Oracle OpenWorld in San Francisco, happening this week. 
 
 
So take a peek:
 
 
If you can't watch here are the Top 3 Takeaways:
 
 
Here is why they matter:
 
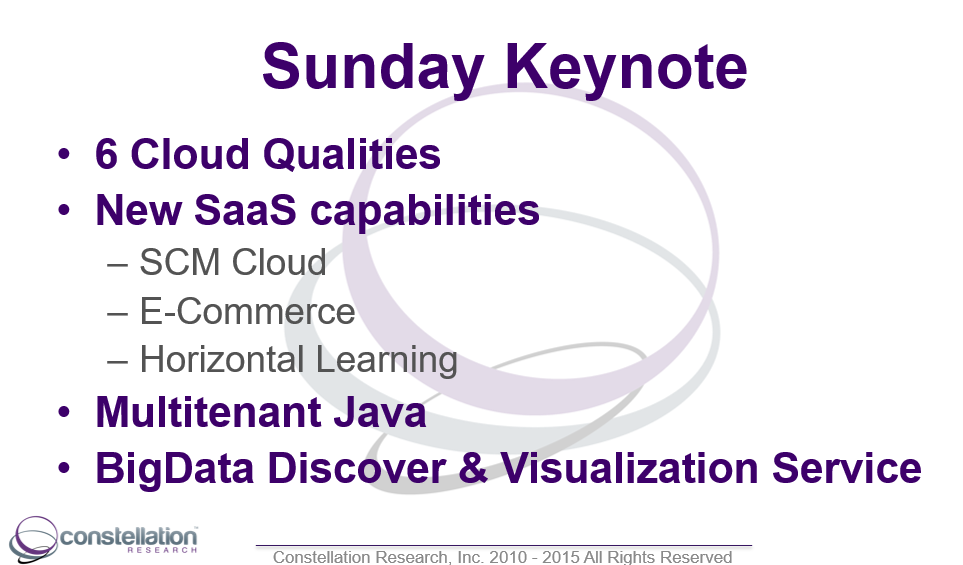
  • 6 Cloud Qualities - It is good to see Oracle define which qualities it applies to its cloud offerings - no surprises there - usual Oracle qualities - but good and key for customers to know what they are and to be able to measure future offerings with it.
  • New SaaS Capabilities - Good to see Oracle plugging the largest gap in the Cloud based suite with SCM. E-Commerce is a similar gap to address on the CRM side. The new HCM Learning, announced in spring 2015 becoming a cross suite capability is good move and to my knowledge a first in enterprise software. A great testament of how important Learning is in the 21st century.
  • Multitenant Java - Built on top of WebLogic - a key capability to scale Java better in both design and runtime, expect very good uptake, assuming it works.
  • BigData Discovery & Visualization Service - An area where Oracle has been traditionally weaker, good for Oracle customers and prospects to see Oracle add capabilities, very important in the overall race for the business user, with software providing much of the intelligence that is needed for completing these new tasks.

MyPOV

A good start for Oracle OpenWorld, with many more things to come, this was likely merely the appetizer. Too early to tell how well the overall integrated Oracle offering performs, we will keep watching.  


Don't miss my overall OpenWorld preview here:
 
 
And here is the Storify I used for the video:


More on Oracle:
 
  • Event Preview - Oracle Openworld - watch here


Future of Work / HCM / SaaS research:
  • Event Report - Oracle HCM World - Full Steam ahead, a Learning surprise and potential growth challenges - read here
  • First Take - Oracle HCM World Day #1 Keynote - off to a good start - read here
  • Progress Report - Oracle HCM gathers momentum - now it needs to build on that - read here
  • Oracle pushes modern HR - there is more than technology - read here. (Takeaways from the recent HCMWorld conference).
  • Why Applications Unlimited is good a good strategy for Oracle customers and Oracle - read here.

Also worth a look for the full picture
  • Event Report - Oracle PaaS Event - 6 PaaS Services become available, many more announced - read here
  • Progress Report - Oracle Cloud makes progress - but key work remains in the cellar - read here
  • News Analysis - Oracle discovers the power of the two socket server - or: A pivot that wasn't one - TCO still rules - read here
  • Market Move - Oracle buys Datalogix - moves more into DaaS - read here
  • Event Report - Oracle Openworld - Oracle's vision and remaining work become clear - they are both big - read here
  • Constellation Research Video Takeaways of Oracle Openworld 2014 - watch here
  • Is it all coming together for Oracle in 2014? Read here
  • From the fences - Oracle AR Meeting takeaways - read here (this was the last analyst meeting in spring 2013)
  • Takeaways from Oracle CloudWorld LA - read here (this was one of the first cloud world events overall, in January 2013)

And if you want to read more of my findings on Oracle technology - I suggest:
  • Progress Report - Good cloud progress at Oracle and a two step program - read here.
  • Oracle integrates products to create its Foundation for Cloud Applications - read here.
  • Java grows up to the enterprise - read here.
  • 1st take - Oracle in memory option for its database - very organic - read here.
  • Oracle 12c makes the database elastic - read here.
  • How the cloud can make the unlikeliest bedfellows - read here.
  • Act I - Oracle and Microsoft partner for the cloud - read here.
  • Act II - The cloud changes everything - Oracle and Salesforce.com - read here.
  • Act III - The cloud changes everything - Oracle and Netsuite with a touch of Deloitte - read here

Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my YouTube channel here
Tech Optimization Matrix Commerce Marketing Transformation Revenue & Growth Effectiveness Next-Generation Customer Experience Openworld Oracle Supply Chain Automation Cloud Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software IoT Blockchain ERP Leadership Collaboration M&A Chief Information Officer Chief Supply Chain Officer Chief Experience Officer

Oracle Softens Tone In Ongoing Hardware War with IBM

Oracle Softens Tone In Ongoing Hardware War with IBM

If Oracle and its executive chairman Larry Ellison have a favorite competitive target, it's IBM. The latest broadside—delivered in conjunction with Intel—is aimed at luring customers running Oracle database workloads on IBM Power7-based systems to Oracle's Exadata platform, which uses Intel Xeon processors.

From the release issued Sunday at Oracle OpenWorld:

The Exa Your Power program is a free database migration Proof of Concept (PoC) for qualified customers. Oracle will assess the customer’s environment, deliver a customized database migration results report, and show how they may be able to significantly reduce the time and cost required to run critical database workloads.

“CSC has successfully migrated dozens of customers’ enterprise workloads to Oracle Engineered Systems as a part of our Digital Transformation Services. We recently migrated an Oracle Database for a major insurance provider from IBM Power 7 to an Exadata X5 engineered system as a Proof of Concept,” said Ashish Mahadwar, Executive Vice President & General Manager, Emerging Business Group. “Our test results showed their Siebel Application running four-to-ten times faster and their ETL Processes running up to 12-times faster on the Exadata. The customer was very impressed by the scale of the benefits and the ease of migration and is now working with CSC on a major Exadata deployment.”

Oracle and Intel are jointly backing the migration effort. 

Thousands of customers are now running Oracle databases on "large and costly" IBM machines, CEO Mark Hurd said during a keynote at OpenWorld on Sunday. "We think you can do better."

While the program was just announced, it's been going on in some form for a while. Oracle and Intel have already partnered to move more than 1,000 customers from Power7 systems to Exadata, according to a slide Hurd displayed during his talk. One named example was homebuilder Pulte Group, which saw financial application performance improve by a factor of 15, according to Oracle.

"It's sort of on us, Intel and Oracle, to give customers an easy way to see just what the two of us can do together to make life a whole lot better," Hurd said. "We can take some of these workloads and go 10 times, 15 times faster than the legacy system."

The Bottom Line

There's quite a bit to unpack here. First of all, the tone of the sales pitch is much milder than ones Oracle has made in the past against IBM over Exadata. In 2012, Oracle yanked newspaper ads that the National Advertising Board concluded had overreached in their Exadata performance claims over Power Systems.

Hurd carefully refrained from making overly broad claims in his keynote remarks, underscored by the reference to improvements for "some" but not all workloads. 

In addition, there's the matter of making fair, apples-to-apples comparisons. Oracle's press release provides the example of a customer moving from a Power7-based system to an Exadata X5, which is the newest model. But the Power7 architecture dates to 2010 and was succeeded by Power8 last year. 

Constellation Research VP and principal analyst Holger Mueller has a measured perspective on the announcement.

"'Engineered systems' such as Exadata are an area of competition right now, and vendors are trying to trump older architectures or form strong combinations," Mueller says. "Here we see that IBM used to implement a lot of Siebel turnkey systems on Power, and Oracle-Intel now want to go for a larger footprint with these customers. But databases remain sticky and the servers they run on are closely connected to that stickiness. Look at the perennial attempts of SAP to move its customers off Oracle, to very little success."

CONSTELLATION INSIGHTS 
Constellation Insights provides members with daily analysis of breaking news across the enterprise. Insights will be available in November 2015. Learn more about Constellation Insights. 
 

Tech Optimization Chief Information Officer

Event Preview - Oracle Openworld

Event Preview - Oracle Openworld

Before making it to Oracle OpenWorld it is time to sort out some thoughts on where Oracle stands overall, where the event will likely take the vendor and what prospects and customers should look into.


So take a peek:


If you didn't have a chance to watch here are the key points
 
  • Oracle is in the process of building a massive integrated technology stack - from 'chip to click' - so from the silicon to SaaS. I will be key to check on progress, quality and attractiveness for enterprises.
  • Last year the focus was on PaaS, what will it be this year? Expect more SaaS, PaaS and likely more IaaS, which is overdue. Oracle was also one of the first vendors talking DaaS (Data as a Sevice) so will be key to check in on that, too.
  • For customers the key thing to watch is if the synergies of the integrated stack work for them. Customers should explore both horizontal and vertical direction for further pieces of the Oracle integration stack. First step needs to be on the validation of the synergies, are they there directionally there, are they there in product, are they there as ROI and customer references.
It will be a wild ride - when you see me, step by to say Hi! - I always love a short chat and catch-up.

 
---------------------

More on Oracle:

Future of Work / HCM / SaaS research:
  • Event Report - Oracle HCM World - Full Steam ahead, a Learning surprise and potential growth challenges - read here
  • First Take - Oracle HCM World Day #1 Keynote - off to a good start - read here
  • Progress Report - Oracle HCM gathers momentum - now it needs to build on that - read here
  • Oracle pushes modern HR - there is more than technology - read here. (Takeaways from the recent HCMWorld conference).
  • Why Applications Unlimited is good a good strategy for Oracle customers and Oracle - read here.

Also worth a look for the full picture
  • Event Report - Oracle PaaS Event - 6 PaaS Services become available, many more announced - read here
  • Progress Report - Oracle Cloud makes progress - but key work remains in the cellar - read here
  • News Analysis - Oracle discovers the power of the two socket server - or: A pivot that wasn't one - TCO still rules - read here
  • Market Move - Oracle buys Datalogix - moves more into DaaS - read here
  • Event Report - Oracle Openworld - Oracle's vision and remaining work become clear - they are both big - read here
  • Constellation Research Video Takeaways of Oracle Openworld 2014 - watch here
  • Is it all coming together for Oracle in 2014? Read here
  • From the fences - Oracle AR Meeting takeaways - read here (this was the last analyst meeting in spring 2013)
  • Takeaways from Oracle CloudWorld LA - read here (this was one of the first cloud world events overall, in January 2013)

And if you want to read more of my findings on Oracle technology - I suggest:
  • Progress Report - Good cloud progress at Oracle and a two step program - read here.
  • Oracle integrates products to create its Foundation for Cloud Applications - read here.
  • Java grows up to the enterprise - read here.
  • 1st take - Oracle in memory option for its database - very organic - read here.
  • Oracle 12c makes the database elastic - read here.
  • How the cloud can make the unlikeliest bedfellows - read here.
  • Act I - Oracle and Microsoft partner for the cloud - read here.
  • Act II - The cloud changes everything - Oracle and Salesforce.com - read here.
  • Act III - The cloud changes everything - Oracle and Netsuite with a touch of Deloitte - read here

Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my YouTube channel here
Tech Optimization Future of Work Innovation & Product-led Growth Next-Generation Customer Experience New C-Suite Data to Decisions Openworld Oracle SaaS PaaS IaaS Cloud Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP CCaaS UCaaS Collaboration Enterprise Service Chief Information Officer Chief Technology Officer Chief Digital Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Executive Officer Chief Operating Officer

Webinar: Avoiding Cloud Vendor Lock-In

Webinar: Avoiding Cloud Vendor Lock-In

Customers Must Hurry To Address The Mistakes From Shadow IT SaaS/Cloud Adoption

@rwang0 #CRChat #webinar vendor lockin

Amidst the hey day of the early years for software as a service (SaaS) and Cloud, many line of business executives signed simple month to month, user based contracts without the burdens of IT and scrutiny of vendor procurement.  These edge applications and best of breed point solutions gave the business side massive flexibility in accessing innovation and moving the business forward as IT teams struggled with stabilizing existing landscapes and identifying a strategy to repay technical debt.

Fast forward to 2015, many organizations face challenges unlike the early years of cloud for a few reasons:

  1. Best of breed point solutions have evolved to cloud suites. From simple collaboration apps to sales force automation to talent management, successful SaaS vendors have evolved into cloud suites.  The complexity of offerings have introduced mission critical functionality on the cloud that require a more deliberate approach to cloud contracts
  2. Average contract has substantially increased in length.  Remember when your SaaS vendor contract was month-to-month with a one year contract being on the long side?  Recent contracts with some HR Tech vendors have averaged from three to five years, with even seven starting to emerge as part of the standard contract.  Longer term commitments impact an organization’s agility which is why contract strategy should be coordinated with overall business strategy.
  3. Pricing models shift from simple to increasingly complex.  SaaS vendors started out with simple per user, per month pricing (i.e. PUPM).  Today, models have increased in complexity beyond user based pricing.  Usage based pricing is based on employees, revenue, gigabytes consumed, connections, or other business metrics.
  4. Integration remains a complex issue.  Early SaaS integrations were simple.  Customers could leverage point-to-point tools.  With Cloud becoming mainstream, the need to master data sources, address different granularities of process, harmonize workflows, and orchestrate API’s increase complexity of ownership.
  5. Pace of innovation begins to plateau.  Many early SaaS startups proudly announced monthly and quarterly updates with substantial improvements in functionality.  Many vendors have now moved from quarterly updates to three a year and even two at some.  Customers will want to understand the impact on road map and adoption.

The Bottom Line: Buyers Face Massive Vendor Lock-In

Cloud apps have dominated new license sales in the enterprise applications market in recent years. Constellation estimates that 93 percent of all new enterprise software license sales offer a cloud deployment option.  In the cloud model, buyers do not own the software license. Instead, the software is leased and accessed, while the purchaser owns the data. As the market shifts from on-premises to cloud deployment, the risk of getting locked into a vendor increases for three main reasons:

  1. The access model means users have limited rights and control. Cutting through the hype, buyers do not own the rights to the code in most public cloud models. Buyers pay for the right to access functionality and use the intellectual property, but at the full mercy of the cloud vendor. Should the vendor decide to take a different product direction or find itself bankrupt, users remain at the vendor’s mercy.
  2. Costs of switching vendors remain ambiguous at best and expensive at worst. While users have access to and ownership of their data, the hurdle in moving from one cloud vendor to another increases with usage over time. Without rights over the app’s functionality, users face lock-in if they cannot easily export their business processes that are instantiated in the vendor’s functionality. Add in different architectural standards, varying granularity of process flows and complex metadata models, and users face an expensive and daunting challenge switching from one cloud vendor to another. Most migration plans are unclear on how to successfully switch from one vendor to another.
  3. Vendors currently eager for business may grow fat and lazy in the future. The rush to earn a customer’s business remains intense. Most cloud vendors have customer-friendly policies. However, the risk of vendor complacency grows with each percentage point shift from on-premises to cloud deployments. Unless rights are stated up front today, buyers will lose leverage over time.

Recommendations: Take Steps From The Original Cloud Bill Of Rights To Protect Your Cloud Investment

Customers should leverage the software ownership life cycle to plan cloud contracts.  The five phases include:

Screen Shot 2015-10-25 at 11.05.40 AM

  1. Customer experience describes the client expectations of the vendor in the relationship.
  2. Selection describes the rights prospects and clients should expect from software vendors as they make their decision on a product and vendor.
  3. Deployment describes the rights clients should expect from vendors as they implement and consume the technology.
  4. Adoption describes the rights clients should expect from software vendors as they use the solution across the customer organization.
  5. Usage optimization describes the rights customers should expect from software vendors as they change how they expand, maintain or contract in their usage of the solution.
  6. Renewal describes the rights clients should expect from software vendors as they shift their usage requirements and change how they adopt SaaS solutions.

Use the Customer Bill of Rights in all contract negotiations.  Make sure you protect yourself from the life cycle of technology engagement.

How to Secure the Best Cloud Software Contract with R “Ray” Wang

Webcast November 10, 2015 11:00am PT/ 2:00pm ET

Get ready to learn the secrets of avoiding Cloud Vendor lock-in with this free introductory webinar brought to you by the Constellation Executive Network.

Join Constellation Research principal analyst and bestselling author R “Ray” Wang as he shares how to structure the most favorable cloud software contract for your organization. R “Ray” Wang will share his top cloud negotiation tips derived from his involvement in 1,000+ cloud contract negotiations. The increasing complexity of cloud services contracts means you can not afford to miss this webinar.

You will learn:

  • Top cloud negotiation tips from one of enterprise tech’s leading analyst
  • Common contract negotiation pitfalls
  • How to ensure you secure the best cloud services deal and avoid vendor lock-in.

For more customized approaches, feel free to reach out to any member of the Constellation team.

Get All 10 Lessons Learned From Disrupting Digital Business

Here’s everything you need to know from the best selling book – “Disrupting Digital Business” published by Harvard Business Review Press:

Lesson 1 – Transform Business Models And Engagement

Lesson 2 – Keep The Brand Promise

Lesson 3 – Sell The Smallest Unit You Can

Lesson 4 – Know That Data Is The Foundation Of Digital Business

Lesson 5 – Build For Insight Streams

Lesson 6 – Win With Network Economies

Lesson 7 – Humanize Digital With Digital Artisans

Lesson 8 – Democratize Distribution With P2P Networks

Lesson 9 – Deliver Intention Driven, Mass Personalization At Scale

Lesson 10 – Segment by Digital Proficiency Not Age

In fact, the impact is significant and now quantifiable with 52% of the Fortune 500 gone since 2000 and the average age of the S&P 500 company in 1960 is down from 60 years to a little more than 12 projected in 2020.  That is a 500% compression that has changed the market landscape forever in almost every industry.

Your POV.

Are you tired of the arrogant public-IPO startup who’s broken your relationship?  Want to move back to a win-win?

Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org.

Please let us know if you need help with your Digital Business transformation efforts. Here’s how we can assist:

  • Developing your digital business strategy
  • Connecting with other pioneers
  • Sharing best practices
  • Vendor selection
  • Implementation partner selection
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Resources

Reprints

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales .

Disclosure

Although we work closely with many mega software vendors, we want you to trust us. For the full disclosure policy,stay tuned for the full client list on the Constellation Research website.

* Not responsible for any factual errors or omissions.  However, happy to correct any errors upon email receipt.

Copyright © 2001 -2015 R Wang and Insider Associates, LLC All rights reserved.
Contact the Sales team to purchase this report on a a la carte basis or join the Constellation Customer Experience

The post Monday’s Musings: Avoiding Cloud Vendor Lock-In appeared first on A Software Insider's Point of View.

Data to Decisions Digital Safety, Privacy & Cybersecurity Future of Work Marketing Transformation Matrix Commerce New C-Suite Next-Generation Customer Experience Tech Optimization Innovation & Product-led Growth Webinar AR Leadership SaaS PaaS IaaS Cloud Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP CCaaS UCaaS Collaboration Enterprise Service Chief Customer Officer Chief Digital Officer Chief Executive Officer Chief Financial Officer Chief Information Officer Chief Marketing Officer Chief People Officer Chief Procurement Officer Chief Supply Chain Officer Chief Experience Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer

The Hottest Cloud-based Marketing Startups of 2015

The Hottest Cloud-based Marketing Startups of 2015

1
  • What's Hot in CRM, 2012 Apttus, Booker, Lattice Engines, Segment and Tubular Labs are the five hottest cloud-based marketing startups of 2015.
  • 13 of the hottest 34 cloud-based marketing startups are from the Bay Area, followed by Los Angeles with 3, and Bangalore and New York, both with 2.
  • 14 are in Pre Series A, 7 in A-Stage, 5 in B-Stage and 3 in C-Stage funding rounds.

These and other insights are from a quick analysis completed today using Mattermark Pro, in response to reader requests for more research on marketing startups.

Mattermark uses a combination of artificial intelligence and data quality analysis to provide insights into over 1 million private companies, over 470,000 with employee data, and over 100,000 funding events. In the interest of full disclosure I’m not today and have never done any consulting work of any kind with Mattermark.

Finding The Hottest Cloud-based Marketing Startups

To find the hottest cloud-based marketing startups, an initial query requesting startups competing in the cloud computing and marketing industries was completed. Next, advanced query tools in Mattermark Pro were used to filter out all startups that had exited as indicated by their stage status in Mattermark’s data. This filtered out startups who had been acquired, completed an IPO or had exited through other means. The table below is the result of an analysis completed today with Mattermark data.  You can download the table here in Microsoft Excel format.

hottest cloud-based marketing startups

The Mattermark Growth Score shown in the table below and downloadable Excel file is a measure of how quickly a company is gaining traction at a given point in time. It incorporates the Mindshare Score (web traffic, social traction) as well as business growth metrics (e.g. employee count over time, funding). The underlying assumption is that companies who see growth across these signals are shipping product and talking to customers, and are more likely to continue to grow as a result. This score is not meant to provide guidance on which startup to invest in.  Rather it’s a measure of momentum across the metrics and KPIs that Mattermark measures.


Filed under: Analytics, Cloud Computing, Cloud Computing Forecasts 2011, Cloud startups, Louis Columbus' blog, SaaS, SaaS Forecasts Tagged: Apttus, Booker, Cloud Computing, Lattice Engines, Louis Columbus' blog, SaaS, SaaS ERP, Salesforce.com, Social Media Analytics, Software-as-a-Service

Marketing Transformation Chief Marketing Officer

#SAPtd Las Vegas 2015 Report- Analyics, HCP, and Fiori BUILD

#SAPtd Las Vegas 2015 Report- Analyics, HCP, and Fiori BUILD

We had the opportunity to attend SAPtd (aka TechEd / dCode) conference in Las Vegas this week. The event had similar attendance to least year, a vastly expanded (and improved) conference space, compared to a year before - though no SapphireNow style level (which is the best conference floor I have seen in the last 12 months).


So take a peek:


No chance to watch - read below (keep in mind this is not from an overall SAP announcement perspective, but for the audience, SAP developers). 
 
  • Fiori BUILD - SAP customers have been challenged by suboptimal user interfaces for the longest time. Fiori addresses this, as it turns out the price tag was not really the issue for customers, even now that Fiori is free, way too many SAP users are still working with not so great user interfaces. To make the work of designers more easy, the new Fiori BUILD tool makes it easier for a designer to even take screen layouts out to users and collect feedback on the mochup's usability. We will not see the majority of SAPtd attendees become UI designers, but they may as well use a tool to create applications with a better user interfaces.
     
  • HCP and VORA - We saw live usage of tax and translation services in HCP, and the usage of VORA, unfortunately not with any code (relevant for the audience).
     
  • Cloud for Analytics - SAP brings together all BI, GRC and newer assets into one product family. Core pillars are for now the Cloud for Planning product and the Digital Boardroom (built with the latter). More to come. 

    Analyst Tidbits

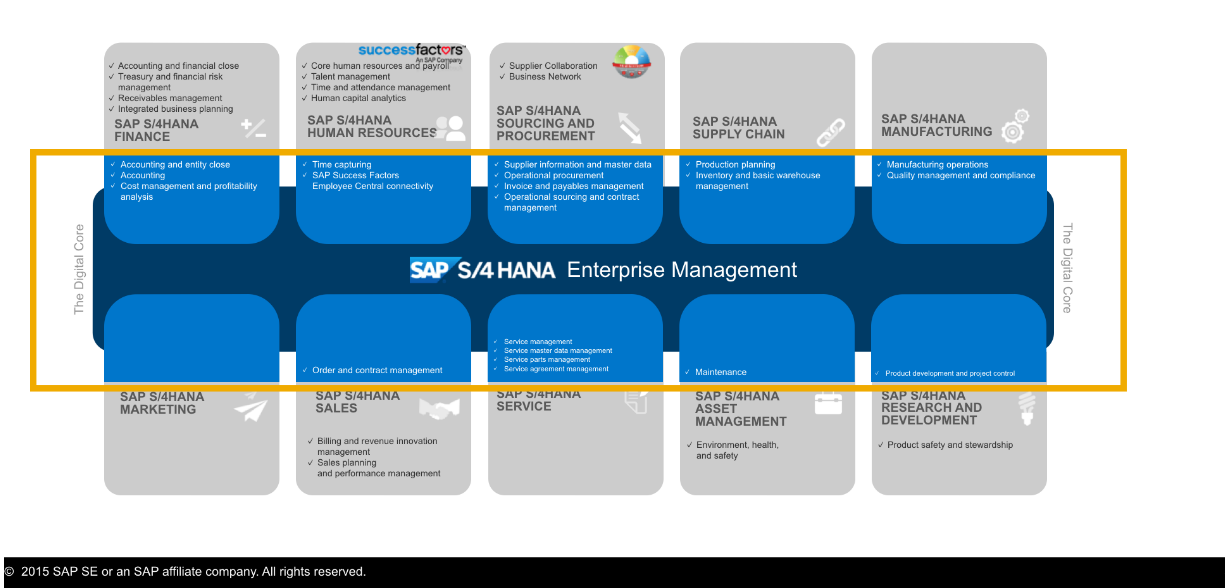
    • S4/HANA - The biggest news overall for me came in a briefing  meeting where SAP clarified the 'digital core' - more importantly how much substantial functionality will be available in November with 1511 release of S/4HANA release (first on premises, then in the cloud a few weeks later). It is substantial beyond the early S4/HANA scope of Finance. If it all materializes, SAP is showing greater speed in creating S4/HANA than I would have anticipated, so certainly the biggest surprise of the conference, good new for SAP customers. 
     
     
    • Co-Innovation - SAP is innovating internally and contributing back to the product, I had the chance to meet with CIO Helen Arnold, building a employee-sourced enabled ticketing system on top of HP is not every CIO's slice of bread, so good to see how HCP enables innovation. 
    • SAP Digital - Makes progress, but probably needs to be even more aggressive. A year ago SAP pointed to a marketplace for developers, that has not been yet implemented, not sure whose charter that is - but it vital for developer success.
     

    MyPOV

    A good SAPtd for SAP, where more of the technical details were in the single sessions than the keynotes. The key product for SAPtd is HCP, and it would have been good to see and and learn more of HCP. It was good to see that Leukert lead with the product, but the real direct value impact from new capabilities came from the new Fiori BUILD capabilities. The message for customers is pretty clear, use HCP, new innovations are coming with micro services, VORA, but it is still early. Cloud for Analyics is a fresh start, Cloud for Planning is a robust planning tool and the new Digital Boardroom is in a maturity state where it makes sense for aggressive enterprises to take an honest look at the product.  
     
    On the concern side SAP needs to cater more to the audience of the event. SAPtd is the key event to move the technical experts, and to show them how to excite their enterprise and how to make money in the next 12 months (are many attendees are freelancers or small entrepreneurs) is pivotal. So SAP should not make the mistake to show and announce product progress no matter what the next event is. To a certain point SAP is victim of its own success, as in the past it was Sapphire for the What? and then SAP TechEd for the How?. Now product release cycles are so fast that SAP is looking for the next event... but it will be key for SAP not to forget who the audience is at SAPtd. The Tuesday keynote was more like a Sapphire than a TechEd / dCode keynote. Anybody doubting, compare 2014 (see here) and 2015 Tuesday keynotes, 2014 was the standard to beat and SAP fell short here.
     
    Nonetheless attendees were forgiving and just went to the sessions (after all they are used to Sapphires) to learn more details, but the opportunity to move 5000+ developers as a group was missed. For me the major takeaway was how far S4/HANA seems to have come, more to check in the next weeks. 
    More on overall SAP strategy and products:


    • Event Preview - SAP TechEd 2015 - watch / read here
    • Event Report - SAP SuccessFactors SuccessConnect - Good Progress sprinkled with innovative ideas and challenging the status quo - read here
    • News Analysis - WorkForce Software Announces Global Reseller Agreement with SAP - read here
    • First Take - SAP SuccessFactors SuccessConnect - Day #1 Keynote Top 3 Takeaways - read here
    • News Analysis - SAP SuccessFactors introduces Next Generation of HCM software - read here
    • News Analysis - SAP delivers next release of SAP HANA - SPS 10 - Ready for BigData and IoT - read here
    • Event Report - SAP Sapphire - Top 3 Positives and Concerns - read here
    • First Take - Bernd Leukert and Steve Singh Day #2 Keynote - read here
    • News Analysis - SAP and IBM join forces ... read here
    • First Take - SAP Sapphire Bill McDermott Day #1 Keynote - read here
    • In Depth - S/4HANA qualities as presented by Plattner - play for play - read here
    • First Take - SAP Cloud for Planning - the next spreadsheet killer is off to a good start - read here
    • Progress Report - SAP HCM makes progress and consolidates - a lot of moving parts - read here
    • First Take - SAP launches S/4HANA - The good, the challenge and the concern - read here


    • First Take - SAP's IoT strategy becomes clearer - read here
    • SAP appoints a CTO - some musings - read here
    • Event Report - SAP's SAPtd - (Finally) more talk on PaaS, good progress and aligning with IBM and Oracle - read here
    • News Analysis - SAP and IBM partner for cloud success - good news - read here
    • Market Move - SAP strikes again - this time it is Concur and the spend into spend management - read here
    • Event Report - SAP SuccessFactors picks up speed - but there remains work to be done - read here
    • First Take - SAP SuccessFactors SuccessConnect - Top 3 Takeaways Day 1 Keynote - read here.
    • Event Report - Sapphire - SAP finds its (unique) path to cloud - read here
    • What I would like SAP to address this Sapphire - read here
    • News Analysis - SAP becomes more about applications - again - read here
    • Market Move - SAP acquires Fieldglass - off to the contingent workforce - early move or reaction? Read here.
    • SAP's startup program keep rolling – read here.
    • Why SAP acquired KXEN? Getting serious about Analytics – read here.
    • SAP steamlines organization further – the Danes are leaving – read here.
    • Reading between the lines… SAP Q2 Earnings – cloudy with potential structural changes – read here.
    • SAP wants to be a technology company, really – read here
    • Why SAP acquired hybris software – read here.
    • SAP gets serious about the cloud – organizationally – read here.
    • Taking stock – what SAP answered and it didn’t answer this Sapphire [2013] – read here.
    • Act III & Final Day – A tale of two conference – Sapphire & SuiteWorld13 – read here.
    • The middle day – 2 keynotes and press releases – Sapphire & SuiteWorld – read here.
    • A tale of 2 keynotes and press releases – Sapphire & SuiteWorld – read here.
    • What I would like SAP to address this Sapphire – read here.
    • Why 3rd party maintenance is key to SAP’s and Oracle’s success – read here.
    • Why SAP acquired Camillion – read here.
    • Why SAP acquired SmartOps – read here.
    • Next in your mall – SAP and Oracle? Read here.


    And more about SAP technology:
    • News Analysis - SAP Unveils New Cloud Platform Services and In-Memory Innovation on Hadoop to Accelerate Digital Transformation – A key milestone for SAP read here
    • HANA Cloud Platform - Revisited - Improvements ahead and turning into a real PaaS - read here
    • News Analysis - SAP commits to CloudFoundry and OpenSource - key steps - but what is the direction? - Read here.
    • News Analysis - SAP moves Ariba Spend Visibility to HANA - Interesting first step in a long journey - read here
    • Launch Report - When BW 7.4 meets HANA it is like 2 + 2 = 5 - but is 5 enough - read here
    • Event Report - BI 2014 and HANA 2014 takeaways - it is all about HANA and Lumira - but is that enough? Read here.
    • News Analysis – SAP slices and dices into more Cloud, and of course more HANA – read here.
    • SAP gets serious about open source and courts developers – about time – read here.
    • My top 3 takeaways from the SAP TechEd keynote – read here.
    • SAP discovers elasticity for HANA – kind of – read here.
    • Can HANA Cloud be elastic? Tough – read here.
    • SAP’s Cloud plans get more cloudy – read here.
    • HANA Enterprise Cloud helps SAP discover the cloud (benefits) – read here.

    Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my YouTube channel here
     
     
    Future of Work Tech Optimization Data to Decisions Digital Safety, Privacy & Cybersecurity Innovation & Product-led Growth New C-Suite SAP SaaS PaaS IaaS Cloud Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP CCaaS UCaaS Collaboration Enterprise Service ML Machine Learning LLMs Agentic AI Generative AI AI Analytics Automation business Marketing finance Healthcare Customer Service Content Management Chief People Officer Chief Information Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer

    Event Report - HR Tech 2015 - Analytics, Compliance and more

    Event Report - HR Tech 2015 - Analytics, Compliance and more

    We had the opportunity to attend the HR Tech conference this week in Las Vegas. New record attendance with close to 30k attendees, record exhibitors, sessions etc. it is clear if you are looking for the latest in HR, you need to be at HR Tech.


    So take a peek:
     
     
    If you can't watch - here are the key takeaways
     
    • Analytics - This remains a key trend to make HR applications better for end users. Hope you could make it to the panel I was honored to moderate on Monday, with the key analytic leaders of Castlight Health, Cornerstone, Equifax Workforce Solutions, Ulimate Software and Workday. We tried to shed some light on why it cannot always be explained why an analytical applications makes a certain decision, hope it resounded with the audience. Unfortunately both Meerkat and Periscope failed... so it can't be shared. But the 500 attendees for sure enjoyed the panel, thanks to the great panelists I had.
       
    • Talent Managmement is alive - We not only see innovation in Recruiting, but also in Performance Management. And working Performance Management is key to make overall Talent Management work. So let's hope that the latest advances on more small time cycle feedback and coaching, coupled with e.g. anonymous feedback, will make a difference.
       
    • UI Innovation is alive - Vendors can't stand still on improving their UIs, which is great news for enterprises, as adoption will accelerate. Making it easier for users to use HR applications is a win / win for enterprises and vendors alike.
       
    • Compliance remains key - ACA offerings have now matured and can be found with almost every vendor. Enterprises should look for breadth and depth on the compliance vendor side, so they don't create a compliance integration problem, on top of the existing integration problems.
       
    • Adoption - Clearly enterprises are using  more from the same vendors, so integration provided by vendors works for both sides, the vendors and the enterprises.

    MyPOV

    Clearly the event to be if you are in HCM, don't miss Chicago next year!


    More on HR Tech coverage:
     
    • HR Tech 2015 Preview - take a look / read here
    • HR Tech 2014 Takeaways - take a look / read here
    • HR Tech 2013 takeaways - read here
    • What to look for at HR Tech 2013 - read here 
    Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my YouTube channel here
    Future of Work Distillation Aftershots Digital Safety, Privacy & Cybersecurity Tech Optimization Innovation & Product-led Growth New C-Suite Data to Decisions Next-Generation Customer Experience Revenue & Growth Effectiveness Marketing Transformation Security AI Analytics Automation CX EX Employee Experience HCM Machine Learning ML SaaS PaaS Cloud Digital Transformation Enterprise Software Enterprise IT Leadership HR LLMs Agentic AI Generative AI business Marketing IaaS Disruptive Technology Enterprise Acceleration Next Gen Apps IoT Blockchain CRM ERP finance Healthcare Customer Service Content Management Collaboration Chief People Officer Chief Information Security Officer Chief Privacy Officer Chief Procurement Officer Chief Customer Officer Chief Human Resources Officer Chief Information Officer Chief Technology Officer Chief Data Officer

    What Storage Industry Consolidation Means for Applications Customers

    What Storage Industry Consolidation Means for Applications Customers

    These are heady times for the storage industry of late, what with Dell’s pending $67 billion acquisition of EMC and Wednesday’s announcement that Western Digital will buy SanDisk for $19 billion. 

    Dell CEO Michael Dell said this week the combined company will be committed to its entire storage product line. As for SanDisk, Western Digital explained its rationale for the deal in a press release:

    The combination is the next step in the transformation of Western Digital into a storage solutions company with global scale, extensive product and technology assets, and deep expertise in non-volatile memory (NVM). With this transaction, Western Digital will double its addressable market and expand its participation in higher-growth segments.

    Overall, a lot of money and installed base is about to change hands in the storage world. What may not be immediately apparent, however is the fact there are implications for enterprise software customers as well, says Constellation Research analyst Holger Mueller.

    “Storage matters for next-generation apps, as all use cases deal with big data scale,” Mueller says. Flash storage is also key to accelerate the delivery of insights within applications, he adds. 

    “It’s ironic: as storage gets cheaper and becomes commoditized, on the other side, data—which leads to storage—is more important than ever, determining where next generation-applications are being built," he adds.

    The Bottom Line

    Consolidation in the storage industry means software customers will have scalable partners for solid-state storage and other storage mediums, Mueller says. But the downside of excessive consolidation—potentially higher costs—is no different in this instance.

    Tech Optimization Chief Information Officer Chief Procurement Officer

    Tech Startup RevJet Reveals World’s First Creative Side Platform (CSP)

    Tech Startup RevJet Reveals World’s First Creative Side Platform (CSP)

    One way to enter the marketplace is to do all your development stealth-style and then announce to the world what you have created. And that, in fact is what RevJet, a tech start-up has done. Atter a year of confidential development, the marketing technology corporation revealed the first-of-its-kind Creative Side Platform (CSP), which extends it’s marketing technology to incorporate the ad creatives that undergird the world’s annual $500 billion media spend directly under the real-time control of marketing departments and their creative agencies.

    So What Does This Mean to You? With the CSP, marketers and their creative agencies can now effortlessly construct, view, serve, measure, and automatically optimize all their ad creatives for all their media buys across all formats — including mobile, social, video and programmatic ad campaigns — all from a single platform.

    What Type of Results Are Companies that use RevJet Experiencing?

    In its first few weeks operating on the RevJet CSP, Microsoft rapidly achieved 100+% performance improvements across diverse digital ad campaigns via dozens of rounds of effortless, automatically optimizing ad creative experiments.

    For years, I’ve preached to my team that we must always be experimenting with ad creatives, but we’ve never had anything like the RevJet CSP to make it happen,” said Grad Conn, CMO lead for Microsoft’s Centralized Marketing Organization. “Their CSP is the first truly comprehensive ad creative platform built to facilitate effortless creative experimentation at its very core. We’re quickly adapting to life on the CSP and are thrilled to onboard four of our creative agencies and two DSPs.

    What’s Different about RevJet? The RevJet CSP is the first and only comprehensive platform designed to enable continuous, automated, high-velocity ad creative experimentation and drive perpetual performance improvement for ad creatives of any format. The underlying CSP technology is already battle-tested in the marketplace, having propelled LifeStreet Media to a $100+ million exit and a market leadership position amongst Facebook app developers.

    RevJet empowers marketers to automatically optimize the creative send to specific audiences in real time across channels and media. As ad tech and marketing tech converge, a platform like RevJet could be used with the whole content marketing process. For Marketers who choose this, it could give them differentiating capability  compared to the competition. In addition, brands that building marketing cloud solutions should consider RevJet a potential differentiator.

    Who is Backing RevJet? Nautic Partners, the Providence-based private equity firm, announced its $66  million LifeStreet investment in 2012, and in October 2014 announced a technology spinoff along with plans to launch RevJet as a standalone marketing technology startup. RevJet is backed by $2.5 billion private equity firm Nautic Partners.

    And a Word From the Founder and CEO “Our CSP is purpose-built to extend marketing technology’s reach, finally unlocking the $500 billion dollars’ worth of pent-up value trapped within the world’s ad creatives,” said Mitchell Weisman, RevJet founder and CEO. “Tapping into this massive value is only possible by scalably increasing the performance of ad creatives across all devices and formats.  Having already used the core CSP technology to build and sell a leading media company for over $100 million, we’re confident the CSP can drive the world’s media spend to go 2x to 3x further.

    Want to Learn More? RevJet CEO Mitchell Weisman and Microsoft’s Diana Choksey will be speaking about the future of creative and tech at the iMedia Breakthrough Summit in Austin this coming Tuesday, October 27th. Learn more here.

    My POV: What’s really interesting is the convergence of technology, as well as silo functional departments in brands. Perhaps software will be the driving force to get departments that don’t always collaborate to do so. Another example of how corporate politics should be a white collar crime – i.e., not collaborating. But the digital disruption is driving more the changes to technology; it’s affecting people, process and technology.

    @DrNatatalie VP and Principal Analyst, Constellation Research

    Share

    Marketing Transformation Chief Marketing Officer