Results

Dell plans to acquire EMC, VMware, Virtustream, Pivotal and more

Dell plans to acquire EMC, VMware, Virtustream, Pivotal and more

This morning, not so much as a surprise after many leaks, it was made official – Dell plans to acquire EMC.  
 
 
Take a look at the thoughts my colleague Ray 'R' Wang and I put together this morning:


So let’s take a look at the press release (it can be found here) in our customary News Analysis style, and then let’s look at the implications:
 
Dell Inc. and EMC Corporation today announced they have signed a definitive agreement under which Dell, together with its owners, Michael S. Dell, founder, chairman and chief executive officer of Dell, MSD Partners and Silver Lake, the global leader in technology investing, will acquire EMC Corporation, while maintaining VMware as a publicly-traded company.
MyPOV – So we know who acquires who, MSD is the investment vehicle of Michael Dell and Silver Lake the partner that Dell used to take itself private. Keeping VMware (see latest blog on VMware, the VMworld event report here) as a separate company is key as we will see later. No word of other EMC federation members though, Pivotal (latest blog post here), RSA, VCE and Virtustream (the newest member of the EMC federation (see the Market Move blog on the acquisition by EMC here).
 
Under the terms of the agreement, EMC shareholders will receive $24.05 per share in cash in addition to tracking stock linked to a portion of EMC’s economic interest in the VMware business. Based on the estimated number of EMC shares outstanding at the close of the transaction, EMC shareholders are expected to receive approximately 0.111 shares of new tracking stock for each EMC share. Assuming, for illustrative purposes, a valuation for each share of tracking stock of $81.78, the intraday volume-weighted average price for VMware on Wednesday, October 7, 2015, EMC shareholders would receive a total combined consideration of $33.15 per EMC share and the total transaction would be valued at approximately $67 billion. The value of the tracking stock may vary from the market price of VMware given the different characteristics and rights of the two stocks.
MyPOV – An interesting vehicle to finance the deal, with VMware tracking stock. We leave it to our colleagues the financial analysts to look more in detail, but it is clear that the VMware stock prices is going to be in the spotlight in the next months. Interesting the announcement is featured on all other EMC federation members’ homepages, but not VMware’s.
 
The EMC Board of Directors approved the merger agreement and intends to recommend that stockholders of EMC approve the agreement.
MyPOV – Important detail…
 
DELIVERING FUTURE-READY TECHNOLOGIES TO CUSTOMERS
The combination of Dell and EMC will create the world’s largest privately-controlled, integrated technology company. The company will be a leader in the extremely attractive high-growth areas of the $2 trillion information technology market with complementary product portfolios, sales teams and R&D investment strategies. The transaction combines two of the world’s greatest technology franchises with leadership positions in servers, storage, virtualization and PCs and it brings together strong capabilities in the fastest growing areas of the industry, including digital transformation, software-defined data center, hybrid cloud, converged infrastructure, mobile and security.
MyPOV – Good point the largest privately controlled technology company. It will be interesting to see if and how Dell can use being private as its advantage. It has certainly show it here, as Dell, the smaller of the two vendors, can acquire EMC, the other way around would probably not have worked. And it is correct – both vendors combine a sizeable part of IT spend, for some customers we estimate north of 50%, for others in the low percentages (e.g. a VMware only customer). But it gives Dell what Dell wanted (and needed) – more access to the CIO office, and a larger portfolio to sell. Once you have that trusted relationship, you can use it to sell more and gain more share of wallet.
 
Since becoming a private company, Dell has had the flexibility and agility to focus completely on customers and invest for long-term results. The transaction will unite Dell’s strength with small business and mid-market customers with EMC’s strength with large enterprises to fuel profitable growth and generate significant cash flows. The combined company will consist of strategically-aligned businesses and incubated high-growth assets, fostering innovation, enabling customer choice and attracting and retaining world-class talent .
MyPOV – And here we have it stated – more CIO office access at larger corporations. True also that there are ‘incubated high growth assets’ (an interesting term) across both vendors, but both still have to show and live up to their growth potential. It is even harder to see that on the Dell side, but never vendor has created a 1B+ software product on the incubator side. Dell will needs a few of those to pull off in the future.
 
“The combination of Dell and EMC creates an enterprise solutions powerhouse bringing our customers industry leading innovation across their entire technology environment. Our new company will be exceptionally well-positioned for growth in the most strategic areas of next generation IT including digital transformation, software-defined data center, converged infrastructure, hybrid cloud, mobile and security,” said Mr. Dell. “Our investments in R&D and innovation along with our privately-controlled structure will give us unmatched scale, strength and flexibility, deepening our relationships with customers of all sizes. I am incredibly excited to partner with the EMC, VMware, Pivotal, VCE, RSA and Virtustream teams and am personally committed to the success of our new company, our customers and partners.”
MyPOV – Good quote from Dell, on the strategic areas he enumerates, we can follow on software defined data center, converged infrastructure (if e.g. Evo comes to Dell servers with force), mobile (Airwatch) and Security (RSA). We are more skeptical on digital transformation and hybrid cloud. On the former, because that involves also SaaS assets, that the combined entity will not have, and the latter as it requires to play in the public cloud, something that neither Dell nor EMC have done so far. Interesting Dell does not call out the EMC ‘bread and butter’ business… storage. Whatever that means for the storage plans we will see. If asked I am sure Dell will see storage as part of the software defined data center, where we are e.g. optimistic around the VMware Nicira assets.
 
“I’m tremendously proud of everything we’ve built at EMC – from humble beginnings as a Boston-based startup to a global, world-class technology company with an unyielding dedication to our customers,” said Joe Tucci, chairman and chief executive officer of EMC. “But the waves of change we now see in our industry are unprecedented and, to navigate this change, we must create a new company for a new era. I truly believe that the combination of EMC and Dell will prove to be a winning combination for our customers, employees, partners and shareholders.”
 MyPOV – An almost sentimental statement by Tucci, which also shows why EMC has not been able to pull it off so far in regards of strategic growth areas (which largely still remains a mystery to me – we will have to wait for the Tucci biography for a shot at this).
 
"We are excited and honored to invest in the outstanding businesses built by Joe Tucci and his world-class management team. This is an extraordinary opportunity to continue and expand our partnership with the iconic technology entrepreneur Michael Dell and his talented team,” said Egon Durban, managing partner of Silver Lake. “We believe the strategic integration of EMC and Dell will generate unparalleled depth and breadth across servers, storage, virtualization and the next era of converged infrastructure, creating a global technology platform poised for sustained long term growth and innovation in the years to come. We are doubling down and increasing our investment in this differentiated market leader for the next paradigm of enterprise computing.”
MyPOV Good quote from Durban, who (finally!) mentions storage, and the other parts of the data center play, servers and virtualization (but misses networking). And yes – Silver Lake is doubling down and betting on Dell to pull this off, ‘only’ the largest tech deal so far. In comparison, the tally for serial acquirer Oracle is around 50B over the last 10+ years.
 
VMware will remain a publicly-traded company and continue to provide customers’ value through leading software- defined data center technology, together with its cloud, mobile and desktop offerings. This transaction is expected to accelerate VMware’s growth across all of its businesses through significant synergies with Dell’s solutions and go-to-market channels. VMware remains committed to investing in and partnering with its strong, industry ecosystem.
MyPOV – And a key point on the independence of VMware again. Fair enough to say the independence of VMware allows for more freedom in partnering, but Dell competitors who are now VMware partners will not forget who owns VMware now… we will have to see if these may mean a move away from VMware in the medium run.
 
TRANSACTION TERMS
The transaction is expected to be financed through a combination of new common equity from Michael S. Dell, MSD Partners, Silver Lake and Temasek, the issuance of tracking stock, as well as new debt financing and cash on hand. There are no financing conditions to the closing of the transaction.

Mr. Dell and related stockholders will own approximately 70 percent of the company’s common equity, excluding the tracking stock, similar to their pre-transaction ownership.

MyPOV – No comments, here interesting that Singapore based Temasek got an in on the deal.
 
Following completion of the transaction, Mr. Dell will lead the combined company as chairman and chief executive officer. Mr. Tucci will continue as chairman and chief executive officer of EMC until the transaction closes. Dell’s headquarters will remain in Round Rock, Texas, and the headquarters of the combined enterprise systems business will be located in Hopkinton, Mass. […]
MyPOV – And that settles the leadership question, as well as when Tucci will resign. Interesting to see the common headquarter will be in Massachusetts, not the cheaper location to do business, but probably important to keep consistency. There seems to be a sentiment in Massachusetts on losing businesses and on the Q&A call it was clear that both Dell and Tucci were ready to address this concern.
 

Implications, Implications

Implications for Customers

As usual when acquisition happen, we recommend customers to make sure that key roadmap items are secured. Combined entities look for synergies, and those synergies may not be aligned with what enterprises have been promised before, or at least made their buying decisions on. Contracts are the weapon of choice to protect IT projects and enterprises from undesired outcomes. In more detail, storage customers should stay the course, unlikely they will see major disruption, but question converged appliances coming from EMC. It is likely that the next generation of appliances coming from the new Dell will be significantly better in price for performance. The VMware portfolio is unlikely to be affected, so stay the course. If building a next generation application projects, Pivotal is unlikely to be affected in the near term, too. Customers should not expect radical new and / or soon solutions to operate the public side of a hybrid cloud solution of the new Dell – as much as we would recommend the vendors to do so. So public cloud projects beyond the current EMC / VMware / Dell reach should stay the course, as project economics are unlikely to change substantially.


Implications for Dell

Rumors are out there that Dell tried to get rid of the consumer PC business before, if true it points to the fist challenge of a combined entity that is struggling to keep up growth on the consumer side. In the same industry HP is just separating B2C and B2B, one development to watch. If Dell can part from its onetime secret to success (cheap PCs), it will be an interesting step to observe. Dell has been able to grow its B2B server business to (estimated) 8B+, a respectable size, but not enough to reach the scale it needs. On the flipside, the Dell Server business is larger than the EMC Federation (excluding EMC) combined. Dell has also been working on a number of software assets, some of them acquired, some of them grown in-house, one of the more prominent ones the integration product formerly known as Boomi. One key area to watch will be, if Dell will embrace the latest VMware appliance, EVO. And the new Python offerings maybe interesting for a new way of running microservices and data centers. I expect the storage offerings to be merged quickly, for whoever remembers the bidding war between HP and Dell a few years ago around 3Par – this is an ironic step today. If the ‘new’ Dell will manage to integrate the technology stack it will be offering more products and services than arch rival HP and IBM, both are weaker in either functionality and or volume of the dimensions of the software defined data center game. From a breadth and depth only Oracle will be ahead of Dell, though clearly trailing on storage. Microsoft just launched its first PC, but we see the PC business as a side note in the overall considerations for the new Dell.


Implications for EMC

It will be interesting to see how long the EMC brand will keep being put on new products. Likely EMC is going into computing history as the ‘one trick pony’ that never made to make it beyond storage to be truly great. We expect the storage product to become part of Dell server combinations soon, everything else is not substantial to worry too long at this point.
 

Implications for EMC Federation companies

So let’s walk through them….

VMware remains the crown jewel in two aspects: For one to finance the deal – with immediate pressure on Gelsinger and team to keep the stock price up. And then for the intimate knowledge of knowing what enterprises run inside their data centers. When I asked Gelsinger why VMware is not doing more to monetize this, his reply was that VMware already is, to which mine was that we need to see more of that then. It will be that more that will make or break much of the success of the new Dell. If Dell can give VMware a homogenous on ramp to Dell owned datacenters, fortified with competitive SLAs, this will be an option CIOs and CTOs will look at with no doubt for the existing loads. If there are savings, why not run even complex load like e.g. SAP and Oracle solutions in the public cloud? As VMware is under pressure to keep up revenue we don’t expect any lower interest on the EUC portfolio. Invigorated by Windows 10, Airwatch and Horizon just have found a few thousand sales people with good CIO access. Monetizing this will be key for the success of the new Dell.

Pivotal remains a mixed story – shining on the PaaS side with CloudFoundry, not convincing on the database side. But even the latter may find new life when combined with the Dell ‘incubated’ products on the Big Data side. Though we remain skeptical, a struggling product family doesn’t get better when combined with a new incubated product family that isn’t fully developed. The story is very different on the PaaS side, where CloudFoundry remains almost the de facto standard for large enterprise PaaS projects. To give these next gen applications being built on CloudFoundry a public cloud home made by Dell is going to be key (instead of losing it largely to AWS and others). That this alignment of PaaS and IaaS works is something we see all over the market, from Oracle and IBM all the way even to Rackspace. Enterprises want to see less crack points and who can give them less integration headache will be a winner for tomorrow’s budgets.

Virtuestream is a short term opportunity – having done well with hosting / putting to the ‘cloud’ complex SAP ERP solutions. That is unique know how that should help the new Dell very well. In the long run though SAP will be better at hosting / putting to the cloud SAP than anyone else, so it is important for Dell to move fast in this regards, and again needs a target / public cloud where to run these loads.

RSA and VCE are beyond my coverage, so won’t mention them here.


Implications for partners

A great day for combined partners, which will get a lot of attention to power the new Dell. Watch for the portfolio cleanup and bet on the right horse early. As these things go, in case of doubt bet on the Dell product. Single vendor partners need to re-think their strategy if they want to try to be all in – but that will be a crowded boat, or if they want to seize the opportunity for a more heterogeneous portfolio. Some great partner enterprises have risen from the ashes of similar difficult scenarios.


Implications for competitors

We expect the competition to try to throw as much FUD against the new Dell as they can possibly create. All these markets are cut throat, Dell knows that. We expect competitors to offer migration offerings, with storage being the largest, and possibly even the most vulnerable target. Enterprises will keep looking for cheaper alternatives from open source vs e.g. VMware. But competitors should not bank on the uncertainty to last longer than two, maybe three quarters. Pressure on Dell to execute is massive, and that will lead to a clear roadmap and execution sooner than later.


Overall MyPOV

A very bold move by Dell, that is not even sure to go down as announced, pending financing and VMware stock value. Business goes on, e.g. VMworld Europe kicks off Tuesday this week and it will be a key event to reassure European customers of what VMware can do. Maybe Michael Dell will jet over there, which probably would be a key endorsement move and could slow some potential ‘Euro frenzy’. The industry has not done well with mega mergers, think of the HP / Compaq merger, but these are key events that are even being reviewed in the press 10+ years later. It will be the same for the Dell / EMC merger that – if Michael Dell and his (new) team can pull it off – will be a remarkable re-invention of the Dell brand, a very different Dell. It will be key to see if Dell can muster the investment to build out a Dell ‘public’ cloud for all the arguments we have listed earlier, that’s where in my view EMC missed the boat. And being later has never helped in the high tech business, but to catch up is getting harder and harder, so speed and execution will be of the essence. We will be watching.


Tech Optimization Innovation & Product-led Growth Next-Generation Customer Experience Data to Decisions Future of Work dell vmware AI ML Machine Learning LLMs Agentic AI Generative AI Analytics Automation B2B B2C CX EX Employee Experience HR HCM business Marketing SaaS PaaS IaaS Supply Chain Growth Cloud Digital Transformation Disruptive Technology eCommerce Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP Leadership finance Customer Service Content Management Collaboration M&A Enterprise Service CCaaS UCaaS Chief Information Officer Chief Technology Officer Chief Digital Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Executive Officer Chief Operating Officer
I love APIs Event Preview

I love APIs Event Preview

We have the opportunity to attend the 'I love API' conference happening in San Jose this week on October 13th and 14th.


Take a peek at my thoughts here:


Or if you don't have a chance to look - read here:
  • APIs become more and more important - No surprise - APIs power more and more of the economy
  • Is is getting easier - or harder - One key area will be to see if it getting easier to build and consume APIs - not even by a developer, but potentially (a savvy) business users.
  • Do APIs scale? - It used to be that APIs could not do brute force interfaces - let's see how they scale up to the 21st century demands. And next to technical scalability, there is also business scalability with aspects like e.g. uptake, monetization, licensing and more.
  • IoT - No surrpise - the hottest next generation application use case features prominently at the conference. 
  • 3 Tracks - Developer, Technologist and Executive - will be interesting to see these three separate tracks. 
If you can make it to San Jose - make sure you step by and say Hello!
 
--------
If you like the video / blog - here are more event previews:
 
  • Event Preview - AWS reInvent 2015 - watch / read here
  • Event Preview - What I would like Salesforce to address this Dreamforce 2015 - watch / read here
  • Event Preview - What I would like Workday to address this Rising - read / watch here
  • Event Preview - What Alan Lepofsky and I want Box to address this BoxWorks - watch / read here
  • Event Preview - What I would like Salesforce to address this Dreamforce 2015 - read / watch here
Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my YouTube channel here
 
 
Tech Optimization Innovation & Product-led Growth Next-Generation Customer Experience Data to Decisions Future of Work User Conference Chief Customer Officer Chief Information Officer Chief Marketing Officer Chief Digital Officer

IOT News: PTC to Acquire Augmented Reality Leader Vuforia from Qualcomm

IOT News: PTC to Acquire Augmented Reality Leader Vuforia from Qualcomm

Why is the PTC acquisition of Vuforia so important? PTC is is a global provider of technology platforms and solutions that transform how companies create, operate, and service the “things” in the Internet of Things (IoT). The company’s next-generation ThingWorx® technology platform gives developers the tools they need to capture, analyze, and capitalize on the vast amounts of data being generated by smart, connected products and systems. The purchase of Vuforia business from Qualcomm Connected Experiences, Inc., a subsidiary of Qualcomm Incorporated extends PTC’s strategy for digital and physical convergence. PTC is committed to continued growth of Vuforia Technology.

Who is Vuforia? Vuforia is one the industry’s most advanced and widely adopted augmented reality (AR) technology platform, and will enrich PTC’s technology portfolio and accelerate PTC’s strategy as a leading provider of technologies and solutions that blend the digital and physical worlds. The agreement says that PTC is committed to continued investment in the Vuforia platform and to the ongoing support and growth of the Vuforia ecosystem.

What’s Mobile Got To Do With It? Vuforia is a mobile vision platform that enables applications (“apps”) to see and connect the physical world with digital experiences that demand attention, drive engagement, and deliver value. Today, Vuforia is supported by a global ecosystem of developers in 130 countries, and has powered more than 20,000 apps with more than 200 million app installs worldwide.

It’s All About the Collaboration. The combination of Vuforia and PTC leverages two transformational technology trends – Internet of Things (IoT) and augmented reality (AR) – to deliver a new class of products that merge the digital and physical worlds. When coupled with PTC’s IoT and analytics platforms, Vuforia unlocks a world of possibilities for creating new ways to design products, to monitor and control products, and to instruct operators and technicians in the appropriate methods of use and service.

What’s Vuforia’s Got Going On? Vuforia has wide adoption from leading companies including 37 of the Interbrand 100 and has consistently been awarded for its performance, robustness, and ease of use, including “Best Tool” at Augmented World Expo in each of the last three years. Vuforia supports multiple developer tools, including Eclipse, xCode, and Unity and runs on multiple operating systems and devices, including iOS and Android phones, tablets, and selected mobile eyewear.

Why is This Partnership Important To Your Business? By delivering powerful computer vision functionality through a simple API, the Vuforia platform will enable developers and leading brands to deliver award-winning experiences to consumers around the globe. Vuforia has the ability to, through augmented reality, to transform work.

For more info, check out the press release.

@DrNatalie, VP and Principal Analyst, Constellation Research

IOT for Customer-Facing Applications that Change Marketing, Sales, Customer Service and Customer Experience in the World of Work


Next-Generation Customer Experience Chief Customer Officer

Dell to Buy EMC for $67 Billion: Five Initial Takeaways

Dell to Buy EMC for $67 Billion: Five Initial Takeaways

After weeks of speculation, Dell and EMC made history on Monday with the announcement of a $67 billion merger deal—the largest in tech history—which will see EMC go private under Dell's ownership. While a transaction of this size and scope will justifiably be scrutinized in depth over the coming weeks, here are some initial takeways for customers to consider.

It's All About VMWare

EMC owns an 81 percent stake in VMWare, which will remain a publicly-traded company after the deal closes. That said, VMWare and the enterprise workloads it runs in companies around the world are the "crown jewels" of the merger, says Constellation Research VP and principal analyst Holger Mueller.

Dell's aim is to transfer those loads to private and public data centers stuffed with Dell servers and software, along with EMC storage, VMWare Airwatch and other assets of the combined company.

"We know much of the future loads will run in the public cloud, so the new Dell has to find a way beyond being an OEM provider for the public clouds as put up by Telcos and others," Mueller adds. "No one knows better what loads enterprises run on-premises than VMware. When to move and transfer this load beyond on-premises data centers is the master plan."

A Pivotal Move

Dell CEO Michael Dell and EMC CEO Joe Tucci didn't talk much about software on Monday's conference calls for the deal. But software, specifically enterprise application development and delivery, could end up being a major growth engine for the combined company. "If executed right, Dell owns the majority of Pivotal, the most popular enterprise PaaS, and has a seat at the table for next-generation applications," Mueller says.

Open for Business?

Dell intends to continue partnerships such as VCE, the converged infrastructure venture between EMC, VMware and Cisco, and customers will have a wide set of choices," according to executives. Nor will Dell push VMWare exclusively as a virtualization platform, according to Michael Dell. Expect continuations of EMC's strong partnerships with the likes of Lenovo and Hewlett-Packard as well, executives said.

Paying for the Deal

Dell, along with Silver Lake Partners and MSD Partners, is taking on massive bank debt to acquire EMC. The plan is to significantly deleverage that debt over the next 18 to 24 months, in part due to "cost synergies," according to Silver Lake managing partner Egon Durban. While layoffs are expected, executives provided no specifics on Monday. 

Another way Dell could generate capital to pay down the debt would be through divestures of EMC product lines, with the VMware stake clearly being the most lucrative option.

The Bottom Line 

All of the sentiments and expectations about strategic synergies aside, this is a mega-merger that carries massive risk and uncertainty - as with any deal of such size. Dell and EMC customers should prepare for a long, complex integration process, as well as the potential for significant changes in their sales and support relationships with both companies. 

Customers at the beginning or middle stages of their public and private cloud journey will also be presented with a major new choice for a strategic provider. 

“Dell has a lot of free cash flow from the deal and has a once-in-a-life time opportunity to restructure its portfolio to compete not only in private cloud, but gain scale to compete with Amazon for cloud IaaS and PaaS," says Constellation Research founder Ray Wang.

For additional analysis, check out Mueller and Wang's Google Hangout discussion on the deal below.


Data to Decisions Tech Optimization Chief Executive Officer Chief Information Officer

Inside the SportsBiz Studio: Bob Hamer

Inside the SportsBiz Studio: Bob Hamer

1

Welcome to another edition of Inside the SportsBiz Studio! This is my version of Inside the Actor’s Studio where I will feature a Q&A with another sports business professional willing to share insights from their career and opinions about the state of the industry. Just like the TV show, there will be some common questions that everyone answers as well as questions tailored to each individual’s background in the industry.

BobHamer

Our next guest is Bob Hamer, President of Sports Business Solutions.

What was your first #sportsbiz job?

I was an intern with the Charlotte Bobcats & Sting during the Summer of 2005.

What was one lesson from that first job you still carry with you today?

The importance of learning and building relationships. We can always get better, and this industry is all about your network.

Who was a key mentor for you and how did they help?

My first boss Jeff Ianello. He gave me my first full time opportunity in Inside Sales at the Suns in 2006. He constantly pushed and challenged me to get better and it wasn’t always easy but he was always there when I needed help too. He saw something in me early on and continued giving me additional responsibilities and room to grow my career. I owe a lot of my professional success to him.

What sports brand or organization do you hold in the highest regard and why?

It’s hard to pick one and I have a lot of teams I’m close to that I really respect, but I’d say in general the NBA and its family of teams. What they do with their TMBO (Team Marketing and Business Operations) consulting group and how they share best practices to elevate the performance of all of the teams is very impressive and something I’ve always admired.

What is one industry trend you are closely monitoring over the next 12 months?

Social selling and sports sales 2.0. The game is changing and I’m eager to see how teams utilize data and technology to be more efficient in their sales processes.

What one professional accomplishment are you most proud of today?

Becoming a Vice President in the NBA. I never could have imagined it in my wildest dreams. And to do it all in Phoenix with the Suns, a team I loved working for in a market I loved living in was really special. There aren’t many examples of someone starting in Inside Sales and ending up as a VP with the same team, I’m very proud of that.

In your time at the Suns, how did you see the landscape of ticket sales change?

Data & technology. Getting smarter about our pricing (variable and dynamic), more information on our customers, sourcing our sales and focusing our efforts where we saw the greatest return. In general, operating the business more strategically. We’ve come a long way from the phone book!

Everyone is focused on how millennials are different as both customers and employees. How do you see this affecting the industry?

I think it’s exciting! They bring a knowledge of digital and social media that I think is vital long term. They want to know the why behind what we do and want continual coaching, training and development, all of which will help create a more engaged work force that’s developing constantly. It’s a more fluid work environment which keeps it new and fresh, I think that’s all very positive. In terms of customers, people will always love sports and entertainment, and they’ll see business value in being a partner with sports teams so I don’t think it’ll change too much there.

What is one underrated skill that you look for when recruiting new talent?

Ambition. I want to find people that want to be the best at what they do and are willing to put in the time and energy necessary to do so. We can teach and train you but we can’t teach the intangibles like hard work and passion.

What can candidates do to make themselves stand out better, from their resume all the way to the interview?

Go beyond just applying for the job. Be proactive, develop relationships with people in the organization, get connected through a mutual contact. If you’re referred over to a hiring manager for a job you’re much more likely to get an interview than applying cold. Don’t play the waiting game, go out and get it.

You can connect with Bob on LinkedIn or on Twitter at @SportsBizBob.

Musings: Dealing With The Startup Who Went Public And Is Now Arrogant As Hell

Musings: Dealing With The Startup Who Went Public And Is Now Arrogant As Hell

Best of Breed Startups Often Initially Differentiate And Delight Customers With Extreme Customer Centricity

The journey to an initial public offering (IPO) often brings an intense customer-centric culture and focus that separates the startup vendors from their legacy competitors.  These startup vendors woo their prospects with not only their emerging technologies and solutions, but also a commitment to enable their customer’s to deliver on disruptive business models.  These vendors earn their market share and mind share by delivering on this brand promise.  When customers partner with these vendors, they:

  1. Gain direct access to the company’s decision makers.  The founders and key executives spend time with the prospects and clients.  All parties establish strong relationships and even friendships.
  2. Yield significant influence on product road map.  Vendors care about customer’s requirements.  Each side works to identify what is a platform, a core feature, configurable option, and a customization.  Platform and core feature requests often center around industry, geography, and business models.  Each side is vested with symbiotic success.
  3. Receive extreme customer service and success. Issues with bugs, broken functionality, and implementation issues receive instant response by vendors.  Their goal is to ensure the customer’s go-live and success.
  4. Secure pricing discounts for early adoption.   Early adopters receive a risk discount for betting early and partnering with new startups.  These discounts often reflect the amount of joint effort required to take a solution live.
  5. Evangelize success in sharing their stories. Vendors shower customers with opportunities to tell their story.  Client success leads to media exposure, customer events, and career promotion.  In many cases, the vendor may offer the client an opportunity to work for them as well.

This vendor-customer partnership leads to an amazing growth for the vendor and great success for the customer.  The reward for freeing themselves from the shackles of legacy technology providers delivers massive gains.   The emergence of a successful new market category encourages other startups to follow suit and forces legacy vendors to respond to this new customer centricity.  As a result, the industry advances forward while clients and prospects take steps to accelerate their business and technology strategy based on these experiences.

Post-IPO Or Acquisition, Most Startups Act More Like The Legacy Vendors They Replaced

Once public or acquired, these organizations struggle to retain their culture of innovation, customer centricity, and growth rates.  The push to IPO often drives the company into 80 to 120% CAGR.  Post IPO, they must deliver more consistent growth.  So long they deliver more than 40% organic and inorganic growth year-over-year, investors leave the newly minted publicly traded company alone.   However, in many cases, the push to IPO stretches their ability to continue growth at breakneck speeds.  How the startup achieves IPO often dictates their ability to succeed post-IPO.  A bad business model will fall apart post-IPO (see Figure 1)

Figure 1. The Life Cycle Of Startups

JumpStart Growth

As the shiny new object faces the pressure of public markets, the focus on growth or focus on profit margin often shifts the company culture.  Announcements of experienced industry veterans joining the ranks often lead to standardization and a push to scale the business.  Now public, the post-IPO business types take over to scale the business.  They attract MBAs to join the ranks.  This new wave of employees bring their case study approach and cast aside the core ideals.  They often take credit for other people’s work.  Teams start focusing on politics instead of delivering on sales or product.  Pre-IPO folks battle the post-IPO folks.  The new managers force an overhead and level of process required to scale.

The result – the startup types and company heroes who took the company to IPO begin a slow ebb of departures.  In some cases, the founders leave within a year.  Now keep in mind, these individuals were hired in the startup phase because they knew when to do the right thing for the customer.  They didn’t have playbooks, process maps, approval requirements.  They often changed jobs on a monthly basis, reached across functional fiefdoms to deliver for the customer.  They didn’t care what metrics were good for one department versus another.   They delivered on the brand promise and were empowered.  They could talk to management without having to go through a gopher.  There was a meritocracy.  In many cases, they were inefficient, they were not consistent, and they didn’t take orders well from management.   However, they did what was good for the company and could see the impact of their contributions.  Unfortunately, over time the corporate types drive a culture clash that leads to an exodus of innovation and talent.

Customers do notice a change in the company’s behavior and culture.  Decisions that used to take days now take weeks.  A favorite service agent or sales rep leaves.  Calls for new requirements go unanswered.  As these post-IPO companies exhibit more and more legacy incumbent like bad behavior, customers begin to complain.  Partners and system integrators notice a fractious relationship.  The great hot-flying startup slowly takes on the characteristics of the legacy incumbents they replaced.  New startups challenge their position.

Early Adopter Customers Face This Arrogance Right Now From Successful Startup To Newly Minted Public Companies

Market leaders and fast followers now face challenges when dealing with west-coast VC backed startups who finally become newly minted public companies and extremely arrogant.  This also happens in acquisition.

Right now a growing number of customers face this arrogance from their favorite startup in social business, mobile enablement, cloud, big data, and unified communications.   Without naming the vendors acting on their worst behavior, here are some true customer quotes from conversations with hundreds of clients:

  • “Upon renewal, my favorite HR Tech startup jacked up my rates 25% on renewal”
  • “I was told by our CRM/CX vendor that we were no longer important to the company now that we have bigger clients”
  • “My cloud HRTech vendor told me that our rates were significantly discounted in our initial deal and despite our divestiture, you now have to pay up, so we won’t be reducing your costs”
  • “We used to receive excellent response times to our feature requests from our collaboration vendor, now they push out products we don’t care for and expect us to pay for them”
  • “We’ve been complaining about the mobile UI for the past three years.  In the past, we would at least have some influence on the product direction.  Since we have no new additional sales, our new sales guy ignores us”
  • “Our relationship with our HRTech sales person has gone down hill. Despite helping him out early and a repeat customer in many deals, they are only focused on new sales and no longer spend time building out our relationship”
  • “We’re moving back to the legacy vendors who have figured out the the best of breed is now a feature in their stack/platform”
  • “The company is now PR driven, not product driven. They are more worried about appearances than hearing the truth”

Analysts Often Recognize Five Factors Of A Failing Vendor

Constellation often can tell when a vendor has made the shift into arrogance from five factors:

  1. Vendors begin selling vapor ware with product announcements six months out.  Releases are late and products are shipped with questionable customer value.
  2. Corporate communication teams (influencer relations, analyst relations, public relations) clamp down on access to key executives.  They play gate keeper to the analysts and want to be in control of all communications and budget.  Instead of enabling change and input, they shut down dialogue and add friction to the relationship.
  3. Executives no longer have thick skin in taking private criticism.  They’d rather hear happy thoughts than face reality when presented with the facts.  They shun direct feedback and focus on keeping to the message.
  4. Founders and key employees exit the company and are replaced by post-IPO margin types.  The replacements bring bad habits from the legacy companies they came from and drag down the company culture.
  5. Partners complain about the difficulty in working with the vendor.  Vendors begin to compete with partners for their revenue streams.  Partners no longer trust a handshake deal.

The Bottom Line: Business And Technology Strategy Must Account For The Post-IPO Jekyll And Hyde

To avoid the Post-IPO Jekyll and Hyde, Constellation suggests three concrete steps to minimize the damage.  For existing customers, successful application of these three principles in contract renewals will help refocus the relationship to a win-win paradigm:

  1. Use the Customer Bill of Rights in all contract negotiations.  Make sure you protect yourself from the life cycle of technology engagement.
  2. Leverage industry analysts to keep the vendors in line.  By serving as a third party confidant, analysts can bridge the gap between the vendor and the customer.  More importantly, the poor treatment of a client by a vendor impacts the analyst’s perception of a vendor.
  3. Line up alternatives.  Begin the process of finding alternatives.  Good candidates include organizations who have put the startup features into their suite or platform.

For more customized approaches, feel free to reach out to any member of the Constellation team.

Your POV.

Are you tired of the arrogant public-IPO startup who’s broken your relationship?  Want to move back to a win-win?

Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org.

Reprints

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales .

Disclosure

Although we work closely with many mega software vendors, we want you to trust us. For the full disclosure policy,stay tuned for the full client list on the Constellation Research website.

* Not responsible for any factual errors or omissions.  However, happy to correct any errors upon email receipt.

Copyright © 2001 -2015 R Wang and Insider Associates, LLC All rights reserved.
Contact the Sales team to purchase this report on a a la carte basis or join the Constellation Customer Experience

The post Monday’s Musings: Dealing With The Startup Who Went Public And Is Now Arrogant As Hell appeared first on A Software Insider's Point of View.

Next-Generation Customer Experience Innovation & Product-led Growth B2C CX Leadership Chief Customer Officer Chief Information Officer Chief People Officer Chief Human Resources Officer Chief Experience Officer

CSCMP – three lessons for digital supply chain leaders

CSCMP – three lessons for digital supply chain leaders

Last week  spent the majority it of it in San Diego, enjoying the warm southern California weather and sun. Why was I there? Attending the annual CSCMP conference. The conference was, as usual, well attended by an array of supply chain professionals. As in previous years, the event offered a wide array of break out sessions and interactions with fellow professionals. Three take aways from the event:

  1. The importance of labor – it’s the people stupid. To borrow a line from James Carville, well at least part of the line. What was interesting and I was glad to hear, was the importance being placed on labor in the supply chain. We have seen this rise in labor importance in the retail world. We are all keenly aware of the growing change in the store front. Retailers, with brick and mortar, are looking to these assets under a different light. They are looking to transform these assets into destinations, think Restoration Hardware or Williams Sonoma. Others, such as Finish Line and Macy’s are looking to fulfill eCommerce orders directly from stores. While these changes to how their supply chain fulfills orders has a direct impact on inventory strategies they also have a secondary effect on labor. Employees both within the store but also in warehouses and logistics will have to add skills and new responsibilities to their daily routines. CxOs will have to ensure they empower this labor with the proper training, incentives and technology to ensure success. Bottom line is labor in the supply chain often is the touch point between the supply chain and the customer. CxOs cannot afford to ignore this crucial link. As Howard Shultz CEO of Starbucks stated from main stage – the most important asset for Starbucks are the ones wearing the green aprons.
    images

    The coffee giant’s greatest assets – the ones in green.

  2. Mission impossible for logistics – okay that might be an overstatement, but the reality is that our logistics networks, both warehousing and transportation, are being asked to do more. Logistics professionals should not expect this to abate any time soon. Delivery to the home, to lockers, even to the trunk of your car are all pushing last mile delivery capabilities to their limit. What will happen when the FAA loosens up drone regulations? This is driven entirely by the empowered consumer. As role and influence of the consumer continues to force supply chains to react to their demands, logistics will have to shoulder a greater amount of the burden. Supply chains will have to be ever nimble with their logistics to meet these demands. For example, Hostess had to ensure they have the necessary distribution centers (DCs), strategically located to meet exploding demand when they reintroduced their delicious Twinkies and Cupcakes to the market. The challenge became being able to readjust their strategy on the fly as the demand patterns became apparent. The success for Hostess rested in large part to their ability to have the proper levels of inventory in the right DCs. CxOs will need to be constantly evaluating all their logistics components of their supply chains to ensure they are in the best position to satisfy their customers’ expectations. They must also be willing to change strategies and tactics as needs evolve. Look for new business services such as the ones offered by Flexe who is using crowd-sourcing to fill excess warehousing space. As well as Amazon who announced the launching of Amazon Flex. Bring the same business model as Lyft, Uber and Airbnb to package delivery. Amazon Flex will open up package delivery to anyone who has a vehicle to become last mile delivery assets.
    Can your warehouse and logistics keep up?

    Can your warehouse and logistics keep up?

  3. Eat your own lunch otherwise someone else will – digital continues to accelerate disruption all across the supply chain.  Disruptive technologies such as IoT, robotics and augmented reality were all on display at CSCMP. Smart labels by Johnny Walker were discussed and how they can provide the consumer with additional insight about what they are consuming but also the distributor with regards to the location of inventory and the pace of consumption. Computing giant HP is leveraging connected printers to proactively order ink when the machine detects the level drops below a certain range. Companies such as Lids.com are using robotics from Swisslog to manage their DCs. Distribution companies such as DHL replacing traditional handhelds with augmented reality for their packing professionals, reducing errors and increasing velocity. Manufacturers such as GE are adding connectivity capabilities to their high end refrigerators…not because they have a use case for a connected ice box but to lay down the ground work for possible use cases. More than ever, CxOs must be watching for digital disruptions that are are currently impacting their businesses or those that are just over the horizon. These are also going to impact different parts of their supply chain – just complicating the matter.

After leaving San Diego my believe that we are on the verge of seeing some major changes through out our supply chains was reinforced. While it may sound cliche, the digital supply chain is going to change how we approach this space in ways we have not even imagined. CxOs are in the midst of exciting times. Those that embrace this will flourish, those that cling to their old thinking will be left behind. Quickly.

Looking forward to CSCMP next year back on the East Coast in Orland Florida.


Matrix Commerce Innovation & Product-led Growth Supply Chain Automation Cloud Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software IoT Blockchain ERP Leadership Collaboration M&A Chief Information Officer Chief Supply Chain Officer

The General Mills Cheerios Recall and Your Supply Chain

The General Mills Cheerios Recall and Your Supply Chain

Supply chain professionals everywhere are no doubt wincing about the recent recall of nearly two million boxes of Cheerios by General Mills—turns out they weren’t gluten-free after all. From the Washington Post:

Jim Murphy, senior vice president of the company's cereal division, said he was "embarrassed and truly sorry" by an incident that allowed wheat flour to get introduced into the gluten-free oat flour system at a production facility in Lodi, Calif.

The "undeclared allergen" could cause adverse health effects for those with wheat allergies, celiac disease or gluten intolerance.

The Lodi facility lost rail access for a time, forcing General Mills to load the flour onto trucks for delivery. As a result of “purely human error,” wheat flour ended up getting intermingled with the oat flour, according to the Post.

Could It Have Been Avoided?

"One of the big things in supply chain that vendors and service providers are trying to figure out is how to do better track and trace," says Constellation Research VP and principal analyst Guy Courtin.

"That might not necessarily have avoided what happened at General Mills, but what it would have done is warned them sooner and help them rectify the problem sooner," he adds. "All it takes is a missed order on one truck and all of a sudden you've ruined everything you thought you had set up."

The Bottom Line

General Mills' Cheerios mishap provides a call to action for supply-chain pros. Examine your track-and-trace systems for weaknesses and look for ways to improve them, whether through IoT initiatives or better inspections checking processes, Courtin says. 

Incidents like it "just go to show that our supply chains are getting increasingly complex, increasingly strained by time constraints—people want things faster—you just need better checks and balances along the way to make sure these things don't happen," Courtin says.

Another tip for supply-chain pros: "Make sure your mindset is to be more cognizant of this stuff. Make it more of a priority."

The stakes vary according to different industries, Courtin notes. "If you're a food supplier and you screw something up, you might go out of business." But in pharmaceuticals, "if you screw up some of the supply chain there, you go to jail." 


Data to Decisions Matrix Commerce Tech Optimization Chief Information Officer Chief Procurement Officer Chief Supply Chain Officer

Customer Experience Leadership: 5 Pitfalls to Avoid

Customer Experience Leadership: 5 Pitfalls to Avoid

The importance of leading the customer experience cannot be understated. However, if the CMO steps into this role, there are risks that come along with the rewards. It may mean, in some organizations, that you’ll have to start by wearing a flak jacket to repel those who want to do you in. While that sounds harsh, those who have tried to lead new initiatives and were some of the first people who ventured out and did it, like social media, have been seen in the organization as early adopters. Most people in corporate America, though, are members of the early majority and late majority in terms of adoption of new ideas.

As a result, if you are an innovator or early adopter, be prepared that others may not see what you see. They may require a business case and more details on why you want to change the organization. If you know this in advance, it will save you a lot of heartache and make you much more successful.

Screen Shot 2015-09-30 at 2.31.40 PM

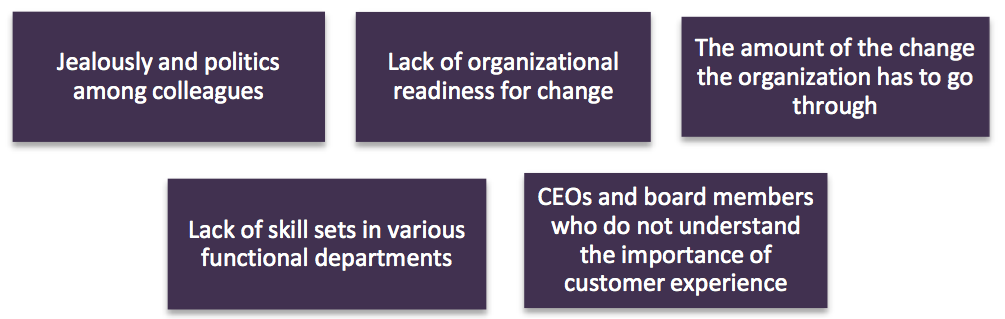
The five “gotchas” our research uncovered for CMO’s (or whomever is leading customer experience) to watch out for include:

  1. Jealously and politics among colleagues
  2. Lack of organizational readiness
  3. Lack of skill sets in functional departments
  4. The amount of change the organization has to go through
  5. CEOs and board members who do not understand the importance of customer experience.

It is highly recommended that if you step into the Customer Experience Management role, you have full backing from the CEO and board members for all decision-making and ample resources in people, budget and technology. Projects without this will be doomed to fail. What has your experience been with leading change?

Resource

Read my latest research report, Should the CMO Lead the Customer Experience?  Download the table of contents and an excerpt of the report here: http://info.constellationr.com/report-download-cmo-oversee-customer-experience


Next-Generation Customer Experience B2C CX Chief Customer Officer Chief People Officer Chief Human Resources Officer

7 Ways for CMOs to Thrive When Leading Customer Experience

7 Ways for CMOs to Thrive When Leading Customer Experience

As brands realize Customer Experience Management is key to their overall strategy and long-term growth, our research at Constellation found CMOs should consider the following 7 principles when leading customer experience initiatives:

  1. Bring passion about the brand you work for and drive cross-functional collaboration and lead organizational change
  2. Focus on both communications and brand guardianship as well as innovation, product and business responsibilities
  3. Balance the brand view and the business view so the CEO takes you seriously
  4. Gain mastery of technical and non-technical skills: it’s critical
  5. Use data and predictive insights to deliver real-time, optimized customer experiences
  6. Evolve into a strong, well-balanced leader of cross-functional teams and groom successors and
  7. Gain design-thinking experience.

Leaders of Customer Experience Management must have an emotional tie to the brand, identify with it and want to share the value it brings to customers. The CMO must be passionate about championing the customer experience and leading the development of the strategies, activities and tactics to create and sustain demand. Marketing must become the cross-functional voice of the customer. Having some organizational change management skills is very helpful to be able to lead the change, and is an inherent part of the changing role of the CMO, especially if they take on an end-to-end customer experience position.

 
The Reward for being a Great CMO? With a winning brand, you will be a CMO that not only knows how to adapt to change, but actually anticipates and drives it. You will be a CMO that knows how to cascade change down and across an organization so the changes to roles, processes, technology and its integration are accepted. You will be able to accomplish this by leading the employees in all departments. You will be able to structure teams to establish a culture that embraces change.
 
Your leadership will cut across functional department boundaries and get everyone on board, behind a vision and into a new way of working collaboratively. This may mean fixing processes that are broken or that no longer make sense. The reward is knowing that you have created an environment where cross-functional teams are not threatened by change, but instead embrace it and find ways to optimize the opportunities change brings.
 
What Does Leadership Have To Do With It? You will need to be a great leader. Just because someone is appointed to a position does not mean they actually have all the skills to get people to follow a new way of doing things. Asking for feedback on leadership skills is key prior to taking a new role. The innovation you will be responsible for can come in the form of how a brand enables customers to find, consume, participate in, talk about and share content about the brand.
 
Customers often control a majority of the dialogue about the brand and Marketing must be ready to talk directly to customers. This is new. In the past, marketers were accustomed to pushing content or campaigns out, but not having to respond. Social and digital media completely changed that with the likes of Facebook, Twitter, and customer communities. Influencing others is key, especially when communicating and engaging with so many different departments, with different agendas and success criteria. Often Marketing delivers a brand promise and other departments, like Customer Service, is tasked to deliver on it. So collaboration is key.
 
People Want to Follow Great Leaders. Times have changed, customer expectations have changed and now brands have to follow suit. Ask yourself, “Would you follow you?Are you able to lead the traditional responsibilities a CMO has had as well as the whole customer experience, which requires you to collaborate with many functional departments?  How is your company handling the leadership of customer experience?

Resource

Read my latest research report, Should the CMO Lead the Customer Experience?  Download the table of contents and an excerpt of the report here: http://info.constellationr.com/report-download-cmo-oversee-customer-experience


Next-Generation Customer Experience Chief Customer Officer Chief Marketing Officer