Results

Oracle databases everywhere with AWS partnership, strong Q1 results

Oracle databases everywhere with AWS partnership, strong Q1 results

Oracle and Amazon Web Services announced a strategic partnership to complete CTO Larry Ellison's multicloud trifecta. Oracle first partnered with Microsoft Azure, then Google Cloud and now AWS. Oracle also delivered strong cloud revenue growth in the first quarter. 

The two cloud providers launched Oracle Database@AWS, which allows customers to access Oracle Autonomous Database on dedicated data centers and Oracle Exadata Database Service within AWS.

Oracle said Oracle Database@AWS will unify Oracle Cloud Infrastructure (OCI) and AWS for database administration, billing and customer support. Enterprises will also be able to connect enterprise data in Oracle to applications running on Amazon EC2, analytics services and AI services including Amazon Bedrock. Procurement will be simplified through AWS Marketplace so enterprises can purchase Oracle Database services using their AWS commitments and existing Oracle licenses. Big software deals closing on AWS Marketplace, rival efforts

In addition, Oracle CTO Larry Ellison and AWS CEO Matt Garman will talk about the partnership on Tuesday at Oracle CloudWorld. The partnership is part of Oracle's broader multicloud strategy. Oracle Database@Google Cloud, which was announced last quarter, is now generally available. Multi-cloud computing isn't 'a bunch of separate clouds'

"We are seeing huge demand from customers that want to use multiple clouds," said Ellison. "To meet this demand and give customers the choice and flexibility they want." Garmin added that the partnership will give joint customers more flexibility and scalability.

Ellison said Oracle's cloud business is benefiting from its Nvidia GPU clusters as well as autonomous database. "Our large and loyal customer base understand and appreciate the many technical advantages of using the Oracle database, and those customers wanted us to find a way to make the very latest and best Oracle technology available on other cloud," said Ellison. "We believe our cloud partnerships with AWS and Microsoft and Google will turbocharge the growth of our database business for years to come."

The Universal Database Versus a Suite of Specialized Databases

Oracle Database@AWS will be available in preview later this year with broader availability in 2025. For Oracle, the AWS deal is big since it now can offer its database services across every hyperscale cloud.

Key items about the partnership include:

  • Direct access between Oracle database services and AWS will be provided via a low latency network connection.
  • AWS customers will be able to use Oracle Autonomous Database seamlessly.
  • Zero-ETL integration will run between Oracle Database services and AWS Analytics services.
  • Oracle database services will seamlessly be integrated with Amazon S3.
  • Oracle Database@AWS can be launched via the Amazon Management Console, Command Line Interface and AWS CloudFormation.

Fidelity, Best Buy and State Street were among the joint customers touting the partnership.

Ellison said the AI race is a marathon not a sprint and it requires all parts of the data center. 

"This race goes on forever to build a better neural network. And the cost of that training gets to be astronomical. When I talk about building gigawatt or multi-gigawatt data centers, I mean these AI models, these frontier models are going to -- the entry price for a real frontier model from someone who wants to compete in that area is about $100 billion. Let me repeat, around $100 billion. That's over the next four, five years for anyone who wants to play in that game. That's a lot of money. And it doesn't get easier."

"Let me say something that's going to sound really bizarre. Well, I probably -- you'd probably say, well, he says bizarre things all the time. So why is he announcing this one? It must be really bizarre. So we're in the middle of designing a data center that's north of the gigawatt that has -- but we found the location and the power place. We look at it, they've already got building permits for three nuclear reactors. These are the small modular nuclear reactors to power the data center. This is how crazy it's getting. This is what's going on."

Separately, Oracle announced first quarter earnings of $1.03 a share on revenue of $13.3 billion, up 7% from a year ago. Non-GAAP earnings in the first quarter were $1.39 a share, 6 cents a share better than estimates.

By the numbers:

  • First quarter cloud revenue was $5.6 billion, up 21% from a year ago.
  • Cloud infrastructure revenue was $2.2 billion, up 455 from a year ago.
  • SaaS revenue was $3.5 billion, up 10% from a year ago.
  • Cloud ERP revenue was $900 million, up 16% and NetSuite first quarter revenue was also $900 million, up 20%.

Oracle CEO Safra Catz said cloud services are now the company's largest business and operating income and earnings growth are accelerating.

Ellison added that Oracle now has 162 cloud data centers. In the first quarter, Oracle signed 42 additional GPU contracts valued at $3 billion. Oracle has 7 OCI regions live at Microsoft with 24 more being built and 4 with Google Cloud with another 14 on tap.

As for the outlook, Catz said Oracle's database business will accelerate with all of the hyperscalers in the mix. Catz said:

  • Oracle spent $2.3 billion in capital expenditures in the first quarter. Fiscal 2025 capex will be double 2024. 
  • "We remain very confident and committed to full year total revenue growth growing double digits and full year total cloud infrastructure revenue growing faster than last year."
  • Total revenue in the second quarter will 7% to 9%. Cloud revenue will grow 23% to 25%. 
  • Non-GAAP earnings in the second quarter will be between $1.42 a share to $1.46 a share. 

Constellation Research's take

Constellation Research analyst Holger Mueller said:

"Oracle had another very good quarter. Its Q1 is traditionally a sluggish quarter dating back in the on premises days, and the strength shows Oracle's transition to services and subscriptions. All regions grew as well which demonstrates the global appeal of the Oracle offering portfolio.  Oracle is building a lot of datacenters, buying a lot of GPUs and now partnering with AWS along with Google and Microsoft. All of those partnerships require CAPEX to put the Exadata machines where they need to be for an attractive customer experience.

Oracle invested close to $8 billion in CAPEX in Q1, but at a lower rate of using free cash flow (it was 47% now down to 41% - but Oracle added almost $1.5B to cash flow). With a build out of a total of 31 datacenters planned for Microsoft (7 live, 24 to be built), 18 planned for Google (4 live and 14 to be built), and an amount to be built for AWS, Oracle will have to keep investing. 

No wonder infrastructure revenue grows with 45%, with Oracle Cloud ERP growing a respectable 16% and NetSuite revenue growth at 20%. Those are very good growth rates during uncertain overall economic times. Oracle has never been closer to the original Larry Ellison vision of becoming the IBM of the 21st century and providing all that enterprises need across the stack – from the hardware to SaaS – with a strong commitment to compete in the multicloud. 

Lastly it is clear that competition to unseat Oracle as the leading transactional, mission critical relational database has folded, AWS was the last competitor standing. The future is coopetition now. Oracle can’t rest on its laurels, as it needs to keep enterprise data in its databases, delivering strong on vector search (bringing AI to the database) and strong and easy uptake of RAG (allowing data to stay in the database for validation)." 
Data to Decisions Tech Optimization Innovation & Product-led Growth Future of Work Next-Generation Customer Experience Digital Safety, Privacy & Cybersecurity amazon Oracle Big Data AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer Chief Executive Officer Chief AI Officer Chief Analytics Officer Chief Product Officer

Apple iPhone 16 event: How an AirPod Pro hearing aid stole the innovation show

Apple iPhone 16 event: How an AirPod Pro hearing aid stole the innovation show

Apple’s iPhone 16 event added a bevy of hardware upgrades in a bid to entice customers to upgrade devices even though Apple Intelligence will be delivered via software updates over the next year. Apple, however, does have a knack for useful killer apps and AirPod Pro as a clinical grade hearing aid will sell well.

Based on innovation, I'd rank the event this way.

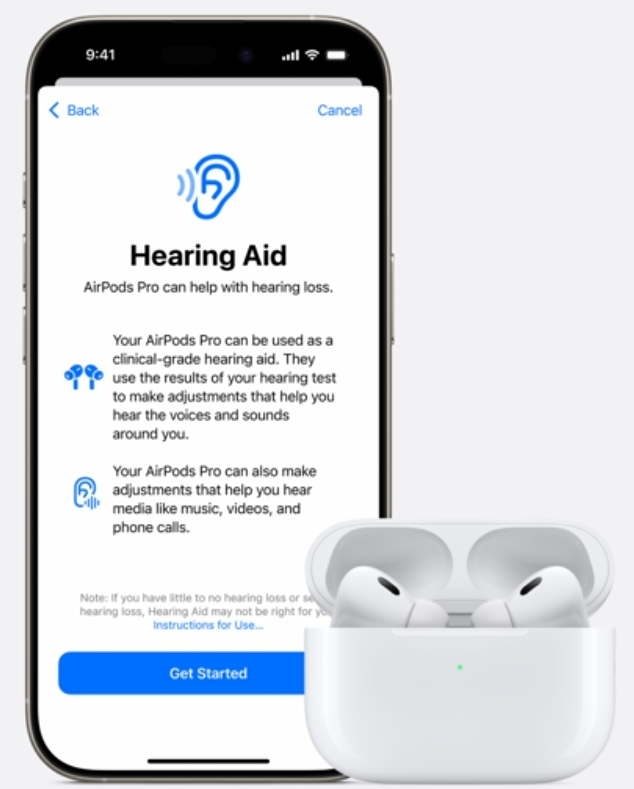
  • AirPod Pro becomes a hearing aid. Given the sheer number of people with untreated hearing loss looking to avoid stigma, Apple will quickly have a hit--once it gets FDA approval. 
  • Apple launches A18 Pro, a chip that the company claims is the most powerful on any smartphone.
  • Apple launches A18 processor that is supposed to rival PC chips.
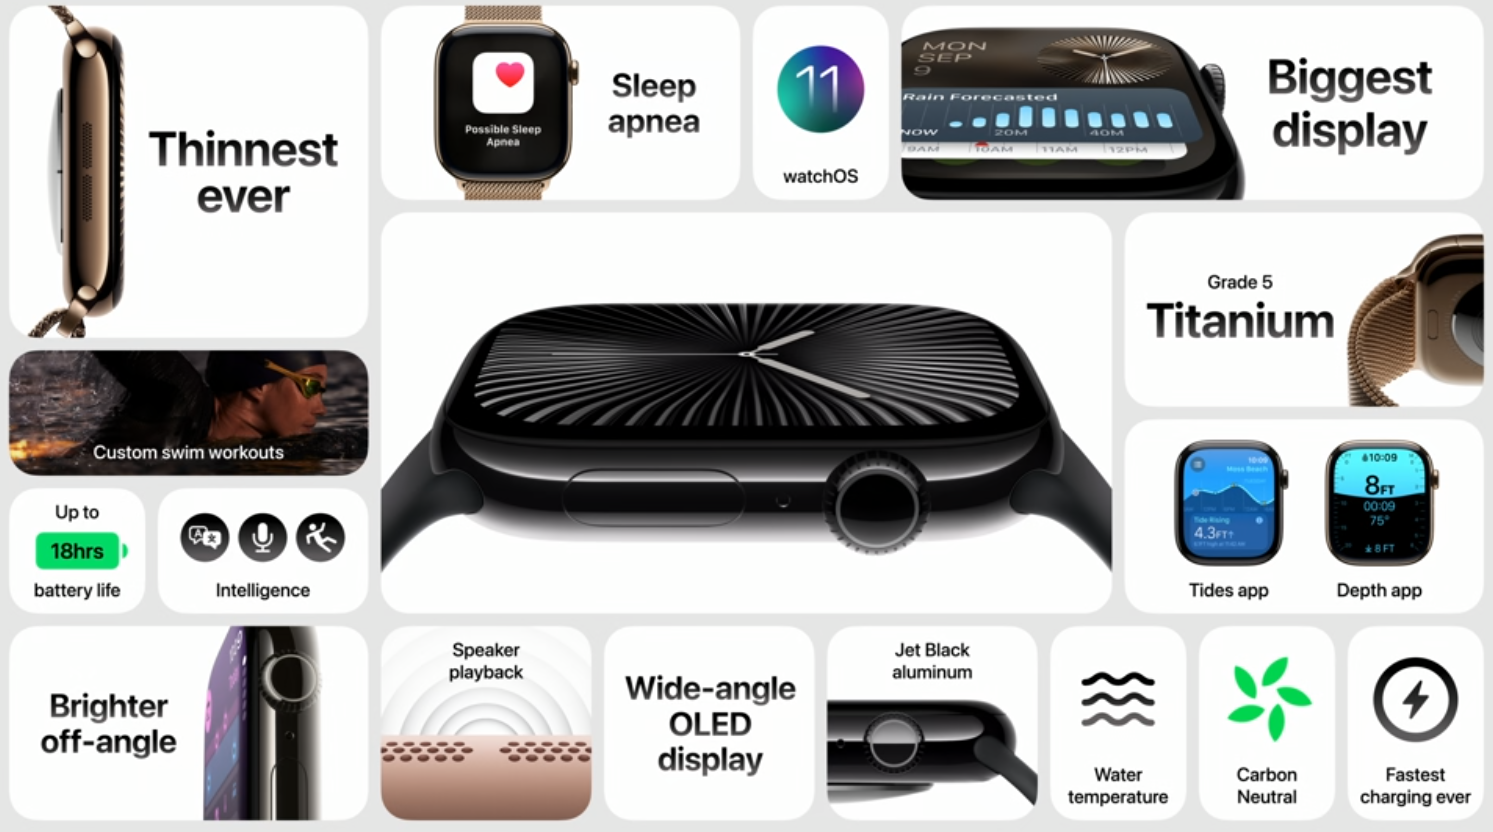
  • Apple Watch has new displays that are able to be viewed better at an angle.
  • Generative emoji creation. Not the most groundbreaking feature, but sticky for the base.
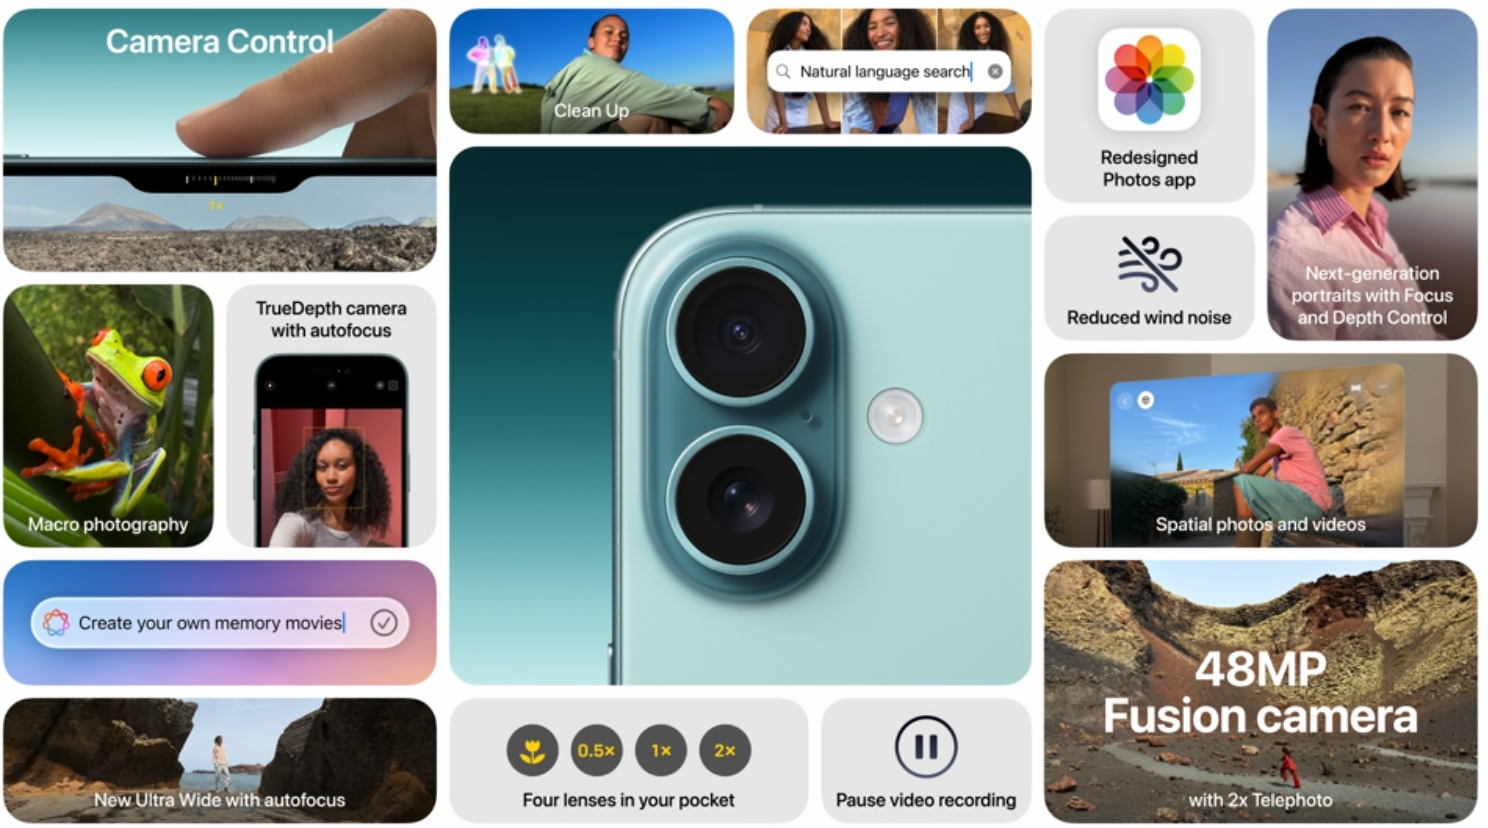
  • Camera control that has haptic features to enable framing of a shot, adjustments and access Visual Intelligence.
  • Spatial audio that will set Apple up for its Vision Pro ecosystem. Today, spatial audio will make mixing audio and video easier.
  • Satellite service on iPhone enhancements with roadside assistance, find device and other features across geographies.

Constellation Research CEO Ray Wang said the iPhone 16 cycle is a "significant release" that sets up "a super cycle of replacement that is shifting from 5G to AI." "We are halfway through the 5G cycle and the AI replacement cycle is driven by Apple Intelligence," said Wang. "We're seeing about 230 million iPhones a year replaced so year one for AI begins in 2025."

But innovation doesn’t necessarily pay Apple’s bills. What follows is a recap of the Apple iPhone 16 event by priority to the company's financials and most customers. Preorders start today on most products announced today with delivery Sept. 20. 

iPhone 16 Pro, A18 Pro

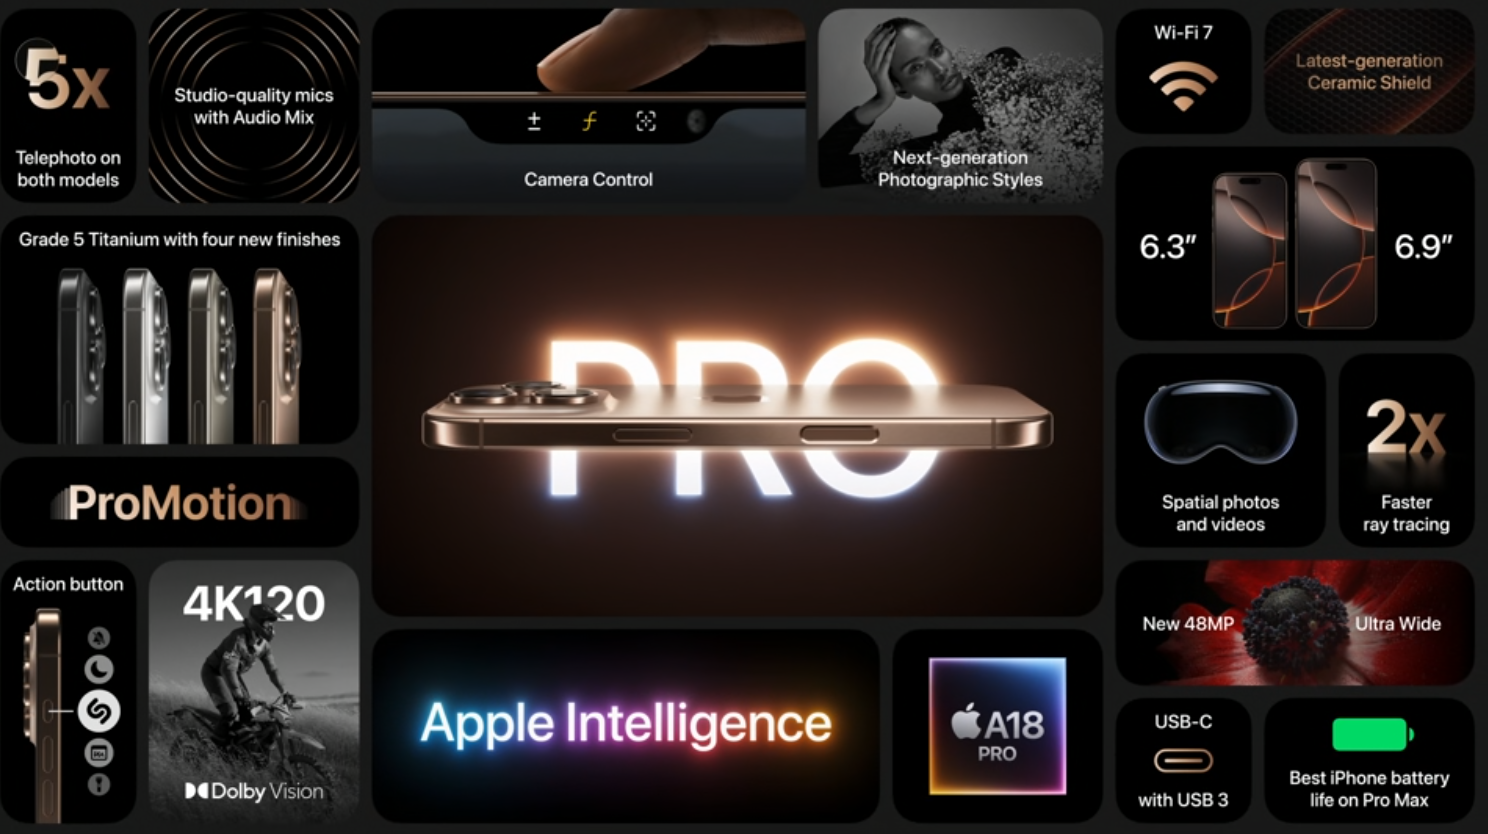
Apple CEO Tim Cook said the company's flagship has new enhancements including the largest displays at 6.3" and 6.7".

According to Apple, iPhone 16 Pro is designed for Apple Intelligence, leverages Siri for genAI tasks and personal semantic intelligence and provides suggestions for better photos. The device also has the longest battery life.

iPhone 16 Pro features A18 Pro, which is faster and more efficient than A18. It includes 3 nanometer technology, 16-core neural engine, 6-core CPU, 2x faster ray tracing, machine learning features, advanced media features, new image and video signal processors.

Spatial audio on iPhone 16 Pro will set Apple up for the future with Vision Pro, but today it will enable better audio and video mixing. Apple also added some fun features for voice memos.

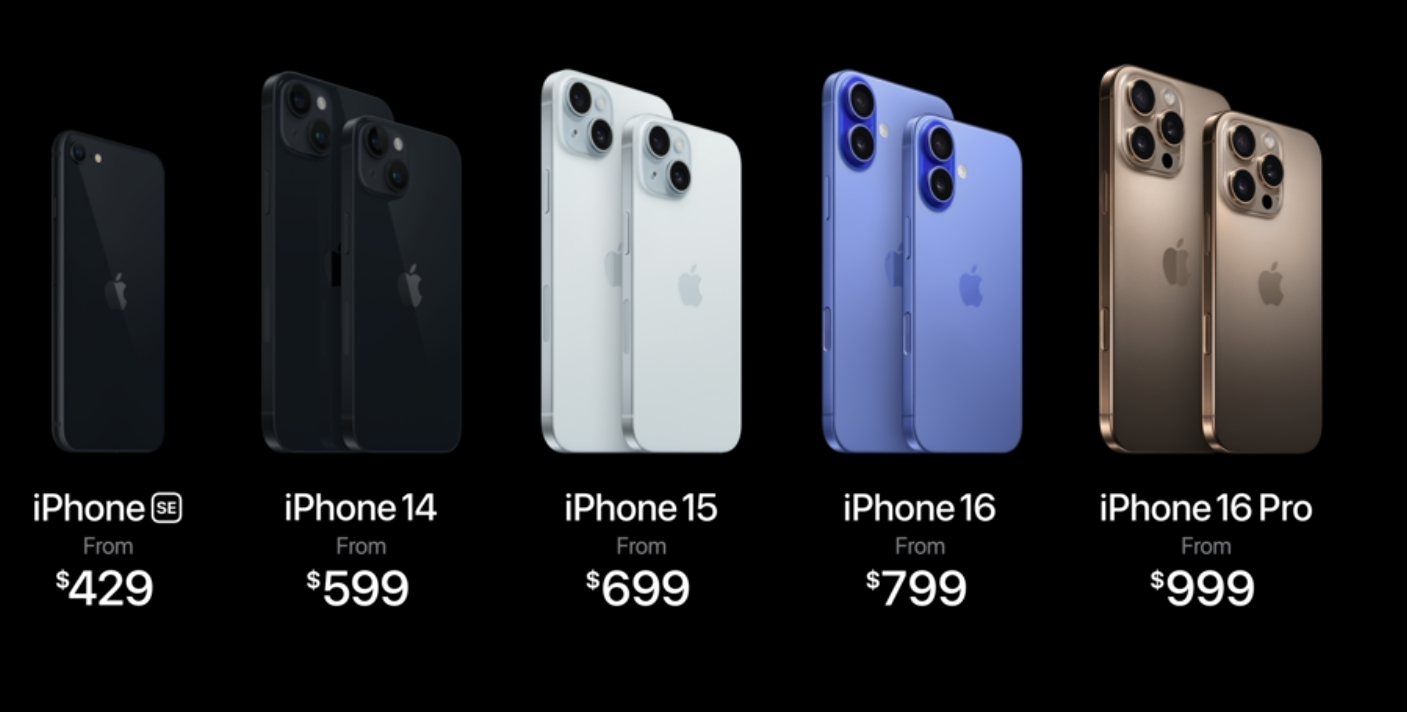
iPhone 16 Pro starts at $999.

iPhone 16, A18 and Apple Intelligence

Cook said the new iPhone has been designed from the ground up for Apple Intelligence, which isn't expected to fully roll out until 2025. iPhone 16 comes in 6.1" version and 6.7" version.

Biggest item in iPhone 16 is Apple Silicon for models, AI and machine learning. Apple launched A18 with 16-core neural engine, 16% more bandwidth to generative models, 3 nanometer technology, 6-core CPU and 30% more energy efficient. Apple A18 also includes a new GPU that uses 35% less power than A16.

Apple claimed that the A18 rivals high-end desktop processors.

The company touted Apple Intelligence integration throughout iPhone 16, but many features aren't expected to be available at launch. However, iOS will get writing tools, tone adjustment and proofreading. Apple Intelligence will be able to create new Emojis on the fly and new images.

Visual Intelligence will enable customers to take a picture and get contextual information for Google and ChatGPT data via iPhone 16's new camera control.

Next month, Apple Intelligence will be available for beta with a rollout in non-English languages next year. The upshot: Upgrade your phone and we'll give you Apple Intelligence later.

iPhone 16 starts at $799 and iPhone Plus starts at $899 and Apple said there are trade-in deals to be had.

Apple Watch

Apple Watch gets a larger screen, fast charging (80% charged in a 30 minutes), and wide-angle OLED display for brighter off-angle viewing. Apple claims that the screen size is now large enough to type on and 30% larger than Series 6 and bigger than the current Apple Watch Ultra.

Available Sept. 20 starting at $399.

Apple Watch Ultra 2

Apple Watch Ultra gets GPS enhancements, running zones and power meters for cycling as well as automatic stroke detection in swimming. Many of the features added to Apple Watch Ultra are already in Garmin watches.

Apple Watch Ultra 2 starts at $799.

Apple AirPods 4

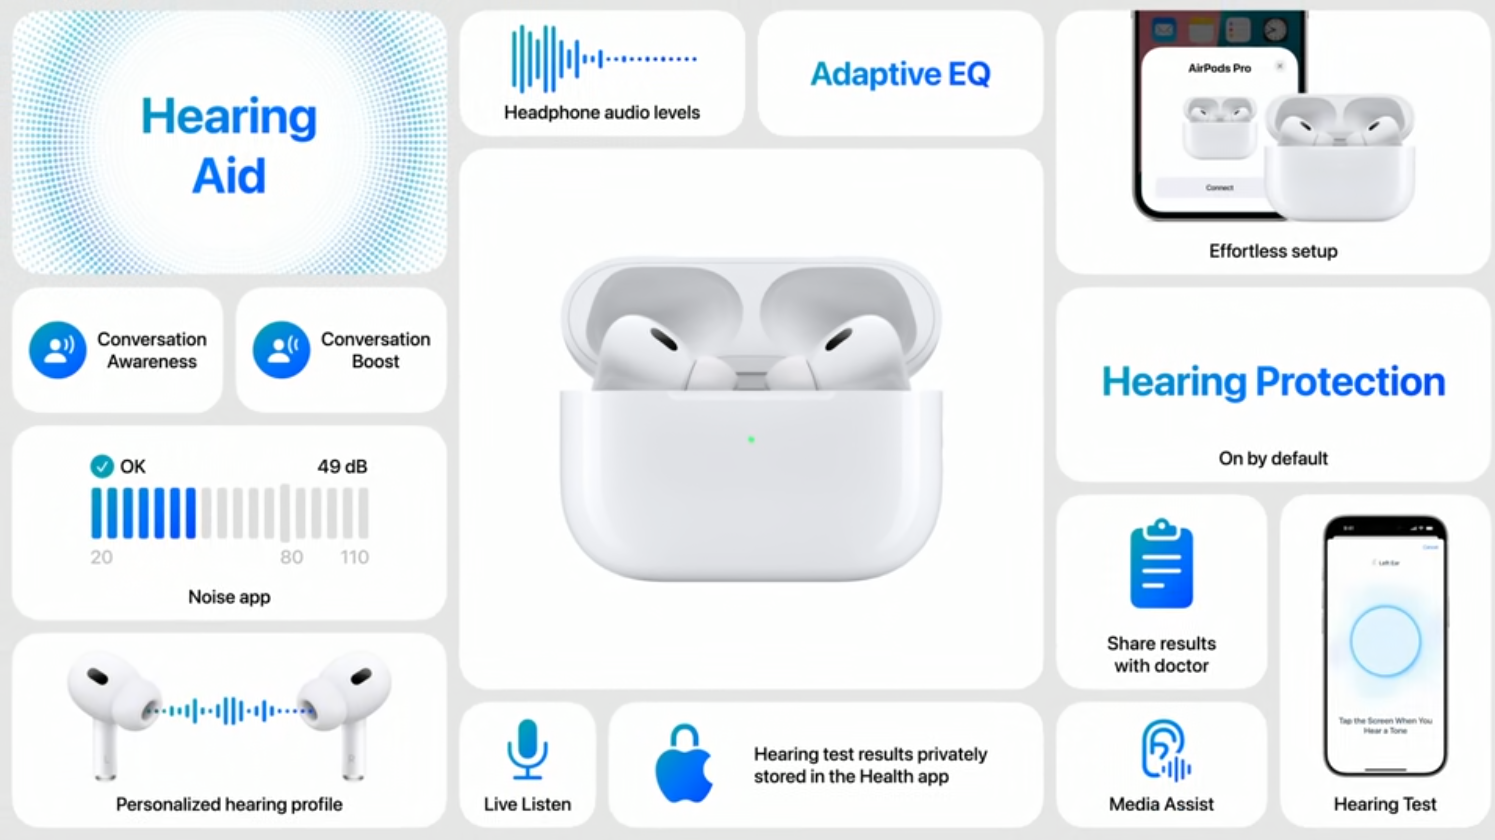
AirPods will enable you to respond to Siri with a simple yes or no nod. The charging case is USB C with 30 hours of total battery life. AirPods will get active noise cancellation for the first time as well as adaptive audio that adapts to environmental noise around you. Other items include conversational awareness, wireless charging to the case and transparency mode. Apple also updated AirPod Max headphones at $549.

AirPod Pro

AirPod Pro will include features to prevent hearing loss and boost awareness of the health issue. AirPod Pro will have hearing protection via machine learning while preserving audio range. AirPod Pro will also include hearing tests with an app on the iPhone based on data from the Apple Hearing Study and a hearing aid feature. Apple said that it expects FDA approval for its Hearing Aid feature soon and the feature will be delivered via a software update.

Data to Decisions Future of Work Innovation & Product-led Growth Next-Generation Customer Experience Tech Optimization Digital Safety, Privacy & Cybersecurity apple AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Executive Officer Chief Technology Officer Chief AI Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Product Officer

Enterprise security customers conundrum: Can you have both resilience, consolidation?

Enterprise security customers conundrum: Can you have both resilience, consolidation?

The parade of cybersecurity vendors looking to capitalize on the CrowdStrike and Microsoft outages has gone by, but it's unclear whether enterprises will be able to have both resiliency and vendor consolidation.

These conflicting goals are worth pondering as Microsoft meets with CrowdStrike and other security vendors Sept. 10 in Redmond.

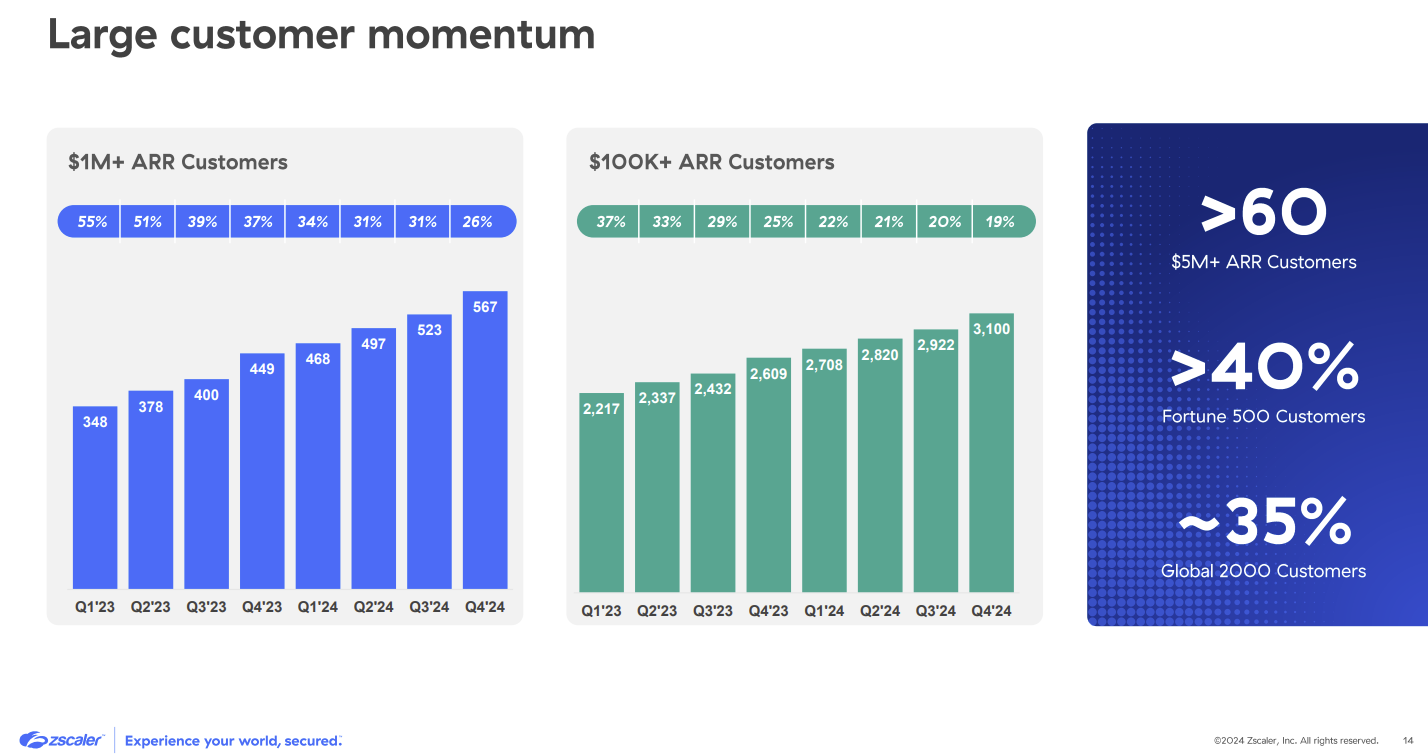
Zscaler CEO Jay Choudhury spent a lot of time talking about CrowdStrike's outage and the opportunities for his company. Those opportunities are compelling, but Zscaler cut its fiscal 2025 outlook as it overhauls its go-to-market and sales approach. Nevertheless, Choudhury had a lot of insights on what CIOs are thinking.

Speaking on Zscaler's fourth quarter earnings call, Choudhury said: "The importance of mission criticality has gone up significantly since the outage that was caused by CrowdStrike. While our customers want resilience, they also do want consolidation, but they do not want consolidation such that it makes them dependent on a single vendor."

In other words, enterprises are trying to thread a needle between consolidating security vendors and building resilience. Choudhury noted:

"Most of the CIO I talk to have been standardizing in-line access to three providers, one for EDR (endpoint detection and response), one for identity, and one for Zero Trust actions. I think that's a good combination because you end up getting a couple of extra layers, but you still have separation. So, in this environment, our customers aren't really pushing back on us because we tell them don't buy everything through Zscaler. You've got an EDR provider, you've got an identity provider and we'll do the rest of Zero Trust on activity."

Simply put, cybersecurity isn't likely to be the best-of-breed mashup it has been in recent years. Cybersecurity also isn't going to be this platformization nirvana that has been pitched by Palo Alto Networks. The reality is something in between and that means that CrowdStrike's moat around its business is largely intact.

This post first appeared in the Constellation Insight newsletter, which features bespoke content weekly and is brought to you by Hitachi Vantara.

A few themes that have emerged in the weeks since the CrowdStrike outage include:

Multiple vendors are capitalizing on the CrowdStrike outage. Zscaler noted increased interest, but SentinelOne had similar comments. SentinelOne CEO Tomer Weingarten said on the company's second quarter earnings call: "We've already seen customers choosing to move away (from CrowdStrike). Some of them have moved away already to SentinelOne, some of them are in the process, some of them will take time to assert, but I think everybody is considering their next steps. People are looking to diversify risk and not really concentrate more and more capabilities with one vendor."

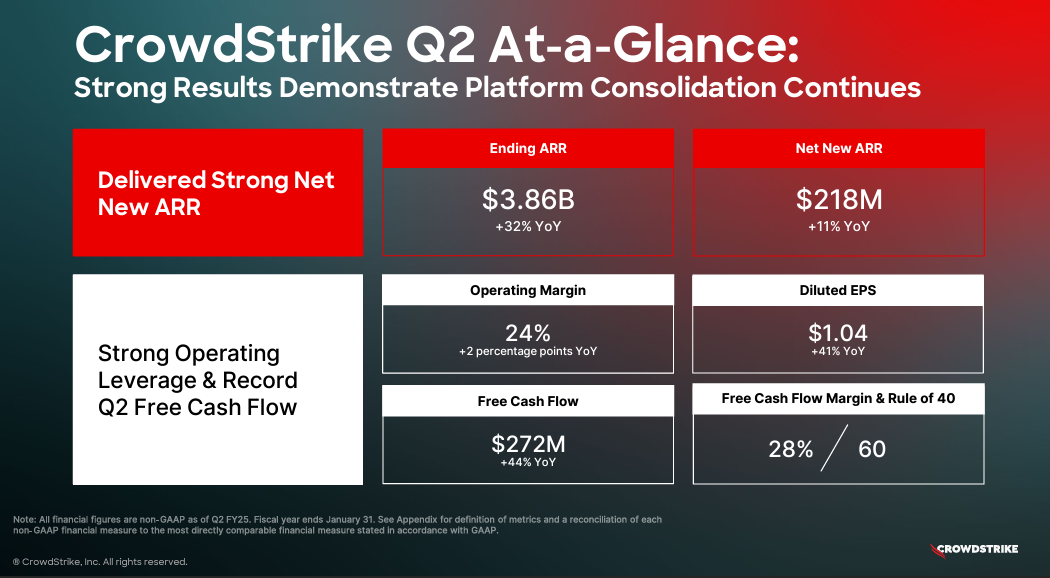
CrowdStrike will be fine and the outage will make the company better. Yes, CrowdStrike said it will take a subscription revenue hit for the remainder of its fiscal year due to its outage, but CEO George Kurtz said deals that were delayed during the July 19 outage remain in the pipeline. "Obviously, there's a lot of noise in the marketplace and we can only control what we can control, and I think the best way for me to articulate that is to just recount some of the conversations. I had two customer calls this morning and most of them start out the same. They talk about our response, how transparent we were, and how we dealt with the problem. We talked about some of the mitigating steps that we've taken and it generally ends with we want to do more with CrowdStrike."

Platformization is still a theme for enterprises. Palo Alto Networks CEO Nikesh Arora said his company's platformization play is resonating with enterprises. Palo Alto Networks delivered a strong fourth quarter and Arora steered his comments toward the intersection of AI and cybersecurity with a brief mention of CrowdStrike's outage. He did say that customers are asking about resiliency and update procedures. Palo Alto Networks also closed its acquisition of IBM’s QRadar SaaS business.

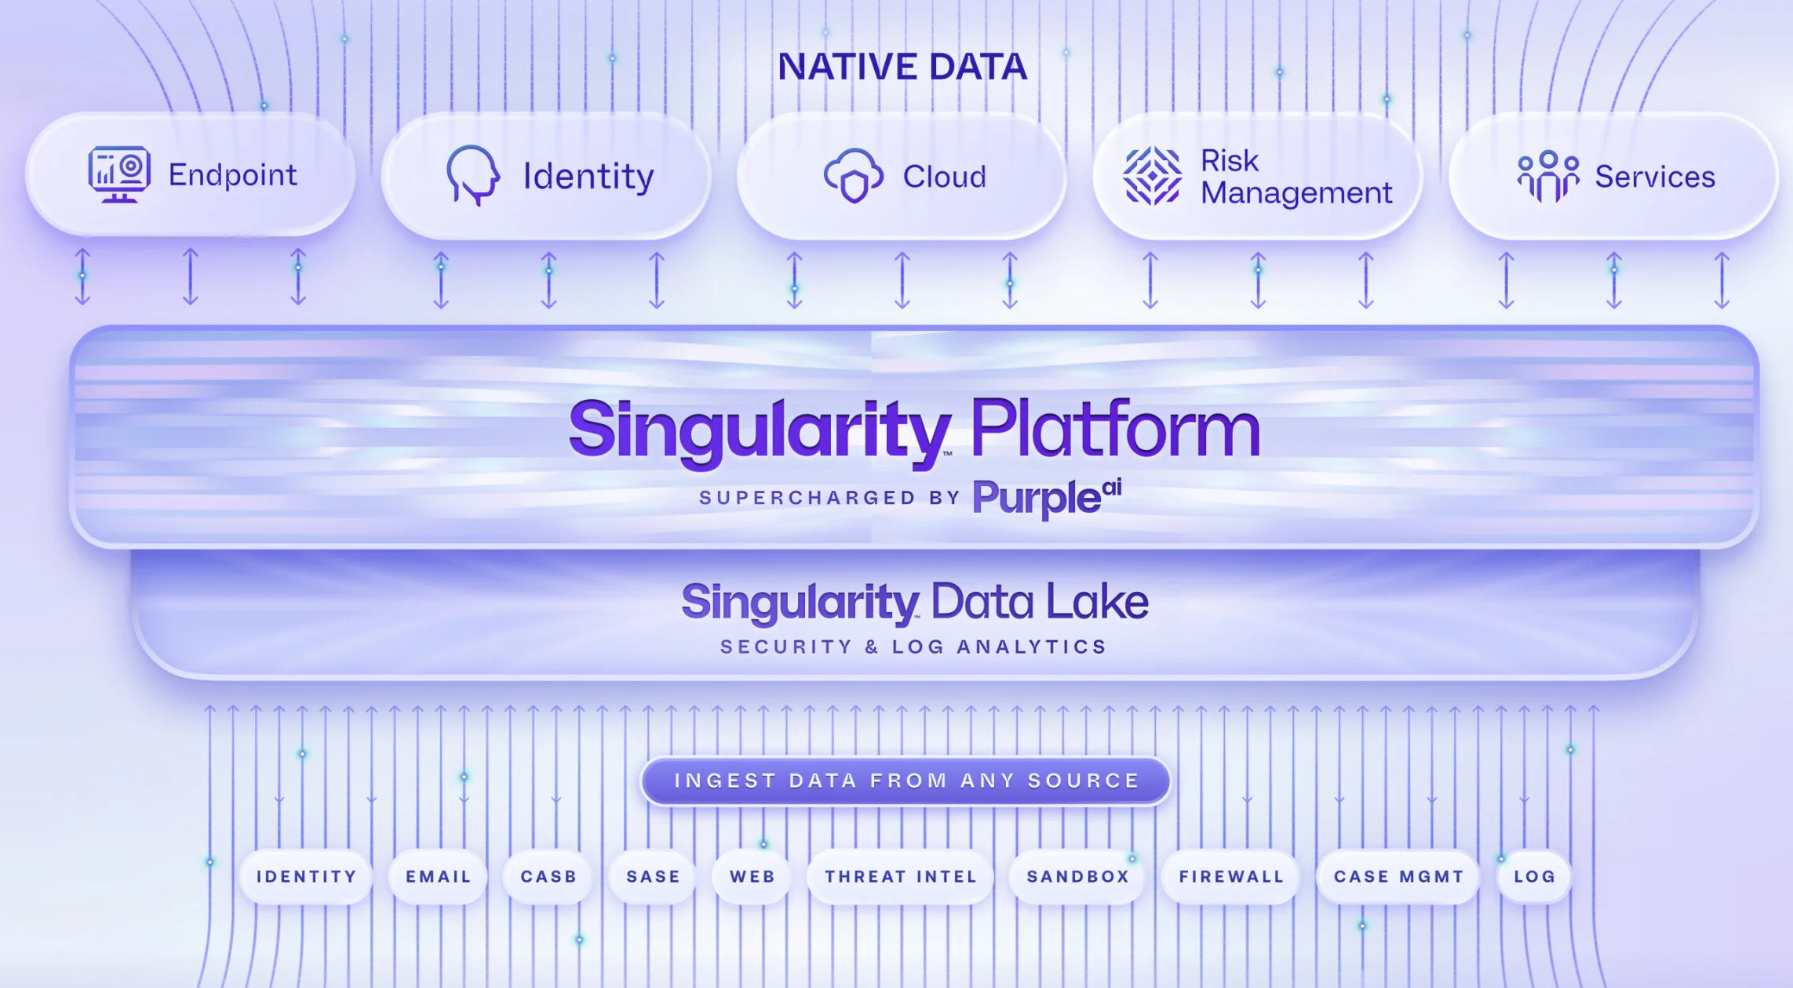
Enterprises will look to multiple platforms based on cybersecurity roles. It's likely that larger cybersecurity vendors are going to gobble up smaller players to build out platforms. Fortinet is one example as it has acquired its way to becoming more of a platform that resembles Palo Alto Networks. Also look for Google Cloud to make some more cybersecurity moves. Google Cloud recently partnered with Rubrik on data protection via integration with Mandiant and was reportedly in talks to buy cloud security startup Wiz.

We’ll leave you with the ShortLists you need to know:

Insights Archive


Digital Safety, Privacy & Cybersecurity I am Team Leader at the Nominee Organization (no vendor self nominations) Distillation Aftershots Security Zero Trust Chief Information Officer Chief Information Security Officer Chief Privacy Officer

HOT TAKE: Salesforce Furthers Autonomous AI Agent Development with xGen Concept & Tenyx Buy

HOT TAKE: Salesforce Furthers Autonomous AI Agent Development with xGen Concept & Tenyx Buy

Late last month Salesforce announced its first AI-powered agents, addressing business development and sales coaching use cases. Fast on that news is the release of new proprietary AI models, under the xGen moniker. These are essentially new libraries of large language models (LLMs) designed for generative text use cases supporting CRM processes. Think email and web content creation, document summaries, etc. 

The latest xGen release is xGen sales, which the company says is “a proprietary model trained and designed to power autonomous sales tasks with Agentforce, and xLAM, a new family of Large Action Models designed to handle complex tasks and generate actionable outputs.” In short, Salesforce is full steam ahead in entering the “autonomous” phase of AI development, at least on paper. Its pre-packaged SDR and sales coaching AI agents are a safe, and solid choice for a first foray - but now the company is opening up the tool set to allow customers and parters to build more autonomous and action-oriented use cases for AI virtual agents. 

It is a smart move. Putting both the onus on the customer and the partner to figure out the last mile of AI agent development allows for a wider proliferation of use cases, and also keeps Salesforce off the hook in some ways (but not all) when it comes to compliance and security. 

These new AI agent tools will get a boost in the near future, now that Salesforce has announced its plans to acquire Tenyx, a developer of AI-powered voice agents. The deal is expected to close by the end of October, and the company says Tenyx’s technology will enable innovation inside its AI agent offerings (yet to be GA) around customer service and support use cases. The AI voice agent technology can quickly augment chatbot and other AI multi-channel tools by offering more intuitive and actionable virtual agent experiences, where these agents can make more decisions and be injected into more workflows to complete more tasks to drive productivity, time to resolution, etc. 

As always, current Salesforce users should carefully inspect and evaluate these new LLMs and LAM offerings. Both for compliance and security, but also for alignment in terms of use case and expected business outcomes. The old adage “just because you can, does not mean you should” comes to mind this early in the development of these new AI agents. In short, proceed with optimistic caution. 

Next-Generation Customer Experience Data to Decisions Future of Work Innovation & Product-led Growth New C-Suite Marketing Transformation I am Team Leader at the Nominee Organization (no vendor self nominations) Distillation Aftershots Tech Optimization Digital Safety, Privacy & Cybersecurity ML Machine Learning LLMs Agentic AI Generative AI AI Analytics Automation business Marketing SaaS PaaS IaaS Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP finance Healthcare Customer Service Content Management Collaboration Chief Revenue Officer Chief Executive Officer Chief Information Officer Chief Technology Officer Chief AI Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Product Officer

UiPath: Process automation orchestration core of AI agent deployments

UiPath: Process automation orchestration core of AI agent deployments

UiPath's second quarter results indicate that enterprises are starting to realize that genAI-powered agents will require orchestration and process automation at the core.

The company, known for its robot process automation roots and automation platform, stabilized in the second quarter following a volatile first quarter that included the departure of CEO Rob Enslin.

Although UiPath's second quarter was better-than-expected, the big question about the company remains. Where does UiPath fit in the AI agent, generative AI and automation mix. An analyst asked UiPath CEO Daniel Dines where the company fits in the AI landscape. Here's what Dines said:

"We really think of an agentic process automation as an evolution of robotic process automation, I actually we started to socialize the agentic process automation term at the beginning of the summer. And we introduced the concept of robots and agents working together. And to me, an AI agent is basically a robot, if you want, that has some more new skills. And I think there will be multiple type of agents.

For instance, there will be agents that are capable of extracting information from long and complex documents. And users, human users will be capable of interacting with these agents asking questions. And in turn, they can ask the agents to perform actions for them. There will be agents that can make more intelligent decisions based on data, and they can route a process in a more dynamic way. Robotic means that the series, the steps in the process are stitched together in a fixed way. And agentic workflow might have dynamic routine as part of the process.

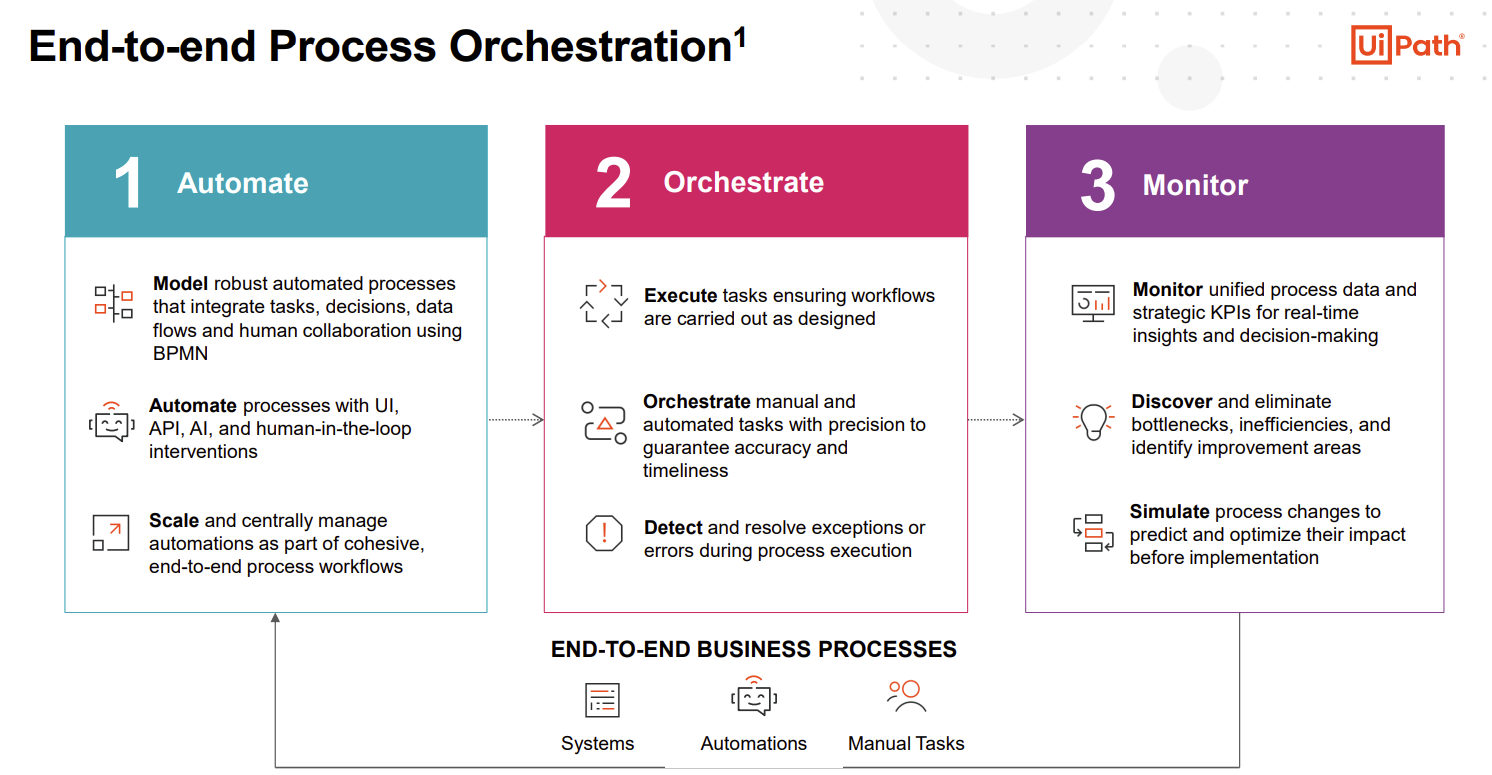
Our strength is in combining robotic automation with agentic automation as part of our process orchestration platform. The differentiator in customers deploying agents will be in how well they are integrated within the business platform and how well we can orchestrate between robots, agents and humans."

That excerpt is a mouthful, but may indicate how AI and automation discussions are maturing. Ashim Gupta, CFO and COO, noted that customers are "seeing the linkages between AI and automation" and the company is seeing clarity on enterprises and how they're focused on returns on investment in an uncertain economy.

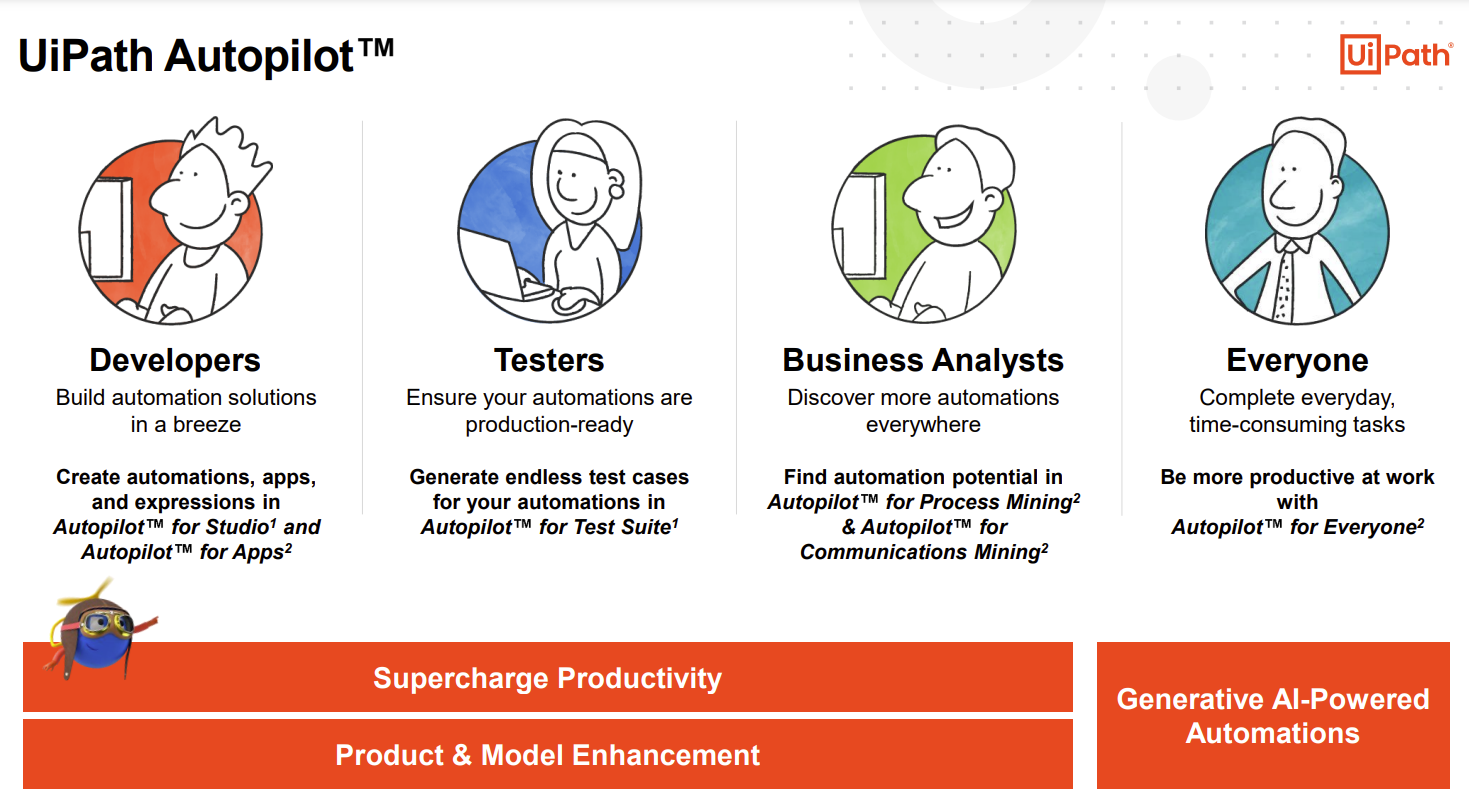
Dines said UiPath's AutoPilot will be generally available soon with communications mining and process orchestration. He added that the company may feature "quite a different model that should tie our pricing more to the value that we deliver." Dines added that's it's too early to comment, but value driven by the UiPath platform.

In addition, UiPath has an internal initiative called "Unify build type" that will create a platform that has an integrated experience across roles. UiPath customers are increasingly adopting its full automation platform that includes document understanding and processing as well as RPA. Dines said:

"An enterprise will have maybe 100s and 1,000s of agents over time. It's equally important to orchestrate these agents, manage them, offer them in a secure and governed environment. We spent many years to build a scalable orchestration platform. We are just taking the best of LLM work, embedding it into our platform and delivering it to our customers.

Our platform emulates human users. That's the core tenet of what we are building. It's a natural extension from RPA to broader automation to an AI-powered automation platform."

Q3 outlook, Q2 numbers

UiPath's third quarter outlook was in line with expectations and the fiscal year view was better than expected. UiPath forecasted third quarter revenue of $345 million and $350 million compared to estimates of $347.5 million. For fiscal 2025, UiPath said revenue will be between $1.42 billion and $1.425 billion compared to estimates of $1.41 billion.

In the second quarter, UiPath reported non-GAAP earnings of 4 cents a share, a penny better than estimates, on revenue of $316 million, up 10% from a year ago. Wall Street was expecting revenue of $303.74 million.

UiPath's net loss for the second quarter was $85.1 million, or 15 cents a share.

By the numbers:

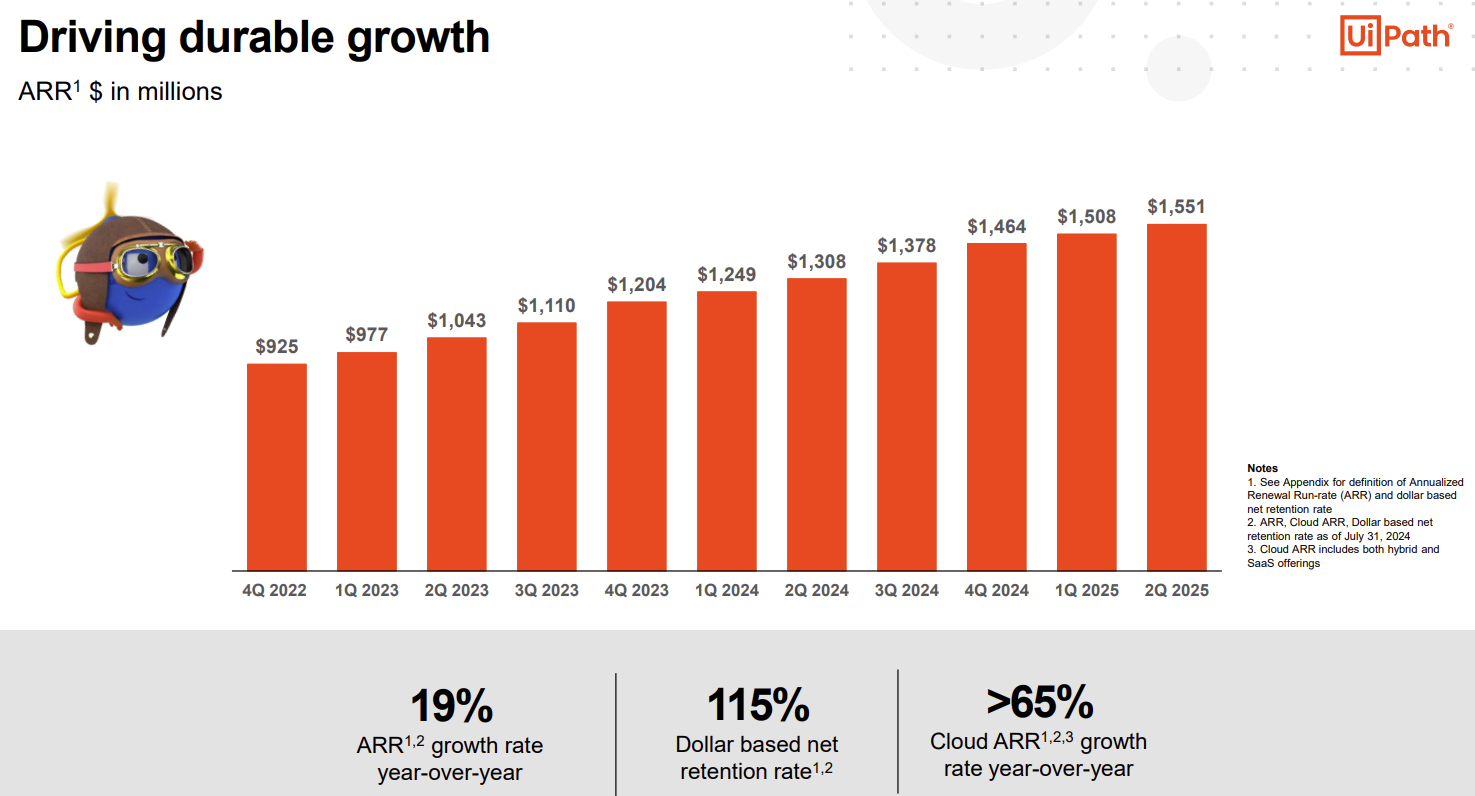
  • UiPath ARR in the second quarter was $1.55 billion, up 19% from a year ago.
  • UiPath had 2,163 customers with more than $100,000 in ARR.
  • There were 293 customers with ARR of more than $1 million.

Data to Decisions Future of Work Innovation & Product-led Growth Tech Optimization Next-Generation Customer Experience Digital Safety, Privacy & Cybersecurity AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Executive Officer Chief Technology Officer Chief AI Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Product Officer

Salesforce's acquisition of Own highlights small ball approach to M&A

Salesforce's acquisition of Own highlights small ball approach to M&A

Salesforce's purchase of Own Company for $1.9 billion highlights how the company has to play small ball with mergers and acquisitions given the scrutiny it gets with big deals. But keep in mind that small acquisitions such as Airkit.ai, which powered Salesforce’s Agentforce strategy, can have bigger impact.

The CRM giant said it will acquire Own Company, which provides data protection and management software, for $1.9 billion. Salesforce already owned 10% of Own Company. Memo to any future entrepreneur: Don't name your company Own if you want to be acquired because the headline gets wonky.

Own Company will plug into Salesforce's platform as part of the data protection and loss prevention offering. What is most notable is that Salesforce had to say that the $1.9 billion purchase "will not impact Salesforce's capital return program."

Yes folks, we're a long way from the heady days where Salesforce would blow $27.7 billion on Slack. Consider the following acquisitions since activist investors targeted Salesforce:

2022:

  • Troops.ai provided applications that enhanced revenue ops collaboration and visibility.
  • Phennecs for privacy and compliance.

2023:

  • Airkit.ai, which specialized in AI-powered customer service experiences.
  • Spiff, a company that has a commission management platform.

2024:

  • PredictSpring, an existing Salesforce ecosystem partner.
  • Tenyx, a developer of AI-powered voice agents.
  • Own Company.

Now aside from Salesforce's reported interest in Informatica in 2024, the company is showing some serious M&A restraint.

Small ball works and Airkit.ai proves it

As someone who happens to like writing about large deals that may (or may not) work out, I miss the old big spending Salesforce. However, small ball works out well.

In fact, small mergers can transform a company without much risk. Airkit.ai is an example and Constellation Research analyst Liz Miller saw the impact early. Miller wrote last year:

"The Airkit.ai use case goes far beyond a familiar customer service or contact center storylines as Salesforce dives into industry-specific bots that are proactive and contextual to a customer or employee's journey...

With Data Cloud in place and the addition of the Einstein Platform and Einstein Studio on top of the Salesforce Platform, the company is now ready to supercharge their customer’s capacity to not just deliver results through AI-powered bots, but have the actual data and AI infrastructure in place to ensure that sales and service teams can safely, quickly and easily deploy digital cross-channel assistants."

Yep, Liz called it.

Salesforce has pivoted the entire company on AI agents and Agentforce. On Salesforce’s second quarter earnings call, Benioff said “Agentforce” 26 times. Dreamforce will be the coming out party for Agentforce, genAI-powered agents that will leverage the entire Salesforce platform.

Benioff said:

"This is really the future, a new future that we can really envision, and with this Agentforce platform, we're making it easy to build these powerful autonomous agents for sales, for service, for marketing, for commerce, automating the entire workflow on their own, embedding agents in the flow of work and getting our customers to the agent future first. And this is our primary goal of our company right now. This is my singular focus."

Simply put, Agentforce is Airkit.ai scaled across the Salesforce platform.

Salesforce in recent years has laid the groundwork with Data Cloud and other parts. Salesforce created a core for all of its clouds, put Data Cloud in the center and then created the AI model pathways for enterprises. Agentforce (Airkit.ai) is the front-end.

In the end, the Airkit.ai purchase may be as critical to Salesforce as MuleSoft, the chassis that connects everything. Should Agentforce reinvent Salesforce, Airkit.ai may be its best acquisition of the bunch. Small ball may lack the excitement, but strategically has better returns.

Data to Decisions Innovation & Product-led Growth Marketing Transformation Matrix Commerce Next-Generation Customer Experience Future of Work Tech Optimization Digital Safety, Privacy & Cybersecurity salesforce AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Marketing Officer Chief Revenue Officer Chief Data Officer Chief Executive Officer Chief Technology Officer Chief AI Officer Chief Analytics Officer Chief Information Security Officer Chief Product Officer

Broadcom reports strong Q3, but Q4 revenue outlook light

Broadcom reports strong Q3, but Q4 revenue outlook light

Broadcom reported better-than-expected third quarter results as revenue growth was driven by Ethernet networking and custom accelerators for AI data centers. The fourth quarter outlook, however, was a bit light. 

The company reported a third-quarter net loss of $1.87 billion, or 40 cents a share, on revenue of $13.07 billion, up 47%. Non-GAAP earnings in the third quarter were $1.24 a share.

Wall Street as expecting Broadcom to report earnings of $1.21 a share on revenue of $12.96 billion.

CEO Hock Tan said the quarter reflected “continued strength in our AI semiconductor solutions and VMware.” Revenue from AI will be $12 billion for the fiscal year due to networking and custom AI accelerators. “The integration of VMware is driving adjusted EBITDA margin to 64% of revenue as we exit fiscal year 2024,” said Tan.

Going into the results, analysts were mostly interested in Broadcom as an AI play. However, AI infrastructure players such as Nvidia and chipmakers like AMD have tailed off of late. VMware integration was also a hot topic as Tan addressed VMware customers directly. “You're telling us you want our products to work better and be more user friendly. You want them to work together. You're asking us--me particularly--to roll up your sleeves and do the hard work. That's exactly what we've done,” said Tan.

VMware is facing the heat from customers and competitors such as Nutanix. Rajiv Ramaswami, CEO of Nutanix, said: "The VMware acquisition continues to be positive for Broadcom shareholders, but at what expense to VMware customers? Higher prices, support changes, lack of innovation - it all adds up to a genuinely frustrating experience for customers, and in the end, effectively cutting VMware –a one-time enterprise leader–out at the knees."

By unit, Broadcom semiconductor revenue was $7.27 billion, up 56% from a year ago. Infrastructure software revenue was $5.8 billion, up 200% from a year ago due to the VMware purchase. In the third quarter, software revenue was 44% of the total pie, up from 22% a year ago.

As for the outlook, Broadcom projected fourth-quarter revenue of $14 billion with adjusted EBITDA of about 64%. Wall Street was expecting revenue of $14.13 billion in the fourth quarter. 

Here's what Tan said on Broadcom's earnings conference call:

  • "We booked more than 15 million CPU costs of VCF (VMware Cloud Foundation), representing over 80% of the total VMware products we booked during the quarter. And this translates into an annualized booking value, or ABV as I had described before, of $2.5 billion during Q3, up 32% from the preceding quarter. Meanwhile, we continue to drive down costs in VMware. We brought VMware spending down to $1.3 million in Q3 from $1.6 million in Q2."
  • "Our hyperscale customers continue to scale up and scale out their AI clusters. Custom AI accelerators grew 3.5 times year-on-year."
  • "We do not focus very much on enterprise AI market as you know well. Our products in AI are largely, very much largely focused, especially on the AI accelerator or XPU side, but even -- also just as much on networking side, on hyperscalers, on cloud, those three large platform and some digital natives, what you call, big guys. We don’t deal very much on AI with enterprise."
  • "The VMware business continues to book very well, as we convert our customers very much in two ways, one, from perpetual to a subscription license, but also those subscription license for the full stack of VCF. And that has been very successful."
Data to Decisions Tech Optimization vmware Chief Information Officer

Scotts Miracle-Gro and UserTesting: 9 customer experience takeaways

Scotts Miracle-Gro and UserTesting: 9 customer experience takeaways

Scotts Miracle-Gro is focused on a three-year strategy aimed at driving 3% annual growth by expanding its retail presence and growing its direct-to-consumer (DTC) channels.

Constellation Research analyst Liz Miller recently caught up with Scotts Miracle-Gro leaders Hailey Schraer, lead user experience researcher at Scotts Miracle-Gro, and Jess Bailey, senior manager of digital experience at Scotts Miracle-Gro, to talk customer experience (CX). I followed up with a look at how those Scotts Miracle-Gro efforts align to the broader corporate strategy laid out by CEO Jim Hagedorn.

Scotts Miracle-Gro: How CX and UserTesting Drive Omnichannel Revenue
Here's a look at the takeaways:

  1. CX is critical: CX plays a vital role in driving omnichannel revenue and continuous testing is the path to success. Scotts Miracle-Gro emphasizes building consumer confidence through education and content, which leads to increased purchase likelihood and repeat visits.
  2. Real-time feedback's role: Scotts Miracle-Gro uses UserTesting to capture customer feedback in real-time. UserTesting enables continuous optimization of user experience (UX) by identifying pain points and improving interfaces based on consumer reactions.
  3. Data drives decision-making: The integration of feedback loops, A/B testing, and analytics allows Scotts Miracle-Gro to make data-driven decisions, optimizing content, and improving conversion rates. UX and CX teams work collaborate to enhance the consumer's path to purchase.
  4. Efficiency and ROI through CX: Leveraging UserTesting has resulted in measurable benefits, including a 33% increase in webpage views, 60% faster project completion, and a 477% projected ROI due to CX improvements.
  5. Conversion through education: Scotts Miracle-Gro focuses on educating consumers about lawn and garden care across its digital platforms. The approach builds consumer confidence, enhances engagement and drives conversions directly to Scotts Miracle-Gro or retail partners.
  6. Omnichannel connective tissue: By combining efforts across sales, marketing, and supply chain, Scotts Miracle-Gro ensures consistency in CX and aligns with business goals. Retail partnerships are enhanced through joint marketing efforts, which drive traffic both in-store and online.
  7. Aligning CX metrics: Key metrics such as engagement, brand perception, and overall brand health are tracked across channels. These metrics guide the broader business objectives, ensuring that CX initiatives directly impact sales and revenue growth.
  8. Agility: Scotts Miracle-Gro can turn around user studies in less than 24 hours, enabling a responsive and agile approach to customer feedback. Insights from UserTesting are shared across teams so they can influence strategic decisions at the executive level.
  9. Managing seasonality and promotions: The company’s sales strategies are highly influenced by planting seasons, with spring being their most critical period. Promotional activities and CX during key retail times are crucial for driving sales and negotiating retailer partnerships.

Data to Decisions Matrix Commerce Next-Generation Customer Experience Innovation & Product-led Growth Future of Work Tech Optimization Digital Safety, Privacy & Cybersecurity ML Machine Learning LLMs Agentic AI Generative AI AI Analytics Automation business Marketing SaaS PaaS IaaS Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP finance Healthcare Customer Service Content Management Collaboration Chief Marketing Officer Chief Revenue Officer Chief Analytics Officer Chief Data Officer Chief Executive Officer Chief Information Officer Chief Technology Officer Chief AI Officer Chief Information Security Officer Chief Product Officer

C3 AI Q1 solid, outlook slightly light

C3 AI Q1 solid, outlook slightly light

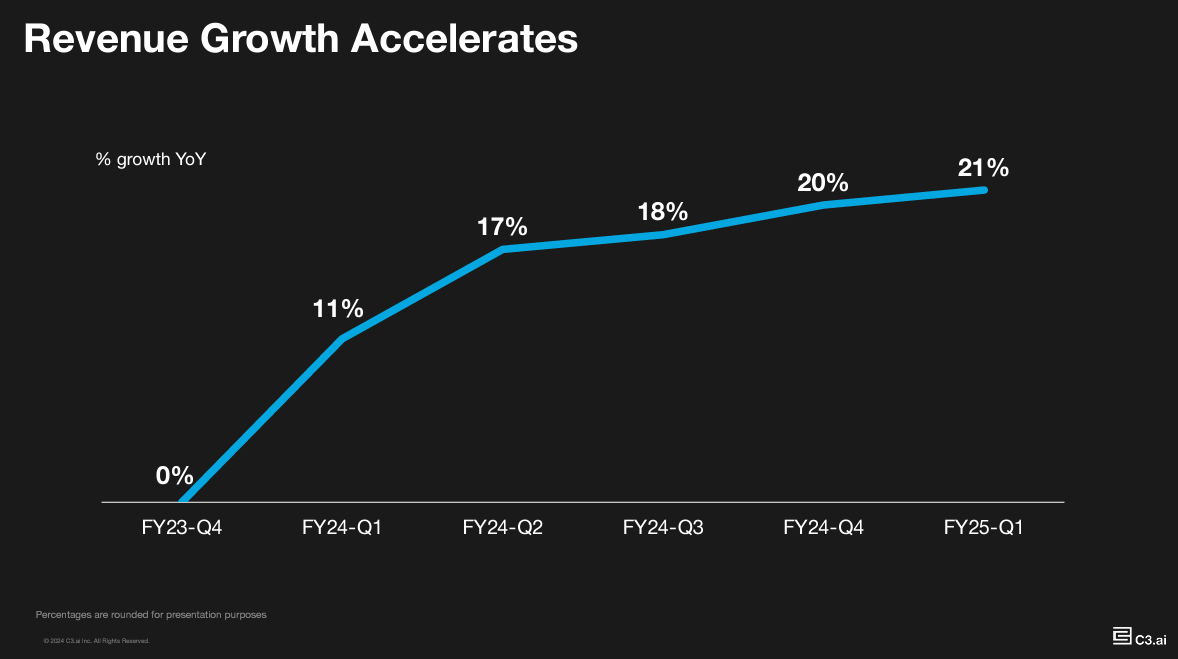
C3 AI's revenue growth in its first quarter checked in at 21% as the company continued to land enterprise use cases. C3 AI's outlook for the second quarter was light.

The company reported a first quarter net loss of 50 cents a share on revenue of $87.2 million, up 21% from a year ago. Non-GAAP loss for the quarter was 5 cents a share. Subscription revenue was 84% of total revenue. 

Wall Street was expecting C3 AI to report a fiscal first quarter loss of 13 cents a share on revenue of $86.94.

As for the outlook, C3 AI projected second-quarter revenue of $88.6 million to $93.6 million with a non-GAAP loss from operations of $26.7 million to $34.7 million. Wall Street was expecting second quarter revenue of $91.3 million. For the fiscal year, C3 AI projected revenue between $370 million to $395 million with the midpoint slightly below estimates of $383.9 million.

Speaking on the earnings call, CEO Tom Siebel said:

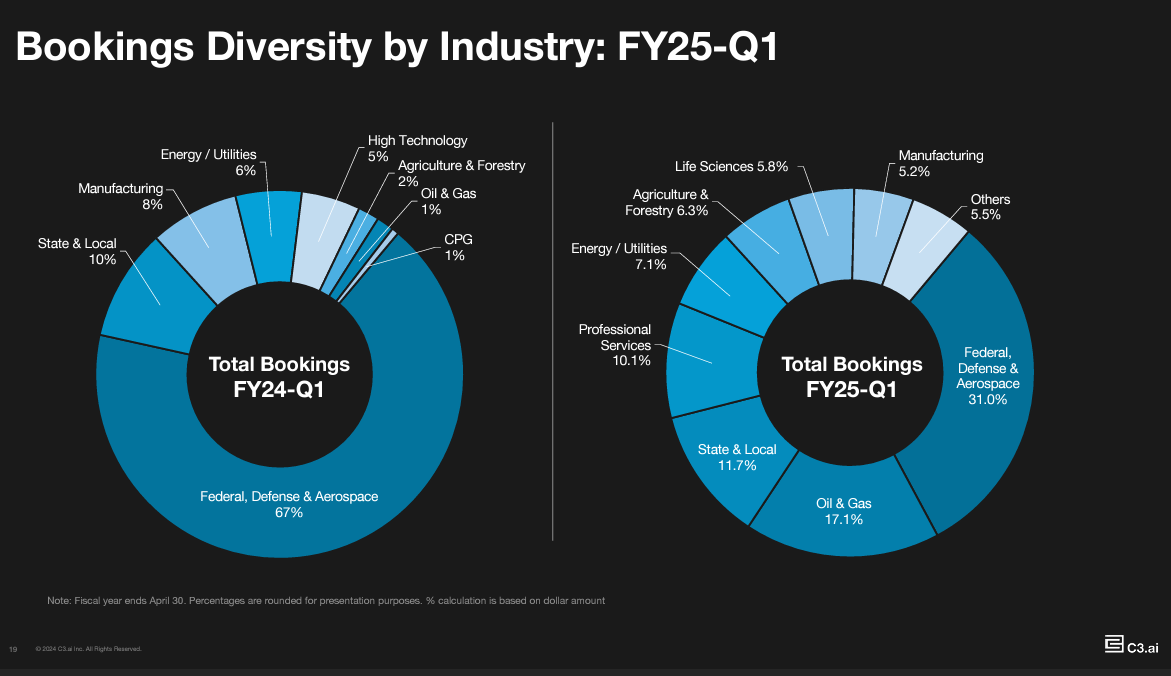
"C3 AI's customer base continues to expand, both within and across industries, while maintaining exceptional levels of customer satisfaction by by our continued focus on delivering measurable, significant enterprise value. Our bookings continue to be increasingly diverse. Our generative AI business is surprisingly diverse, with many candidly unanticipated use cases across the board in a wide range of industries."

By the numbers:

  • C3 AI closed 71 agreements in the first quarter including 52 pilots.
  • The company closed 25 agreements with municipal, county and state agents.
  • C3 AI’s federal business was 30% of bookings in the first quarter.
  • Electrobras, US Marine Corps. And Nucor were among the named customer additions.
  • Partners represented 72% of total agreements in the first quarter and Google Cloud and C3 closed 40 deals.
  • C3 AI closed 17 C3 AI Generative AI pilots in the quarter.
Data to Decisions Innovation & Product-led Growth Future of Work Tech Optimization Next-Generation Customer Experience Digital Safety, Privacy & Cybersecurity AI GenerativeAI ML Machine Learning LLMs Agentic AI Analytics Automation Disruptive Technology Chief Information Officer Chief Executive Officer Chief Technology Officer Chief AI Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Product Officer

HPE posts Q3 revenue growth on AI systems

HPE posts Q3 revenue growth on AI systems

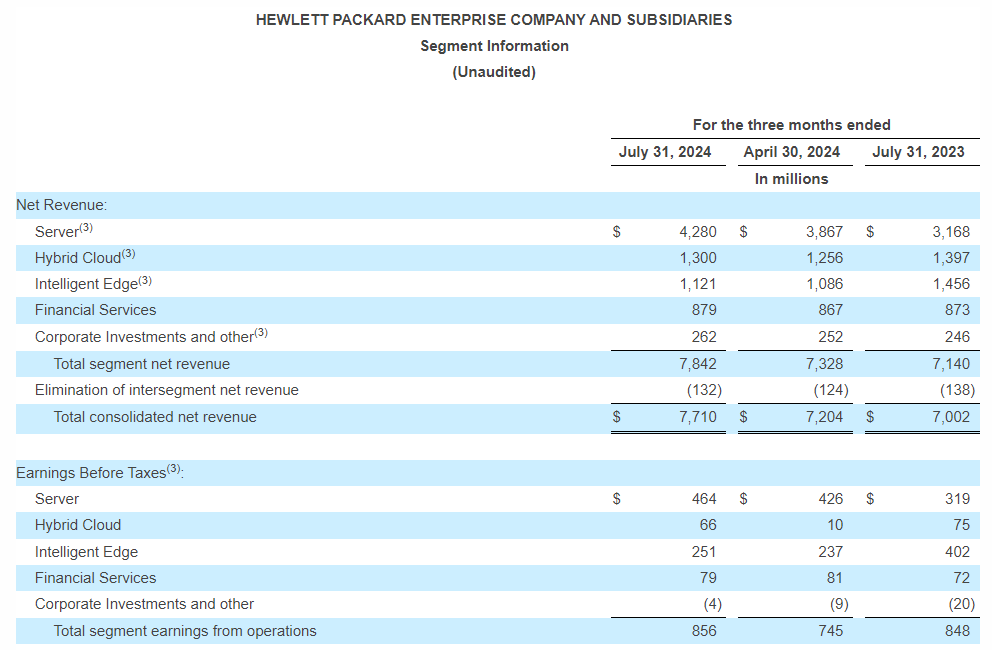
Hewlett Packard Enterprise said its third quarter was driven by AI systems as revenue was up 10% from a year ago.

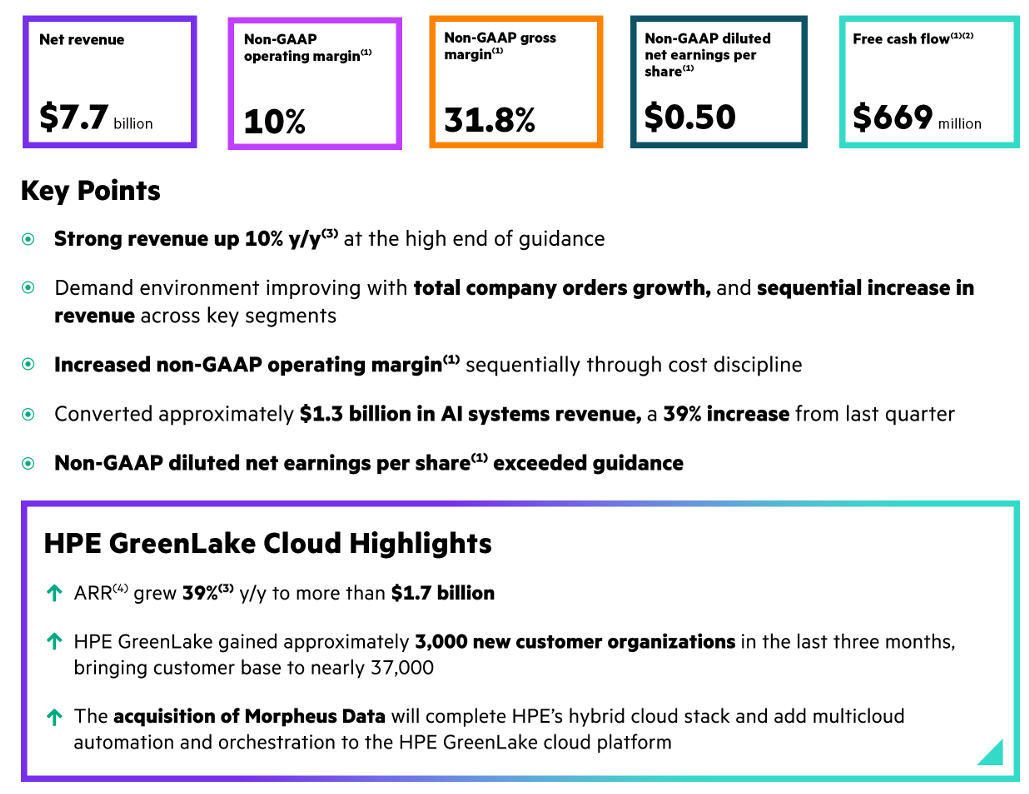
The company reported third quarter net income of 38 cents a share on revenue of $7.7 billion, up 10% from a year ago. Non-GAAP earnings in the quarter were 50 cents a share.

Wall Street was expecting HPE to report third quarter earnings of 47 cents a share on revenue of $7.66 billion.

CEO Antonio Neri said the third quarter was strong with growth due to AI system sales. HPE noted that it was well positioned to gain market share in AI infrastructure.

In a blog post, Neri noted:

"Our AI leadership is built on decades of large-scale infrastructure expertise including technologies like direct liquid cooling that are powering our largest AI systems for model builders, service providers, and supercomputing users. Interest in our HPE AI solutions, particularly from enterprise and sovereign customers, continues to grow. AI systems orders climbed $1.6 billion in the quarter to a cumulative $6.2 billion since Q1 2023 – an increase of approximately $3.5 billion over the last year."

Server revenue in the quarter was $4.3 billion, up 35% from a year ago. Intelligent edge revenue was $1.1 billion, down 23% from a year ago. That business is mostly Aruba.

Hybrid cloud revenue was $1.3 billion, down 7% from a year ago.

As for the outlook, HPE projected fourth-quarter revenue between $8.1 billion and $8.4 billion with non-GAAP earnings of 52 cents a share to 57 cents a share. The non-GAAP figure excludes an after-tax net gain due to H3C income of $2.1 billion due to a partial sale and various adjustments. For fiscal 2024, HPE projected revenue growth of 1% to 3% with non-GAAP earnings of $1.92 a share to $1.87 a share.

Speaking on the earnings call, Neri said:

"We saw sequential and year over year orders growth, but with some geographic variation, demand was strong in North America, Asia Pacific, Japan and India, as Europe and the Middle East lacked. We are aggressively going after the opportunities presented by better market conditions, and are well positioned in a competitive and dynamic environment. 

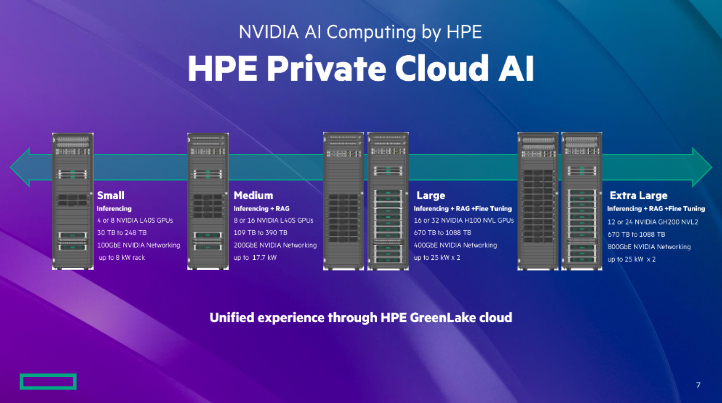
We have accelerated innovation across all pillars of our strategy, networking, hybrid cloud and AI delivered through a unified cloud, native and AI driven experience as a part of our HP Greenlake Cloud Platform. Today, almost 37,000 unique customers use our HP Greenlake cloud to manage their hybrid IT estate."

Neri also addressed AI use cases:

"We continue to pursue profitable deals within our target server margin range, underscoring stability in our operating profit profile. In AI our momentum is very clear. Customer demand for HPE AI systems rolls sequentially, with opportunities increasing in both enterprise and sovereign AI clouds. 

Customers are exploring new ways to use AI, adding to our already robust pipeline and creating even more runway for our broad AI offerings. Enterprise interest in generative AI is high, and while adoption is still in the initial stages, it is accelerated. Customers tell us that they see the possibilities in building the business cases."

Data to Decisions Tech Optimization HPE Chief Information Officer