Results

Event Preview - What I would like Workday to address at Rising 2015

Event Preview - What I would like Workday to address at Rising 2015

This week one Workday will have their user conference in Las Vegas, Rising, so it's time to collect thoughts before the conference gets in full swing soon.


So take a peek, here you go:


In case you have no chance to watch - the key areas to watch here:

 
  • Workday Momentum - Workday is an exceptional growth story - it will be interesting to see how customers, prospects, the overall ecosystem is doing.
  • HCM - Time to see if and which more of analytical apps are shipping, good to check momentum of recruiting, how things are doing on Payroll both natively provided by Workday and then with the many partners and lastly how the Learning management partnerships are doing. 
  • Finance - It really comes back to momentum, and what other capabilities Workday has added recently to convince customers of its capability to run BigFin.
  • SCM - SCM? Yes really SCM - Workday announced Inventory capabilities for Healthcare earlier this year. But inventory is as horizontal a ERP capability as the come - so it will be important to understand where Workday plans to apply Inventory beyond Healthcare and if this is going to become 'the third leg of the stool' for Workday.
  • Industry Momentum - Workday is seeking growth from more vertical functionality, time to check where things stand and what the plans are. 
  • Technology - The objective from my side is to scoop up any platform innovation - may it be on the deployment side or user interface side and more.
 
And more on Workday
  • News Analysis – Workday to Expand Suite of Applications for Healthcare Industry - with a SCM twist - read here
  • News Analysis - Workday supports UK Payroll - now speaks (British English) Payroll  - read here
  • Workday 24 - 'True' Analytics, a Vertical and more - now needs customer proof points - read here
  • First Take - Top 3 Takeaways from of Workday Rising Day 1 Keynote - The dawn of the analytics era - time to deliver Insight Apps - read here
  • Progress Report - Workday supports more cloud standard - but work remains - read here
  • Workday 22 - Recruiting and rich Workday 22 are here - read here
  • First Take - Why Workday acquired Identified - (real) Analytics matter - read here
  • Workday Update 21 - All about the user experience and some more - read here
  • Workday Update 20 - Mostly a technology release - read here
  • Takeaways from the Salesforce.com and Workday partnership - read here
  • Workday powers on - adds more to its plate - read here
  • What I would like Workday to address this Rising - read here
  • Workday Update 19 - you need to slow down to hurry up - read here
  • I am worried about... Workday - read here
Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my YouTube channel here
Future of Work Matrix Commerce Tech Optimization Data to Decisions Innovation & Product-led Growth Digital Safety, Privacy & Cybersecurity Distillation Aftershots Revenue & Growth Effectiveness New C-Suite Next-Generation Customer Experience workday AI Analytics Automation CX EX Employee Experience HCM Machine Learning ML SaaS PaaS Cloud Digital Transformation Enterprise Software Enterprise IT Leadership HR IaaS Disruptive Technology Enterprise Acceleration Next Gen Apps IoT Blockchain CRM ERP CCaaS UCaaS Collaboration Enterprise Service Chief People Officer Chief Customer Officer Chief Human Resources Officer Chief Information Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer Chief Executive Officer

Dreamforce 2015 Winners and Losers

Dreamforce 2015 Winners and Losers

1

Dreamforce is over for another year. This year there were 170,000 attendees, 400 partners and 1,600 sessions. In any measure the event is a big deal and the Launchpad for Salesforce through the next year.

The winners for the event loomed large this year, as they tend to do.

  • Salesforce itself is clearly a winner to garner the attention of the technology community to the extent that Dreamforce is arguably the highest profile tech event and is a creator of cloud energy like no other vendor with the possible exception of AWS
  • The integration of Microsoft and Salesforce, was very significant. Clearly the relationship is very deep between the two vendors. The integration of Salesforce into the Microsoft platform is very clear, the interface is consistent and user friendly. This was the biggest deal for Dreamforce for mine.
  • Microsoft second coming as a device and platform agnostic software provider now.
  • The increasing horizontal depth of SF with IOT and Analytics. Whilst the IOT capability in particular is immature and still a lot of slide-ware, the intent is real, and the history of Salesforce is clear in suggesting that it can execute.
  • Salesforce increased focus on Industry based solutions. This will continue to become a critical agent of the strategy as it matures in the next 12 months.
  • The depth of collaboration of the Salesforce ISV ecosystem that is unmatched in other major software vendors
  • Independent System Integrators providers – The acquisition of Cloud Sherpas by Accenture just changed their dynamic, and increased their value in the eyes of investment bankers

The losers for the event were just as clear

  • The keynotes. They need some reinvigoration, the customer examples, in particular Cisco was cringe worthy from both a script and “acting” perspective. Just get new Cisco CEO, Chuck Robbins up there, not Salesforce execs in tech coats.
  • Large SI’s. capioIT has highlighted the strength of Accenture in the SI space for cloud services. The acquisition of Cloud Sherpas only reinforces this. A lot of the legacy SI’s risk being left behind, and quickly unless they act soon. IBM, Tata Consultancy Services and Infosys are at the front of the queue of vulnerable providers.
  • The Salesforce “No Software” Logo. If Co-founder Mark Benioff is correct and Salesforce becomes the 4th largest software provider next year, then the gimmick, whilst successful has more than run overtime.
  • The Microsoft Dynamics team. I understand co-opetition better than most, but this was not a good moment for Dynamics. Microsoft clearly, and rightfully considers Office to be the primary application to protect, not Dynamics.
  • Stevie Wonder – You are the Dreamforce of my life. Part of my soul died with that line. “Everyone has a price” is more true today, than at any other time in human society

Focus Point

Dreamforce is clearly one of the most important events on the calendar for the integration of technology and business. It captures the attention of millions of professionals. In 2015, the clear winners were Microsoft and Salesforce. Expect these two vendors to get even closer before we hit Dreamforce 2016.

If you require further information, please contact Phil Hassey, Founder capioIT. capioIT is an advisory firm focused on helping organisations to understand emerging technology as the world becomes Digital. 


Tech Optimization Dreamforce salesforce Chief Information Officer

Does government have the innovation appetite?

Does government have the innovation appetite?

Under new Prime Minister Malcolm Turnbull, innovation for once is the policy du jour in Australia. Innovation is associated with risk taking, but too often, government wants others to take the risk. It wants venture capitalists to take investment risk, and start-ups to take R&D risks. Is it time now for government to walk the talk?

State and federal agencies remain the most important buyers of IT in Australia. To stimulate domestic R&D and advance an innovation culture, governments should be taking some bold procurement risk, punting to some degree on new trechnology. Major projects like driver licence technology upgrades, the erstwhile Human Services Access Card, the national broadband rollout, and national e-health systems, would be ideal environments in which to preferentially select next generation, home-grown products.

Obviously government must be prudent spending public money on new technology. Yet at the same time, there is a public interest argument for selecting newer solutions: in the rapidly changing online environment, citizens stand to benefit from the latest innovations, bred in response to current challenges.

What do entrepreneurs need most to help them innovate and prosper? It's metaphorical oxygen!

Innovators need:

  • access to prospective customers, so we may showcase disruptive technologies
  • procurement processes that admit, nay encourage, some technology risk taking
  • agile tender specifications that call for the unexpected in responses - disruptive technologies
  • open-mindedness from big prime contractors, who too often are deaf to inventive SMEs
  • curiosity for innovation amongst business people
  • optimism amongst buyers that small local players might have something special to offer
  • and a reversal of the classic Australian taboo against sales.

Too often, innovative Australian entrepreneurs are met with the admonition "you're only trying to sell us something". Well yes we are, but it's because we believe we have something to meet real needs, and that customers actually need to buy something.

Digital Safety, Privacy & Cybersecurity Chief Customer Officer

Cloud Computing Dominates Deloitte’s 2015 Global Venture Capital Confidence Survey

Cloud Computing Dominates Deloitte’s 2015 Global Venture Capital Confidence Survey

1
  • global cloudCloud computing is the strongest technology investment sector for the third year in a row.
  • Biopharmaceuticals and robotics are the two sectors that have gained the greatest venture capital confidence from 2014 to 2015.
  • U.S. technology hubs (Silicon Valley/San Francisco, New York, Boston, Los Angeles & Chicago), Israel and Canada dominate while confidence continues to fall in Brazil and other emerging markets.

These and other insights are from Deloitte’s 2015 Global Venture Capital Confidence Survey.  You can download a copy here (PDF, no opt-in, 70 pp.).  Deloitte has also produced and made available infographics of the key findings here (PDF, no opt-in, 4 pp.). Deloitte & Touche LLP and the National Venture Capital Association (NVCA) collaborated on the eleventh annual survey, which was conducted in May & June of this year. The study assesses investor confidence in the global venture capital environment, market factors shaping industries and investments on specific geographies and industry sectors.    Please see page 4 of the study for a description of the methodology.

Key take-aways include the following:

  • Global venture capital investors are most confident in cloud computing (4.18). Investors were asked to rate their confidence level in each sector. Confidence levels were measured on a scale of 1 to 5, with 5 representing the most confidence. Basis points indicate year-over-year changes. Mobile (4.05), Internet of Things (3.95) and enterprise software (3.82) are the top four sectors venture capitalists are the most confident in today. Biopharmaceuticals are experiencing the greatest increase in venture capital confidence today.  Please the the graphic below for additional details.

cloud growth

  • The United States (4.17), Israel (3.90) and Canada (3.60) dominate venture capital investors’ confidence while emerging markets including Brazil continues to fall. U.S. technology hubs including Silicon Valley/San Francisco, New York, Boston, Los Angeles and Chicago continue to retain and reinforce global venture capital investor confidence.  The following graphic illustrates global venture capital investor’s confidence by nation.

globe

  • Silicon Valley/San Francisco (4.28), New York (3.86) and Boston (3.77) are the top three U.S. metros global venture capital investors have the greatest confidence in.  Los Angeles (3.43) and Chicago (3.22) are the fourth and fifth most trusted U.S. metros that venture capitalists have confidence in.  $15.2B was invested by global venture capital investors in Silicon Valley/San Francisco according to the Deloitte study.  The following graphic compares venture capitalist confidence levels and venture capital investment dollars received in 2015 through Q2.

US Metro

  •  Immigration reform (61%) and patent demand reform (36%) are the top two  initiatives U.S.-based venture capitalists want addressed by policy leaders.  For non-U.S. venture capitalists, tax incentives/credits (50%), infrastructure and job creation (both 41%) are the top two initiatives they would like to see public policy leaders take on in their home country.

top two

  • Cloud computing continues across all sectors as the area global venture capital investors have the greatest confidence in.  Confidence in biopharmaceuticals grew the fastest of any sector measured by the survey between 2014 and 2015, and this is the first year Deloitte is tracking investor confidence in the Internet of Things (IoT).  A sector comparison is provided below.

sector investing


Tech Optimization Marketing Transformation Next-Generation Customer Experience Innovation & Product-led Growth SaaS PaaS IaaS Cloud Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP CCaaS UCaaS Collaboration Enterprise Service Chief Information Officer Chief Technology Officer Chief Information Security Officer Chief Data Officer Chief Executive Officer

#SocBiz #FutureOfWork News Week Ending Sep 25, 2015

#SocBiz #FutureOfWork News Week Ending Sep 25, 2015

Here is a recap of some of the key news of the last week in the Social Business / Employee Collaboration / Future of Work world.

Did I miss something big? Please post a link in the comments.


Reference Links:

text

The New Salesforce UI, Intelligence and Integrations Help Employees Get Work Done

The new Microsoft Office 2016 is here

Introducing availability of Office 365 Groups in Outlook 2016

Introducing Office 365 Planner

Microsoft Invite—the easiest way to organize meetings on the go

Expanding the availability of Microsoft Send 

IBM Expands Watson Platform for Next Generation of Builders; Extends Industry’s Largest Portfolio of Cognitive APIs

Teambition is a complete and innovative team application suite

Jive Further Expands Its Executive Leadership With Appointment Of David Puglia As Chief Marketing Officer

Pingpad launches

HipChat and JIRA maker Atlassian has reportedly filed to go public

Google Keep: save your thoughts from wherever—including iPhones

Nimble Adds Group Messaging, Templates & Campaign Reports

The Coca-Cola Company Powers Secure Collaboration for 22,000 Employees with Box

BoxWorks | Transform / your business

Constellation's Connected Enterprise 2015


Future of Work Tech Optimization Innovation & Product-led Growth New C-Suite Marketing Transformation Next-Generation Customer Experience Revenue & Growth Effectiveness Data to Decisions Digital Safety, Privacy & Cybersecurity Chief Marketing Officer Chief People Officer Chief Revenue Officer Chief Experience Officer

A Report from ADP Analyst Day: New UI, Vantage Talent Management, and ADP Data Cloud

A Report from ADP Analyst Day: New UI, Vantage Talent Management, and ADP Data Cloud

We had the opportunity to attend the ADP Analyst Day in New York today, ADP commanded the 'usual suspects' to New York (though we learnt some like to be called pundits) into their amazing innovation lab in the heart of Manhattan.


I was joined by fellow Constellation analyst R 'Ray' Wang so we recorded a short video summary of the event... take a peek:

 
If you can't watch - here are the top 3 takeaways:
 
  • The new UI ADP showed us last year and then rolled out to paycheck and selected use cases is now been rolled out to 80% of ADP applications. That by itself is a massive undertaking, but will help customers get more out of their ADP products, which in some cases sported more than pedestrian user experiences.
  • The ADP Talent Management product Vantage has also received the new user interface and with that the 'grey is gone' mission has been accomplished, except for the recruiter experience which is supposed to follow soon.
  • The ADP Data Cloud is one of the most exciting offerings in the ADP portfolio at the moment, helping customers to make more sense of their data. It also offers 'true' analytics to users, about key HR practitioner questions. Remarkably the product supports also the capability to include 3rd party, non HCM data, thus enabling insights beyond the traditional stovepipe contained intelligence approach.


Tidbits

  • ADP makes progress for multinational companies (MNCs) - bringing together products and services, now for over 104 countries and 99% of global employee population.
  • ADP is so comfortable of its products that it let the analysts use the new Onboarding solution, which was both an entertaining as well as educational way to get to know the ADP applications. 
  • The ADP market place is now at over 60 partners and growing fast, a good sign. Good to see business user enabled purchases options, which is the latest bastion to call in the overall IT trend to empower business users more (IT liking it or not). 

MyPOV

Compared to previous summits ADP showed overall less innovation, but that's a good sign for customers, as innovations are being built into product. Mainly that's the new user interface is responsive, can be embedded in 3rd party products, so overall a very positive experience.

On the concern side ADP must now execute on the sales side. The numbers shared for customer growth are encouraging, but ADP show it can really go to cloud scale - beyond the product, but also in marketing, sales, implementation and support. Closer to product the scalability and TCO of its proprietary cloud infrastructure will also be tested (we did not get briefed on it). 

But for now all signs are positive, ADP has eliminated a number of challenges it faced in the market, so time to look at ADP with a fresh mindset, it's not your father's ADP. Stay tuned.
 
More on ADP
 
  • Event Report - ADP Meeting of the Minds - It’s all coming together for ADP in 2015 - product wise - read here
  • First Take - ADP Meeting of the Minds - Day #1 Keynote - read here
  • Progress Report - ADP shows great vision, delivers product innovation - now it needs adoption - read here
  • Site Visit - ADP's new innovation lab in Chelsea - read here
  • News Analysis - ADP announces Spin-Off plans for Dealer Services, sharpens ADP's focus on HCM - read here.
  • Event Report - ADP's Meeting of the Minds - ADP has made up its mind (almost) - customers not yet - read here.
  • First take - 3 Key Takeaways from ADP's Meeting of the Minds Conference Day 1 Keynote - read here.
  • ADP innovates with with verve and good timing – read here.
 
And  more on the importance of the paycheck for HCM:
 
  • Could the paycheck re-invent HCM – yes it can – read here.
  • And suddenly, payroll matters again! Read here.
Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my Youtube channel here
 
And last but not least - a compilation of key tweets from the event:
 
Future of Work Next-Generation Customer Experience Innovation & Product-led Growth Tech Optimization New C-Suite Revenue & Growth Effectiveness Data to Decisions Marketing Transformation Digital Safety, Privacy & Cybersecurity ADP AI Analytics Automation CX EX Employee Experience HCM Machine Learning ML SaaS PaaS Cloud Digital Transformation Enterprise Software Enterprise IT Leadership HR Chief People Officer Chief Customer Officer Chief Human Resources Officer

Tata Consultancy Services Analyst Day: What Stands Out?

Tata Consultancy Services Analyst Day: What Stands Out?

TCS says it’s now among the top-four in consulting and business process services in terms of brand recognition. Here are three ways TCS differentiated itself at its annual analyst day.

Descriptions of consulting services, business process solutions and outsourcing options are often hard to differentiate from one provider to the next. Here are three things stood out to me at this week’s Tata Consultancy Services (TCS) Analyst Day 2015: plentiful customer case examples, positioning around taking some of the artisanal (meaning, bespoke and costly) quality out of consulting, and the IT-focused nature of the IGNIO neural automation technology.

The theme at the TCS event was “Default is Digital,” meaning that most every enterprise now aspires to capitalize on five familiar digital trends: mobility and pervasive computing, social media, big data and analytics, cloud and robotics (a.k.a. automation). TCS surpassed $15 billion in revenue last year, and it presented third-party research here that shows that the company is now in the top tier of consulting and systems integration firms (after IBM, HP and Accenture) as measured by brand recognition. TCS has boosted that recognition in part through worldwide sponsorship of endurance running events including the New York City Marathon.

@TCS_NA, #tcsarday, #BPO, #bigdata

These are among the common themes TCS identified as moving us toward digital enterprises.

TCS says it’s helping its clients with two big imperatives. First, there’s industrializing software and processes so they just work in cost-effective, automated and repeatable ways. Second, and more importantly, it’s helping companies to reimagine the art of the possible by exploiting game-changing digital capabilities such as pervasive computing and big data and analytics.

We heard at length about TCS consulting, business process solutions and outsourcing services, but it’s hard to tease out clear nuances among similar-sounding services across the many consulting and systems integration firms. As I explain in the video below, I was most impressed by the real-world customer examples presented, including one presented by an “industrial services firm” executive who was there in person. Unfortunately we were asked not to share the name of his firm, but it’s an industry giant that’s strongly associated with Internet of Things innovation.


EVENT REPORT: INSIDE TCS ANALYST DAY 2015 from Constellation Research on Vimeo.
 

MyPOV on TCS Analyst Day

To get beyond the sound-alike buzzwords and categories of service offered by consulting and business process solutions and outsourcing firms, it’s crucial to explore customer case examples that fit the areas and kinds of challenges you’re trying to address. All the better if the firm can name the names of the firms and share executive references. TCS has lots of slick customer testimonial videos, but it’s only in conversation and in in-depth case studies that you get to the unvarnished truth and detail of an engagement.

Perhaps the most differentiating point I heard at TCS Analyst Day came from Krishnan Ramanujam, VP & Global Head, Consulting and Enterprise Solutions, who said that TCS is taking a “disruptive” approach by taking some of the “artisanal quality” out of consulting engagements. That means it’s looking to apply repeatable approaches and solutions in non-differentiating areas while applying unique expertise and customer-specific solutions at the core of the engagement.

Citing one example, Rumanujam said TCS was able to complete an engagement in less than five months at a cost of $3 million for one client where “high profile rivals” had bid $30 million and $16 million, respectively, and were looking for engagements of 18 to 24 months. One lynchpin of this strategy, says Rumanujam, is working with existing clients, so TCS has a leg up on understanding the firm’s operations and challenges and can avoid lengthy fact-finding interviews and exploratory analyses.

One other stand-out presentation at TCS Analyst Day detailed Ignio, which is this firm’s entry into the cognitive computing and artificial intelligence arena. Launched in June, Ignio is about “igniting change,” and the idea is to replace robotic automation with what it calls neural automation. Instead of having to explicitly program rules and automation – an approach that doesn’t scale and doesn’t last, due to rapid change within organizations – TCS says it has equipped Ignio with human-brain-like contextual awareness, composable skills and pattern-recognition capabilities. When you plug it into your data sources and systems, it autonomously learns about the technical functioning of an enterprise and automatically and proactively spot poor system performance and looming problems without human guidance.

What stood out about Ignio is that it’s squarely focused in the IT domain rather than tackling business process challenges. In that sense Ignio seems less ambitious than, say, IBM Watson or other cognitive computing initiatives. It’s aimed at the keep-the-lights-on challenges that consume the bulk of IT’s time, and that’s a good place to target next-gen automation capabilities. It also presents a technology solution to a technical audience first rather than expecting business people to trust and pioneer a new capability. It’s a conservative approach that just may be the most realistic way to wade into the cognitive arena.


Data to Decisions Future of Work Next-Generation Customer Experience Tech Optimization Chief Customer Officer Chief Information Officer Chief Digital Officer

Infographic Friday: The 2015 Marketing Rugby World Cup

Infographic Friday: The 2015 Marketing Rugby World Cup

1

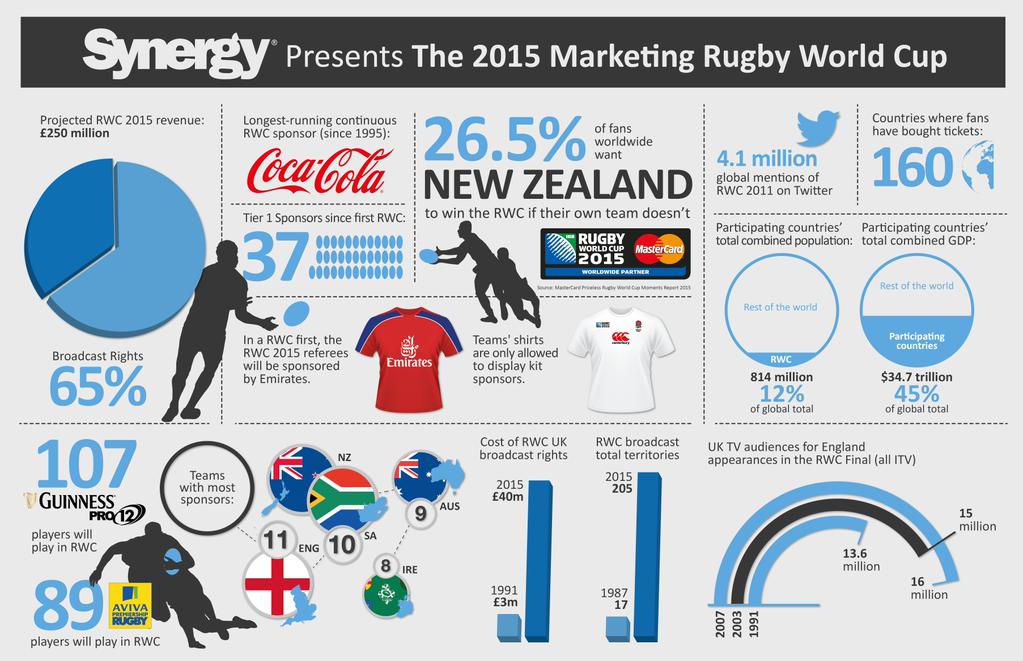
It’s time for another edition of Infographic Friday. Today’s content comes to us from Synergy and @SynergyTim who put together a great set of marketing insights from the 2015 Rugby World Cup. It has a little bit of everything from broadcast rights and kit sponsors to Twitter mentions and TV ratings.

Check out the full infographic below or click here to see the original version via @SynergyTim on Twitter.

Rugby World Cup Marketing

Marketing Transformation Next-Generation Customer Experience Innovation & Product-led Growth Chief Marketing Officer

Technology is changing, but what is making everything change? A summary of change factors in technology and business in 2015 Part I

Technology is changing, but what is making everything change? A summary of change factors in technology and business in 2015 Part I

After a semi sabbatical summer; semi in the fact that I continued to actively follow the industry, its business customers and attempt to understand implications; sabbatical in the sense that I didn’t try to react to each announcement or event individually; instead I was looking for a bigger picture to form. This is the first part of three posts breaking the picture down into the natural divisions of ‘causes’; ‘responses’; and ‘good practice’.

The big picture this far into 2015 is one of strategic change in the face of increasingly obvious disruption to ‘Business as usual’. Current IT industry leaders, together with major global enterprises in multiple sectors have, and are, announcing new goals with new enabling partnerships frequently of an unlikely nature.  Everywhere, in every sector, are new startups creating the disruption in previously well-defined market sectors forcing established leaders to react. (see footnote 2).

Any successful competitive positioning has to understand what is the root causes enabling, and driving, this disruption, and how can my business successfully harness them. But can this question be answered in an understandable manner?

In aggregate the totality of these changes to cover is too much to absorb, and too ambitious for a single blog piece! But there is a relatively simple set of foundations forming the starting point to building a comprehensive understanding and that’s the starting point for this blog. Once again as with the blogging format used last winter to explain emerging IoT from simple concepts through to more complex issues and deployments there will be a linked series of blogs, alternating each week between the Technology enablers, and the Business drivers. But to start with a surprisingly clear big picture, or high level, summary of what is at the heart of this change; and in a word the answer is de-centralization.

De-centralization; The transfer of decision making power and assignment of accountability and responsibility for results. It is accompanied by delegation of commensurate authority to individuals or units at all levels of an organization even those far removed from headquarters or other centers of power.

Source; the business dictionary.

Every aspect of the world, including politics, is now showing increasing sign of de-centralization arising from the low cost technology empowerment of individuals to participate in powerful informed manner. There are two important core technology elements that have brought this about;

A redefinition of Moore’s Law in 2015 would state that every eighteen months the cost of a processor of the same power will halve; Similarly redefining the lesser known Metcalf’s Law from the 1980s LAN era would state that the number of devices that can interact with networked resources is the logarithmic value multiplier rather than the original Laws focus on connectivity for application transactions.

Combine those two elements; add simplicity in usability, the increasing technology awareness and capability of the population as a whole, and the result is to see the traditional barriers, (high levels of investment, substantial support costs, and expensive training) that have prevented de-centralization all start to dissolve. (It is worth noting that both laws in their original forms actually underpinned, and supported, the path of technology towards bigger, more expensive, centralized enterprise computing using client-server in support of the then business imperatives of Back Office transformation with IT and ERP).

This is a level of disruption in the ownership, and use, of, resources to both create, and satisfy, market demands akin to the scale, though exactly in the opposite direction, of the shift in the nineteen twenties and thirties into mass production that made many products affordable. However massive investment in expensive resources to create scale certainly limited the numbers of enterprises that could compete for, and remain in control of, the new markets.  The resulting affordability of many items led to the creation, or enlargement, of many markets; a popular example is the automotive industry where reducing prices exploded the overall size of the market, both in numbers of buyers and in total revenues, but diminished the numbers of automotive manufacturers.

Nearly one hundred years later the basis for many business models arising from huge centralized investments that restrict market change and competitive entry is being destroyed. Today huge resources in computing, marketing, or any aspect of business are available as a hosted service allowing new players to enter almost any market with an innovative disruptive approach. De-centralization also allows a new competitor to assemble exactly the resources required…. with little capital investment.

The side effects of affordable mass manufacturing for consumers (buyers) is increased standardization in products usually with a reduction in number of suppliers; for the manufacturer the challenge is constant price/margin erosion as price/cost is the basis of the competitive element. Whilst it is true that many business models are built around business-to-business operations, as Economists are quick to point out the end point of all business lies in consumer purchases.

Affluent consumers are seeking individuality and are prepared to pay for it, suddenly making small and personal an important part of any new product, or markets. Competitive choice and differentiation becomes as, or even more, important than price; a welcome move in re-establishing margins for successful enterprises who master the new Digital Business game. 

When consumer (buyer) choice is no longer limited to locality, or a handful of previously dominate large companies; and resources are no longer expensive constraints to new competitive entrants, or products; the result is disruption to the majority of business activities. Moreover this is a disruption on the same scale as the introduction of massive scale and resources that signaled the destruction of localized and craft production based markets one hundred years ago. The very revolution that created most of today’s successful global enterprises!

The realization that Digital Business is about adding a new online capability to your existing business model, but is the disruptive recreation of your industry sector is dawning rapidly in Boardrooms as sector news and financial results are the cause of serious evaluation. 

  1. Part two of this blog will examine examples of how global Enterprises and startup businesses are creating new markets by using these change factors
  2. In judging the awards for Constellation Research Connected Enterprise annual Super Nova competition it was extremely noticeable that new hardly known startups dominated the entries submitted by their satisfied customers. In each case the change achieved could truly be described as both innovative and disruptive, whilst the outcomes for the enterprise and its business were remarkable and substantial. See Constellation Connected Enterprise for more details on awards.


TCS "gets" disruption - invests in IaaS, BPaaS

TCS "gets" disruption - invests in IaaS, BPaaS

We had the opportunity to attend the TCS analyst summit in Boston, the event was well attended, with over 50 analysts (my estimate) in the audience. 


Before leaving Boston I recorded this short video - so take a peek:


Here are the key takeaways:

 
  • TCS understands all areas of disruption well, and has customers live in all areas from Customer Experience over IoT to digital transformation.
  • The provider is running its own IaaS in India, UK, US and Australia, the TCS Cloud is being rolled out further into the Nordic Countries and Canada. 
  • TCS has made investments into enabling the BPaaS (Business Process as a Service) - with TAP - TCS Accounts Payable, supporting 40+ countries today.

MyPOV

TCS is well aware of the fundamental transformation that is happening to the consulting, system integrator and outsourcing services space. Wage arbitration is a diminishing factor, so it is good to see that TCS not only understands the new disruptive scenarios, but also masters the technologies and has customer references to show in each of them. Promising are also investments on IaaS side as well as the BPaaS side.
 
On the concern side we see a services vendor building more product, never an easy transformation, that so far has only happened in very few occasions. TCS executives understand that there is a one time opportunity to capitalize on in regards of building next generation products for the best practices of the infinite computing era, I missed the presentation of the ignio platform due to schedule issues.
 
And last but not least - a compilation of key tweets from the event:
 
Tech Optimization Data to Decisions Digital Safety, Privacy & Cybersecurity Innovation & Product-led Growth Future of Work Next-Generation Customer Experience Tata Consultancy Services AI ML Machine Learning LLMs Agentic AI Generative AI Analytics Automation B2B B2C CX EX Employee Experience HR HCM business Marketing SaaS PaaS IaaS Supply Chain Growth Cloud Digital Transformation Disruptive Technology eCommerce Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP Leadership finance Customer Service Content Management Collaboration M&A Enterprise Service Chief Information Officer Chief Technology Officer Chief Digital Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Executive Officer Chief Operating Officer