Results

News Analysis: Amazon Sidewalk Ups The Battle For Last Inch Connectivity

News Analysis: Amazon Sidewalk Ups The Battle For Last Inch Connectivity

Media Name: rwang0-amazon-amazonsidewalk-swpack1.jpg

Amazon Sidewalk  

Key Features Extend Last Inch Network

On Friday May 7th, 2021, Amazon announced a series of updates to Amazon Sidewalk.  Sidewalk delivers last mile connectivity via a network bridge protocol on Amazon's smart home devices.  The Sidewalk Bridge devices such as Echo products and Ring Floodlight Cams use a 900 MHz band and Bluetooth Low Energy (BLE), to extend WiFi networks .  The partnership with Tile announced in the Fall of 2020 can connect with any Bridge device to deliver not only the last mile, but the last inch inside community wide networks build on these Bridge devices.

Sidewalk Bridges

Sidewalk Bridges are devices that provide connections to Amazon Sidewalk. Today, Sidewalk Bridges include many Echo devices and select Ring Floodlight and Spotlight Cams. A comprehensive list of Sidewalk devices includes:

  • Echo (3rd generation and newer)
  • Echo Dot (3rd generation and newer)
  • Echo Dot for Kids (3rd generation and newer)
  • Echo Dot with Clock (3rd generation and newer)
  • Echo Plus (all generations)
  • Echo Spot
  • Echo Studio
  • Echo Input
  • Echo Flex
  • Ring Floodlight Cam (2019)
  • Ring Spotlight Cam Wired (2019)
  • Ring Spotlight Cam Mount (2019)

Sidewalk devices

  • Tile
  • Ring Car Alarm

New Announcements Extend Devices And Reach

The Amazon Sidewalk neighborhood network gained three new features:

  1. Tile joins Sidewalk to help customers find lost items.  Users can find items tagged by Tile via Alexa.  Echo devices will extend the coverage area to find Tiles bluetooth tagged objects.
  2. Level partners with Sidewalk to control smart locks.  The range of Amazon Sidewalk makes it easier for any smart device in connected homes.  Level lock connects directly to Ring Video Doorbell Pro devices.
  3. CareBand improves quality of life.  CareBand is helping dementia pateints with wearable technology that can provide indoor and outdoor activity racking.  Help buttons and automated analysis of activity patterns provide 24/7 monitoring.  With Amazon Sidewalk, no mobile devices are needed.
  4. Sidewalk supports compatible Echo devices on June 8th.  Echo devices can extend the reach of Sidewalk.  Amazon has provided smart privacy provisions.  Shared data is protected with three levels of encryption. Users decide which devices have access.  Data is automaticaly deleted every 24 hours.


Amazon's product boss Dave Limp has been quoted in multiple media outlets stating, "Sidewalk is all about the next billion things that are going to get on the network".  Amazon's attacking the gap between where celluar ends and where home WiFi begins.  Amazon's Sidewalk network will being support for Tile Bluetooth trackers on June 14th.

On the privacy side, Amazon has shipped the products with opt-in requirements for location based services to protect user privacy.  They've also shipped the connectivity with opt-out to make it easier to adopt.  This balance between privacy and convenience will improve adoption and also help customers easily experience the benefits but manage privacy issues.

The Bottom Line: The Battle Of Last Inch Connectivity Is Here

From Starlink to Comcast and Verizon, delivering on the last mile has been a goal.  Reaching the last inch has come with Apple AirTags with Bluetooth tracker and Amazon Sidewalk with Tile.  As tech giants double down on neighborhood and micro mesh connectivity, expect more partnerships and innovations.  Amazon has smartly enabled many of its Echo devices and all of its Ring devices to extend these networks providing mesh coverage and keeping its devices sticky and deliver more value added digital services.  This latest battle for the last inch will result in only a handful of players, creating the next opportunity for connected services.

Get the latest book Everybody Wants To Rule The World

Data to Decisions Digital Safety, Privacy & Cybersecurity Future of Work Matrix Commerce Next-Generation Customer Experience Innovation & Product-led Growth Tech Optimization New C-Suite Insider Associates SoftwareInsider amazon AI ML Machine Learning LLMs Agentic AI Generative AI Analytics Automation B2B B2C CX EX Employee Experience HR HCM business Marketing Metaverse developer SaaS PaaS IaaS Supply Chain Quantum Computing Growth Cloud Digital Transformation Disruptive Technology eCommerce Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP Leadership finance Social Healthcare VR CCaaS UCaaS Customer Service Content Management Collaboration M&A Enterprise Service AR Chief Analytics Officer Chief Customer Officer Chief Data Officer Chief Digital Officer Chief Executive Officer Chief Financial Officer Chief Information Officer Chief Information Security Officer Chief Marketing Officer Chief People Officer Chief Privacy Officer Chief Procurement Officer Chief Revenue Officer Chief Supply Chain Officer Chief Technology Officer Chief Operating Officer Chief Experience Officer

News Analysis: Crypto FOMO and Bitcoin's Rise Into the $1 Trillion Club

News Analysis: Crypto FOMO and Bitcoin's Rise Into the $1 Trillion Club

Media Name: rwang0-dogecoin-standoff-wall-st.jpg

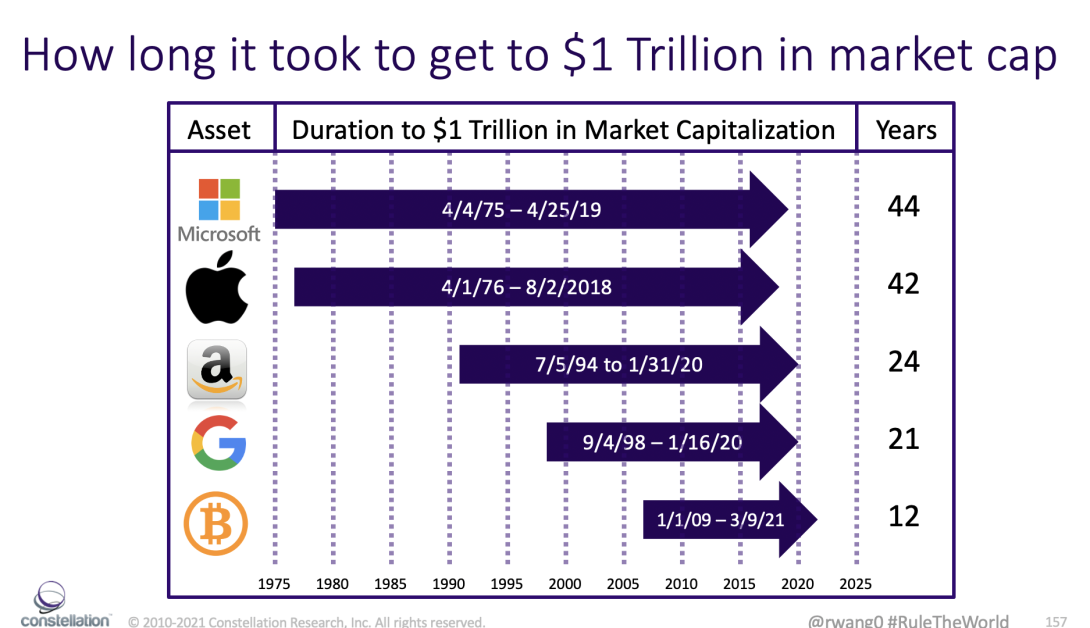
The Road to $1 Trillion in Market Cap 

Crypto FOMO Drives Capital Flows Out Of Big Tech (For Now)

Retail investors have taken money out of the equity market and rotated into crypto to catch the wave.  With all crypto's now worth more than $2 Trillion in market cap and Bitcoin standing out at $1 trillion, this poses a risk to the US dollar dominance as the reserve currency.

  • Bitcoin ($57,000), $1T market cap
  • Ethereum ($3,491), $404 B market cap
  • Binance Coin ($643.74), $98 B market cap
  • Dogecoin ($.597), $77 B market cap
  • XRP ($1.67), $75 B market cap
  • Tether (.9999) $53 B market cap
  • Cardano ($1.63) $52 B market cap

The current rush into crypto and NFT's creates a casino atmosphere and "gold" rush into the next big thing.  Only a few crypto assets will survive in the long run.  Bitcoin's finite limit of 21 million coins, Ethereum's role in commerce, and Cardano seem to have the best prospects.  Expect this trend to continue into the summer and taper off as the reopen rotation gains traction.

The Bottom Line: Don't Count Big Tech Out

The first quarter of 2021 showed how the digital giants continued to grow at break neck paces.  While stock prices reflect a reopen rotation and crypto FOMO trend, few asset classes can show this type of year over year performance.  Don't count big tech out.  Big tech should remain a key component in portfolios.  However, not all big tech stocks are created equal.  Only the digital giants will continue to create competitive moats, invest in innovation, and play the long term game of global domination.

For the year:

  • Google up 30%
  • AirBnB up 22.68%
  • Oracle up 17.42%
  • IBM up 13.93%
  • SAP up 11.16%

Buying big tech stocks on the dip have often boded well for the long term investor.  Tesla, Apple, and Amazon are currently under performing for the year but have long term upside and most likely may be undervalued in the past week.  Take note, Honeywell's entry into the NASDAQ reflects how the company's portfolio is geared for more growth with Quantum Computing and Connected Buildings.

Get the latest book Everybody Wants To Rule The World

Your POV

Are you in the repoen rotation or the crypto FOMO?  What are you investing in next?  Ready to find the next set of digital giants?

Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org. Please let us know if you need help with your AI and Digital Business transformation efforts. Here’s how we can assist:

  • Developing your digital business strategy
  • Connecting with other pioneers
  • Sharing best practices
  • Vendor selection
  • Implementation partner selection
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales.

Data to Decisions Digital Safety, Privacy & Cybersecurity Future of Work Marketing Transformation Matrix Commerce New C-Suite Next-Generation Customer Experience Tech Optimization Innovation & Product-led Growth Distillation Aftershots tesla Insider Associates apple Google IBM SoftwareInsider amazon SAP Oracle Microsoft Leadership Chief Analytics Officer Chief Customer Officer Chief Data Officer Chief Digital Officer Chief Executive Officer Chief Financial Officer Chief Information Officer Chief Information Security Officer Chief Marketing Officer Chief People Officer Chief Privacy Officer Chief Procurement Officer Chief Revenue Officer Chief Technology Officer Chief Operating Officer Chief Experience Officer

Big Idea: Prioritize Long Term Investment Mindset Over Short Term Profits

Big Idea: Prioritize Long Term Investment Mindset Over Short Term Profits

Media Name: rwang0-american-american-airlines-1.jpg


American Airlines OneWorld

Short Term Thinking Crushes Traditional Companies In Fight Against Digital Giants

If legacy companies want to compete with data giants in the age of extreme capitalism, spending capital on innovation needs to STOP being sacrificed for short-term profits.

In 2005, a survey by the Duke Fuqua business school showed that 55% of CFO's at 400 of America's largest public companies would rather sacrifice their firm's economic value to meet a quarterly expectation. Sadly, not much has changed since then.

Don't believe me? Look no further than the airline industry post-COVID-19.

Take American Airlines, which filed for bankruptcy in 2011 but became profitable again by 2014. During six years of record profits, the airline still failed to put together a rainy-day fund for a crisis. It also failed to modernize its technology systems, aircraft, and operating procedures to improve digital channels, enhance analytics, and develop better planning capabilities. Instead, it spent $12 billion of its positive cash flow since 2014 in stock buybacks. American isn't alone, either. Most airlines spent 97% of their free cash flow on buybacks from 2010 to 2020.

Get the latest book Everybody Wants To Rule The World

Your POV

Does your organization take the long view or prioritize short term profits?  Are you reinvesting enough into innovation? Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org. Please let us know if you need help with your AI and Digital Business transformation efforts. Here’s how we can assist:

  • Developing your digital business strategy
  • Connecting with other pioneers
  • Sharing best practices
  • Vendor selection
  • Implementation partner selection
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales.

New C-Suite Matrix Commerce Data to Decisions Innovation & Product-led Growth Revenue & Growth Effectiveness Future of Work Tech Optimization Insider Associates Leadership AR AI ML Machine Learning LLMs Agentic AI Generative AI Analytics Automation B2B B2C CX EX Employee Experience HR HCM business Marketing SaaS PaaS IaaS Supply Chain Growth Cloud Digital Transformation Disruptive Technology eCommerce Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP finance Customer Service Content Management Collaboration M&A Enterprise Service Chief Analytics Officer Chief Customer Officer Chief Data Officer Chief Digital Officer Chief Executive Officer Chief Financial Officer Chief Information Officer Chief Information Security Officer Chief Marketing Officer Chief People Officer Chief Privacy Officer Chief Procurement Officer Chief Revenue Officer Chief Supply Chain Officer Chief Technology Officer Chief Operating Officer Chief Experience Officer

Marketing’s Complex Reaction to Ending the War

Marketing’s Complex Reaction to Ending the War

When Carl von Clausewitz penned On War in 1873, I seriously doubt he had marketing in mind, but in his articulation of the “fog of war” he proves that he gets us.

War is the realm of uncertainty; three-quarters of the factors on which action in war is based are wrapped in a fog of greater or lesser uncertainty. A sensitive and discriminating judgement is called for; a skilled intelligence to scent out the truth.

Now…go back and replace “War” with “Marketing.” I’ll wait here.

Our reality, as a culture, is that we have based our actions and language around war. We execute campaigns. We target. We blast. We relish when small actions go viral: like handing out smallpox infected blankets, we enjoy when something we knowingly unleash infects an unwitting population. We draw battle lines and segment our enemy, carefully noting their behaviors to exploit weaknesses. We hide code in the pixels and stalk our prey.

In military war games, the application of intelligence and enemy tracking, especially through friendly force tracking systems, is key to developing a winning strategy by understanding the behaviors and context of a target to determine the optimal time, attack vector and defense posture needed to win both the battle and the war. Go ahead and let me know when this stops feeling like a MarTech pitch.

In marketing’s culture of war, who is the enemy combatant? The customer is our enemy.

Now. Imagine that in this decades long game of war, someone comes along and says, sorry but we intend to cut off a key stream of skilled intelligence. In fact, we are going to demand that you must proclaim openly and clearly to your enemy what ammunition you have collected, how you will be using your ammunition and give clear opportunity for your enemy to walk off the battlefield with zero penalty or threat of attack. Not only that, but we are also going to cut off your supply of ammunition you obtain through other parties.

The death of the 3rd party cookie and the introduction of Apple’s App Tracking Transparency (ATT) has sent some marketers (and more than a few ad and social platforms) into a tailspin. The demise of the cookie, in particular, has been slowly ratcheting up the stress levels as brands and agencies come to terms with just how often 3rd party cookie data is leveraged for everything from “personalization” (yeah, I put it in quotes…) to campaign optimization.

But let’s take a breath and just look at consumer behaviors in the wake of the ATT launch in iOS 14.5. According to a study from Flurry Analytics, a whopping 96% of users in the US are opting OUT of ad tracking. Their tracking notes that from a sample of 2.5 million daily active users, about 4% are allowing apps access to the Identifier for Advertisers (IDFA). On the other side of the data-shock canal is a study from the team at AppsFlyer in which over 13.2 million instances of a prompt being shown to an end-user. In this study, 39% of those prompts resulted in the user tapping the ALLOW button. The highest rate of “allow” opt-in were across apps like photography (64%), Shopping (44%), finance (42%), food & drink (42%) and non-gaming apps (42%).

Two dramatically different data points from dramatically different points of view. What IS clear, regardless of data source: apps and brands that hold a pre-existing level of affinity with their user are enjoying the benefit of the relationship. Casual gamers, who are typically transient and bounce from farm to farm or puzzle to puzzle, are not typically brand-loyal…and their opt-outs are demonstrating that. For these developers, we are seeing an increase in requests for account sign-ups or pre-ATT prompt content that provides more space to share messages that are in context to the app and displayed at a time that feels less dire and intrusive than the ATT prompt.

Those developers who have taken the time to articulate the VALUE of this requested exchange are also avoiding falling off the cliff. It could be argued they are, for the first time, having an open and honest value exchange discussion with their new partner, the customer.

Customers are tired of being treated like the enemy, being forced to dodge and weave their way through brand’s interpretation of “personalization” that can often be more impersonal and aggravating than mutually valued and valuable. This new age of the customer is asking marketing as an industry and a strategy to rethink our posture of war. In the absence of certain weapons, is there another way to build points of connection between the goals of our businesses and the goals of our customers.

Marketing’s job is shifting from being the General perched on top of the fill looking to pierce the fog of war to craft winning strategy and more like a seasoned host or hostess that can understand that exact moment our guests could really use another glass of wine…and be ready with the perfect sip to keep the relationship and revelry going. It is about knowing who is and isn’t lactose intolerant…and accepting those last-minute curveballs of Kelly being vegan. Afterall, you don’t blast Kelly with information about burgers when she is telling everyone about Veganuary…yet that’s exactly what you do if Kelly is the enemy and you need to control her and force her to eat chicken.

It is easy (and understandable) to have big and bold reactions to the new path of privacy and customer-valued and defined identity. These shifts can feel like the rug is being pulled out from under our strategies. But they are also an opportunity to lean into the behaviors, intentions and higher-fidelity signals our customers are leaving across our own 1st party sources. This is why we’ve seen so many technology solutions from B2B like Demandbase to B2C like Criteo leaning into better ways to deliver efficient and effective engagements through 1st party data stores.

Regardless of where the cookie crumbles, the first thing we need to accept and change is our culture. We need to admit we have been fighting a war. We need to wave the white flag so we can see just how many of our customers are relieved and ready to welcome us to a new party.

New C-Suite Marketing Transformation Next-Generation Customer Experience Chief Marketing Officer Chief Digital Officer

Big Idea: It took 50 years for markets to consolidate down to a few dominant players. Now it takes ten.

Big Idea: It took 50 years for markets to consolidate down to a few dominant players. Now it takes ten.

Media Name: rwang0-ruletheworld-20210713-1620239992727.jpg

Big Idea: It took 50 years for markets to consolidate down to a few dominant players. Now it takes ten. Everybody Wants To Rule The World July 13, 2021 rwang0 Wed, 05/05/2021 - 12:55

The Pace Of Change Continues To Accelerate

It took 50 years for markets to consolidate down to a few dominant players. Now it takes ten.

Countless industries went through gradual reorganization from hundreds or thousands of small players down to a couple of giants. But until very recently, the keyword was “gradual.” There’s no longer going to be a monopoly in each industry. In the next ten years, I expect to see about 100 dominant players in 50 distinct markets worldwide, in most cases with a duopoly of two giants per market.

Those giants won’t be equally strong. The first company to establish a Data-Driven Digital Networks (DDDN) will usually apply its first-mover advantage to take about half of the total addressable market. A second, more reactionary player will take about a quarter of the total addressable market. The remaining 30% (give or take) will go to small players who find ways to survive but have no hope of catching up to the giants. The monopoly has now become a duopoly.

My forthcoming book, Everybody Wants to Rule the World, outlines the very ways in which our playing field is changing and how you can compete to not only keep up but to win. It will be available everywhere on July 13th.

Get the latest book Everybody Wants To Rule The World

Your POV

Do you see your industry collapsing around value chains?  Who are the duopolies in your space? Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org. Please let us know if you need help with your AI and Digital Business transformation efforts. Here’s how we can assist:

  • Developing your digital business strategy
  • Connecting with other pioneers
  • Sharing best practices
  • Vendor selection
  • Implementation partner selection
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales.

Disclosures

Although we work closely with many mega software vendors, we want you to trust us. For the full disclosure policy,stay tuned for the full client list on the Constellation Research website. * Not responsible for any factual errors or omissions.  However, happy to correct any errors upon email receipt.

Constellation Research recommends that readers consult a stock professional for their investment guidance. Investors should understand the potential conflicts of interest analysts might face. Constellation does not underwrite or own the securities of the companies the analysts cover. Analysts themselves sometimes own stocks in the companies they cover—either directly or indirectly, such as through employee stock-purchase pools in which they and their colleagues participate. As a general matter, investors should not rely solely on an analyst’s recommendation when deciding whether to buy, hold, or sell a stock. Instead, they should also do their own research—such as reading the prospectus for new companies or for public companies, the quarterly and annual reports filed with the SEC—to confirm whether a particular investment is appropriate for them in light of their individual financial circumstances.

Copyright © 2001 – 2021 R Wang and Insider Associates, LLC All rights reserved.

Contact the Sales team to purchase this report on a a la carte basis or join the Constellation Executive Network

Data to Decisions Future of Work Matrix Commerce New C-Suite Next-Generation Customer Experience Innovation & Product-led Growth Tech Optimization Insider Associates SoftwareInsider Leadership Chief Analytics Officer Chief Customer Officer Chief Data Officer Chief Digital Officer Chief Executive Officer Chief Financial Officer Chief Information Officer Chief Information Security Officer Chief Marketing Officer Chief People Officer Chief Privacy Officer Chief Procurement Officer Chief Revenue Officer Chief Supply Chain Officer Chief Technology Officer Chief Operating Officer Chief Experience Officer

Monday's Musings: Long Term Loyalty Is Gone!

Monday's Musings: Long Term Loyalty Is Gone!

Media Name: rwang0-long-term-loyalty-gone-ruletheworld.jpg

Long Term Loyalty Is Gone 

Long-term loyalty is gone.

Your customers will trade loyalty for convenience, value, or status.

Consider Domino's. Even though they managed an A+ digital transformation in the 2010s, the company now faces a new existential threat. The enemy is no longer Pizza Hut; it's the new wave of food delivery companies like Uber Eats and DoorDash moving into its sector.

While these food delivery "aggregators" don't own their own kitchens, they do own the customer experience. They can analyze tons of customer data on food preferences and price elasticity. They then partner with "ghost kitchens"— commercial facilities that prepare meals from different cuisines (such as Chinese, Thai, Indian, and pizza) from a single physical location and different online brands.

This agility and data mean the Dominos of the world are about to get their butts kicked! Every company must constantly re-evaluate its business and monetization model and value proposition if they hope to survive.

Otherwise, it's easy to win one war but lose the next.


Get the latest book Everybody Wants To Rule The World

Your POV

Where do you see the future of loyalty? What are you trading loyalty for? Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org. Please let us know if you need help with your AI and Digital Business transformation efforts. Here’s how we can assist:

  • Developing your digital business strategy
  • Connecting with other pioneers
  • Sharing best practices
  • Vendor selection
  • Implementation partner selection
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales.

Data to Decisions Marketing Transformation Matrix Commerce New C-Suite Next-Generation Customer Experience Innovation & Product-led Growth Tech Optimization Future of Work SoftwareInsider AR Leadership Chief Customer Officer Chief Marketing Officer Chief Digital Officer Chief Information Officer Chief Technology Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Executive Officer Chief Operating Officer Chief Experience Officer

Not too much identity technology, and not too little

Not too much identity technology, and not too little

The World Health Organisation (WHO) has released the first of a series of design documents concerning digital proof of COVID-19 vaccination, as the start of a process to standardize digital versions of existing paper “home-based” records and the international “certificate of vaccination or prophylaxis” aka the Yellow Card: “Interim guidance for developing a Smart Vaccination Certificate” (SVC). 

The WHO position so far can be summed up as “Not Too Much Technology; Not Too Much Identity”.

Digitizing proof of vaccination

WHO sets out a worthwhile set of reasons for wanting digital proof of vaccination.  This is a contested policy arena; there are plenty of concerns that vaccine passports would lead to discrimination in employments and travel.  The WHO emphasizes that the making of rules for the use of any SVCs remains a matter for other policy makers. 

So, bearing in mind that proof of vaccination has policy problems, this is how WHO describes the motivation for digital proof:

SVCs can enhance existing paper home-based records and the [Yellow Card] by combining the functionality of both. Additionally, SVCs can provide a way to mitigate fraud and falsification of “paper only” vaccination certificates by having a “digital twin” that can be verified and validated in a reliable and trusted manner, for health, occupational, educational, and travel purposes (as per national and international policies); without depending on an individual verifier’s subjective interpretation. Once an individual’s vaccination record is available in a digital format, additional functionality can be built to support things like automated reminders for the next dose or linkages to other immunization information systems (though these are outside the scope of this document). An SVC is intended to allow for multiple types of use without requiring an individual to hold multiple vaccination records.

Verifiability of vaccination credentials

Until WHO released its guidance, the endeavour to digitize proof of vaccination had been dominated ? almost captured ? by two movements: Self Sovereign Identity and blockchain. Dozens of press reports through 2020 positioned “Verifiable Credentials” as the key to managing vaccine rollouts and “reopening economies”. Some pundits seem to think the long-awaited killer app for digital identity has finally arrived; see e.g. “Coronavirus jumpstarts race for digital ID”.

Several digital proofs of vaccination are being piloted, most of which boast blockchain, including the Evernym IATA TravelPass and IBM’s project in New York City. One of the leading programs in this space is the COVID Credentials Initiative (CCI) formed a year ago by 60 or so companies almost all focused on blockchain. CCI’s messaging today centers on verifiable credentials and minimizes blockchain references.  Yet nevertheless, verifiable credentials are seen by most commentators and technologists as synonymous with ‘identity on blockchain’.

In my view, the technological task of digitizing proof of vaccination is straightforward. Blockchain is neither necessary not sufficient, and no new order is needed for “user-centric” identity management in healthcare (especially in the midst of a pandemic where the priority must be to deliver health services without complicating the way healthcare is managed). 

Verifiable credentials on the other hand are a very good idea indeed, in digital proof of vaccination.  Let’s unpack what is really needed here. 

In essence, any verifiable credential is an assertion about a data subject ?such as “This person had a COVID Type ABC vaccination on April 1, 2021” ? which is digitally signed by or on behalf of the party making the assertion ? such as “Nurse 12345678, ACME Central Vaccination Clinic”.  Ideally the verifiable credential contains a key pair bound to a data carrier controlled by the subject (typically a cryptographic wallet) so that each time the credential is presented, it is signed afresh by the subject’s private key, giving the receiver confidence that the presentation was made with consent of the individual. The fresh dynamic signature also conveys information about the type of wallet the credential was presented from.

Despite the excitement around the new W3C verifiable credential standard and the popular association of verifiable credentials with blockchain, we have had cryptographically verifiable credentials for many years.  The original verifiable credentials were in fact smartcards and SIM cards.

Whenever you use a Chip and PIN smartcard, the merchant terminal cryptographically verifies the digital signatures of the card-issuing bank (proving the account details are genuine) and of the cardholder (proving the transaction was created afresh on the spot, under the cardholder’s control). The same sort of thing happens when you place a mobile phone call: the SIM card digitally signs a packet of account details, proving to the network that you are a legitimate subscriber.  These attributes about end users in different systems are cryptographically verified at the edge of the networks, without ‘calling home to base’.

What has WHO decided?

WHO convened a Smart Vaccination Certificate Working Group  to publish standards for SVC security, authentication, privacy and data exchange.  The interim guidance is the first in a series of three drafts and public consultations leading to a final specification in mid 2021. The Working Group has deliberated already and closed off a number of design decisions, around medical terminology, clinical coding standards, the format of the patient vaccination record, and the technology of the SVC global trust network which will make the certificates widely available and recognizable.

In my view the WHO work has two serious and most welcome implications.  

Firstly the Working Group has expressly endorsed PKI as the technology for a new WHO trust framework for global interoperability of digitized proof of vaccination.  They drew on decades of ICAO e-passport experience and consider the issue of trust framework technology to be "closed " [Ref: line 218 of the consultation paper]. Nevertheless they appreciate that implementing PKI is a significant undertaking, reporting that several countries have called for “assistance related to the establishment of their [public health authority's] national public key infrastructure” [Ref: lines 208-214].  The role of the WHO to facilitate PKI availability and deployment is a work in progress.

Secondly, WHO has stressed that digitized vaccination proofs will not supersede the time-honoured Yellow Card: “vaccination status should still be recorded through the paper-based International Certificate for Vaccination, and Prophylaxis”.  Furthermore, identification of vaccination recipients will be undertaken under existing practices.  That is, WHO sees no need to intervene in identification practices and is not entertaining any idea of a new digital identity framework. The interim guidance spells out that it is expected that a “health worker is able to ascertain the identity of a subject of care, as per the norms and policies of the public health authority” [lines 381-382] and “the identity of the subject of care SHALL be established as per Member State processes and norms” [line 501]. Furthermore, “the SVC is not an identity” [line 382].

In a nutshell, WHO has decided that digitization of the Yellow Card will not entail too much technology (such as the new and unproven blockchain methods or exotic verifiable credentials) and neither will it entail new identity philosophies (such as Self Sovereign Identity, which has untold impact on the way patients and healthcare systems interact).

My analysis and proposal for a Digital Yellow Book

These positions set out by WHO are most welcome, given the tendency for new digital identity movements and technologies to complicate public policy.  I recently wrote a short paper on just these issues and presented it to an IEEE symposium on public interest technologies: “A digital Yellow Card for securely recording vaccinations using Community PKI certificates” (IEEE International Symposium on Technology and Society, 12-15th November 2020, Tempe Arizona).

We should digitize nothing more and nothing less than the fact that someone received their vaccine.  A verifiable credential carrying this information would include the place, date and time, the type of vaccine, and the medico who administered or witnessed the shot.  The underlying technology should be robust, mature and proven at scale ? as is PKI and public key certificates ? and available in a choice of form factors ranging from passive universally accessible 2D barcodes through to contactless electronic certificates in smart phones and medical devices.

Above all, digitizing the fact of a vaccination must be done within the existing contexts of public health administration around the world. No new patient identification protocols should be imposed on health workers.  Let us assume that they know what they are doing today when assessing patients, administering vaccines and keeping records.  There is no call for a new digital identity framework, even if “user centric” seems appealing.  The digitization effort should focus on taking vaccination events and representing them digitally faithfully, accessibly and in-context.

Data to Decisions Digital Safety, Privacy & Cybersecurity Future of Work Tech Optimization Innovation & Product-led Growth AI Blockchain Chief Customer Officer Chief Data Officer Chief Digital Officer Chief Information Officer Chief Information Security Officer Chief People Officer Chief Privacy Officer Chief Supply Chain Officer Chief Executive Officer Chief Technology Officer Chief AI Officer Chief Analytics Officer Chief Product Officer

Event Report: Google Cloud Industries Analyst Day

Event Report: Google Cloud Industries Analyst Day

Media Name: rwang0-ruletheworld-partnership-cloud.png

Google Cloud Industries Leadership

Google Cloud Has Hired A Brain Trust Of Industry Vertical Leaders

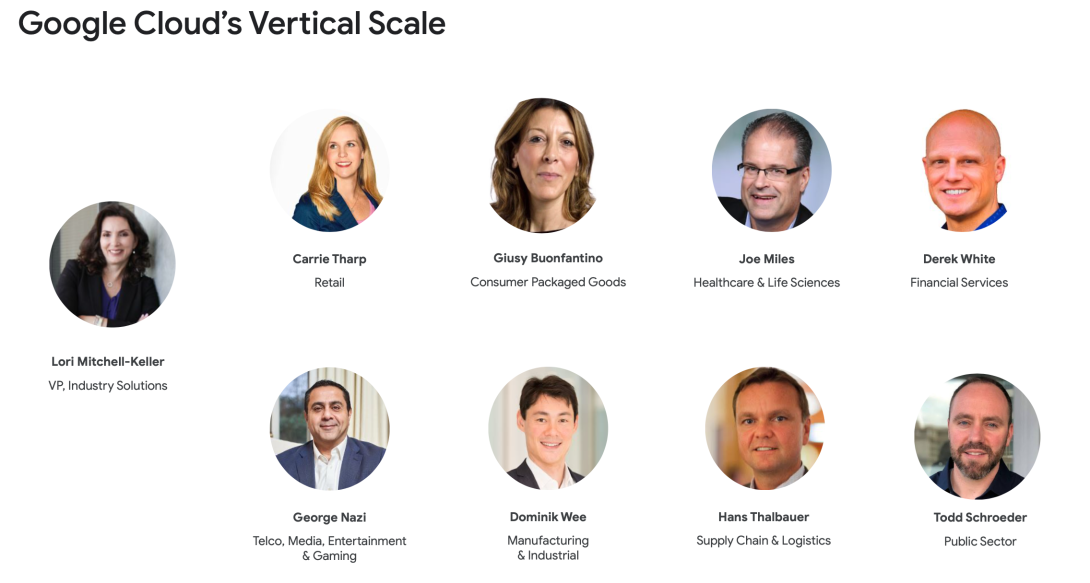
On March 31st, 2021, Google Cloud hosted an Vertical Analyst Roundtable.  Google Cloud CEO, Thomas Kurian, opened up the day with a warm introduction on the role industries will play in the growth of Google Cloud.  Lori Mitchell-Keller, VP of Industry Solutions shared how Google Cloud differentiates its approach to Industries with customers.  The key industries and the leaders for Google Cloud's Verticals include:

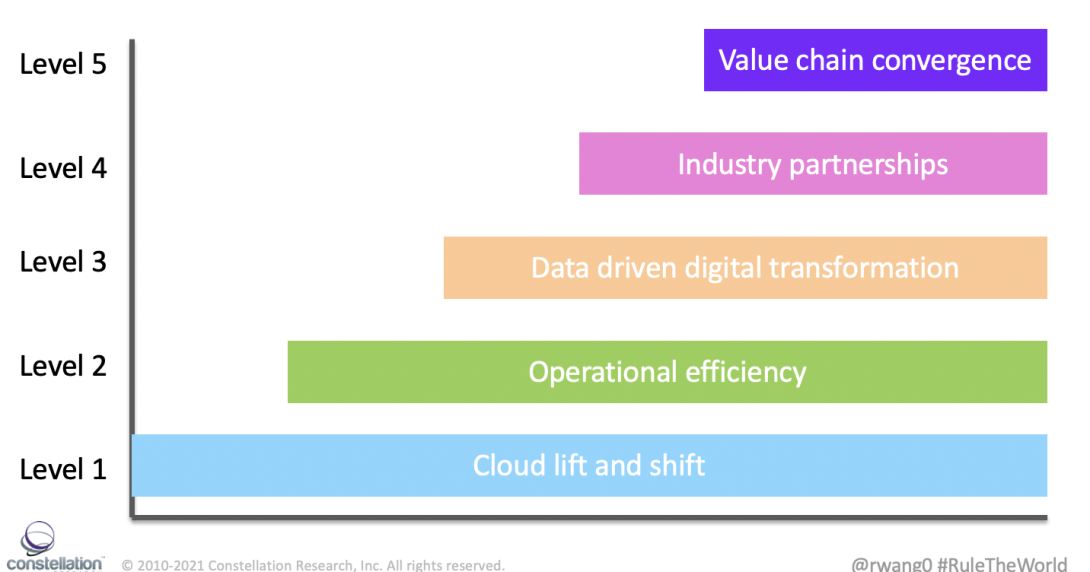
Customer Wins Range From Level 1 to Level 4 Digital Giant Partnerships

  • Retail - focus on immersive and frictionless customer experiences using first party data to accelerate activation, and decrease cost of business
  • CPG - know customers in a data privacy first world, deliver growth in an omni channel ecosystem, and enable a more intelligent sustainable operations
  • Health and Life Sciences - accelerate R&D and clinical insights, achieve precision decisions with ML/AI, and enable population health and value based care models
  • FSI - humanize digital experiences, modernize core technologies and drive out technical debt, adjust to a deluge of regulatory requirements, and manage risk through data
  • Communication Service Providers - create new network-enabled revenue streams, improve low touch high value experiences, evolve service provider networks, upgrade legacy technical debt and core systems, and upskill work force.
  • Media and entertainment - drive up content velocity, deliver mass personalization at scale, ad create dynamic feedback loops to improve relationships and context
  • Manufacturing - digitize customer journeys to improve experience through data, optmiize operations and sustainability, and address cultural and technology needs for digital transformation
  • Supply Chain and Logistics - deliver exceptional customer experience, drive circular economy and sustainability, achieve autonomous enterprise status
  • Public Sector - deliver compliance without compromise, provide tools to accelerate digital transformation, solve for mission needs, and apply vast public data troves for public good.

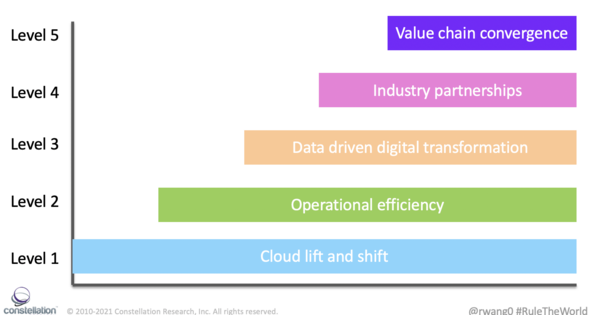
While most of the customers are focused on Level 1 and Level 2 capabilities, Google Cloud is starting to see growth in Level 3 vertical industry wins and becoming more competitive with both Amazon Web Services and Microsoft Azure in industry deals (see Figure 1).  Google Cloud's customer wins at Amwell, Ford, MLB, Target, Unilever, Unity, and Verizon are proof points on the extent of the partnerships with industry for data-driven digital transformation.

Figure 1. The Five Levels Of Cloud Provider Partnerships

Five Levels Of Cloud Partnership #RuleTheWorld

The Bottom Line: Build, Partner, or Perish

In my upcoming book, Everybody Wants To Rule The World, we discuss how the collapse of vertical industries along a convergence of value chains will lead to 100 companies in 50 value chains across seven major geographic trade zones by 2050.  Established organizations who survive to compete against the next set of well-funded digital giants will have to create joint venture partnerships in Level 5 in order to succeed.

Given the capital constraints of the established industry leaders, most will have to partner instead of build. Many of those partnerships will occur with the major cloud platform vendors who can provide the investment capital, the technical expertise, and the key cloud computing and technology prowess needed to win.  Digital leaders who plan for the future will have to double down on one to two cloud players across the world to build deep partnerships or invest in the capital to establish their capabilities.  Winners will build or partner. 

Your POV

Are you a digital leader driving key initiatives? Have you partnered with a cloud vendor? What level is your partnership?  Nominate your project for the 10th annual Constellation SuperNova Awards and buy the book to find out how Everybody Wants To Rule The World

Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org. Please let us know if you need help with your AI and Digital Business transformation efforts. Here’s how we can assist:

  • Developing your digital business strategy
  • Connecting with other pioneers
  • Sharing best practices
  • Vendor selection
  • Implementation partner selection
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales.

Disclosures

Although we work closely with many mega software vendors, we want you to trust us. For the full disclosure policy, stay tuned for the full client list on the Constellation Research website. * Not responsible for any factual errors or omissions.  However, happy to correct any errors upon email receipt.

Constellation Research recommends that readers consult a stock professional for their investment guidance. Investors should understand the potential conflicts of interest analysts might face. Constellation does not underwrite or own the securities of the companies the analysts cover. Analysts themselves sometimes own stocks in the companies they cover—either directly or indirectly, such as through employee stock-purchase pools in which they and their colleagues participate. As a general matter, investors should not rely solely on an analyst’s recommendation when deciding whether to buy, hold, or sell a stock. Instead, they should also do their own research—such as reading the prospectus for new companies or for public companies, the quarterly and annual reports filed with the SEC—to confirm whether a particular investment is appropriate for them in light of their individual financial circumstances.

Copyright © 2001 – 2021 R Wang and Insider Associates, LLC All rights reserved.

Contact the Sales team to purchase this report on a a la carte basis or join the Constellation Executive Network

Data to Decisions Digital Safety, Privacy & Cybersecurity Future of Work Marketing Transformation Matrix Commerce New C-Suite Next-Generation Customer Experience Tech Optimization Innovation & Product-led Growth Revenue & Growth Effectiveness Google Cloud Google SoftwareInsider AI ML Machine Learning LLMs Agentic AI Generative AI Robotics Analytics Automation Cloud SaaS PaaS IaaS Quantum Computing Digital Transformation Disruptive Technology Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP CCaaS UCaaS Collaboration Enterprise Service developer Metaverse VR Healthcare Supply Chain Leadership Marketing B2B B2C CX Customer Experience EX Employee Experience Growth eCommerce Social Customer Service Content Management AR business finance M&A Chief Analytics Officer Chief Customer Officer Chief Data Officer Chief Digital Officer Chief Executive Officer Chief Financial Officer Chief Information Officer Chief Information Security Officer Chief Marketing Officer Chief People Officer Chief Privacy Officer Chief Procurement Officer Chief Revenue Officer Chief Supply Chain Officer Chief Technology Officer Chief Growth Officer Chief Product Officer Chief Experience Officer

Monday's Musings: The Rise of the Digital Executives

Monday's Musings: The Rise of the Digital Executives

Media Name: rwang0-digital.jpg

Digital Leaders and Their Efforts Take a Front Seat in the Post-Pandemic Era

When the pandemic impacted businesses a year ago, most brands and enterprises scrambled to accelerate digital transformation efforts. These “digital” efforts ranged from rekindling digital channel projects to doubling down on digital channels to even accelerating subscription business models. Often led by CIO’s, CMO’s, CTO’s, and Chief Digital Officers, many successfully scrambled to shift channel revenue from physical to digital while dealing the impact of remote work delivery. These accomplishments accelerated five years of digital transformation in less than one year’s time.

As organizations now shift from pandemic burning platform to the post-pandemic reality, the “light” digital projects focused on digital channels will not be enough to sustain true digital initiatives. The simple monetization models will face intense competition. The lack of a digital business model will leave organizations exposed. In fact, digital leaders will have to invest in three key areas of true digital transformation to successfully emerge into the post-pandemic era. Organizations must invest in:

  1. Digital business models. Digital leaders must think hard about how their digital strategy will co-exist in a world of traditional business models. Leaders must determine where will their mix of financial investment and human capital reside.
  2. Digital monetization. Organizations must rethink monetization efforts across ad revenue, search revenues, goods, services, memberships and subscriptions. Selection of monetization model or models will be driven by business model decisions.
  3. Digital channels. While, websites, mobile apps, and chats played a key role in enabling pandemic CX, digital leaders must determine how investment dollars will be allocated in a post-pandemic world as hybrid models will dominate the landscape. Business models and monetization models will determine level of channel investment.

The Shift From CDO's To Digitally Enabled Leaders Is Happening Now

Consequently, who leads such initiatives going forward will be hotly contested. In fact, the role of the chief digital officer must be revisited given the uneven job description and responsibilities across different industries. To be honest, what a CDO does has depended on what industry has sought to create a role. In many cases, chief digital officers have served as CTO’s, others have served as CMO’s deploying a marketing tech strategy, and CIO’s who have had digital initiatives along with keeping the lights on in traditional IT have also served as a CDO. While each of these approaches have merit, this lack of clarity and consistency on what a CDO’s role should be has created some tension and mass confusion in board rooms and among executive leadership teams.

Over the next 12 to 18 months, almost every organization will have beefed up their digital leadership. The rush to anoint a Chief Digital Officer to centrally own all digital initiatives may no longer make sense given the adoption of digital inside organizations and the accelerated digital transformation experienced by leadership. What and how a Chief Digital Officer will be defined may no longer be that important. However, what digital leaders do will play a role.

To start with, expect every role inside an organization to take on digital initiatives. For example:

  1. Chief executive officers will beef up their direct reports and design for new digital business models, assess future partnerships for joint venture approaches, and create a digital culture that supports innovation and execution.
  2. Chief marketing officers will accelerate their digital presence, project their brand’s mission and purpose across all digital channels, apply account based strategies, improve personalization and relevance, and reduce customer acquisition costs.
  3. Chief service officers will improve incident to resolution response via digital channels, identify new monetization models for service, apply IOT models to deploy remote service capabilities.
  4. Chief customer officers will use digital channels to improve community and engagement efforts to improve customer retention, satisfaction, and loyalty.
  5. Chief revenue officers will design for new revenue optimization capabilities, build out digital monetization, apply machine learning and AI to dynamic pricing, improve account based strategies, and improve revenue per customer.
  6. Chief information officers will bring their project execution expertise, improve the overall digital infrastructure and channels, design to support for digital monetization models, compete for data supremacy, and future proof architecture for new digital business models.
  7. Chief supply chain officers will use AI to capture data for demand signals, drive pricing optimization, improve S&OP efforts, create new distribution models, apply 3D printing, and reduce inventory costs.
  8. Chief human resource officers will hire for digital artisans, train and reskill for right-brain and left-brain skills, enable competency based recruiting, create digital employee experiences, and build a digital culture.
  9. Chief financial officers will apply new metrics such as active users, retention rate, customer satisfaction, customer acquisition costs, average revenue per user, profit per sale, market share growth, and reserve asset yield.

The Bottom Line: Digital Enabled CXO's Must Compete With Digital Giants

Digital giants are organizations that have built vast networks of users or devices, mastered how to disintermediate customer account control, deployed digital monetization at scale, competed for data supremacy, and developed a long term growth mind set. Notable examples include entities such as AirBnB, Alibaba, Amazon, Baidu, Coupang, Disney, DoorDash, Facebook, Gojek, Instacart, JD.com, Google, Microsoft, Netflix, Roblox, Tencent, Tesla, Uber, and Zillow in a wide variety of industries.

While Chief Digital Officers may still exist, the entire executive leadership team will grow digital skills as predicted in 2009 by Esteban Kolsky and myself.

The era of the standalone CDO driving all digital initiatives will transition to suites of leaders who have digital capabilities.

This transition to these digital leaders will prepare brands and enterprises to compete with the rise of the digital giants. A broad stable of digital leaders will prepare brands and enterprises to compete with the rise of the digital giants. 

Find out more by pre-ordering my upcoming book: Everybody Wants To Rule The World

Media Name: @rwang0 digital.jpg
Data to Decisions Digital Safety, Privacy & Cybersecurity Future of Work Marketing Transformation Matrix Commerce New C-Suite Next-Generation Customer Experience Tech Optimization Revenue & Growth Effectiveness Innovation & Product-led Growth infor SoftwareInsider CX Customer Service Leadership Marketing B2B B2C Customer Experience EX Employee Experience AI ML Generative AI Analytics Automation Cloud Digital Transformation Disruptive Technology Growth eCommerce Enterprise Software Next Gen Apps Social Content Management Collaboration Machine Learning LLMs Agentic AI HR HCM business Metaverse developer SaaS PaaS IaaS Supply Chain Quantum Computing Enterprise IT Enterprise Acceleration IoT Blockchain CRM ERP finance Healthcare VR CCaaS UCaaS M&A Enterprise Service AR Chief Analytics Officer Chief Customer Officer Chief Data Officer Chief Digital Officer Chief Executive Officer Chief Information Officer Chief Revenue Officer Chief Experience Officer Chief Marketing Officer Chief Technology Officer Chief Information Security Officer Chief Operating Officer
News Analysis: Coupang, South Korea's Digital Giant, Set For A $51 Billion+ Debut

News Analysis: Coupang, South Korea's Digital Giant, Set For A $51 Billion+ Debut

Media Name: rwang0-bon-kim-coupang.jpg

 Coupang ?? 

Digital Giant Seeks $3.6 Billion Raise

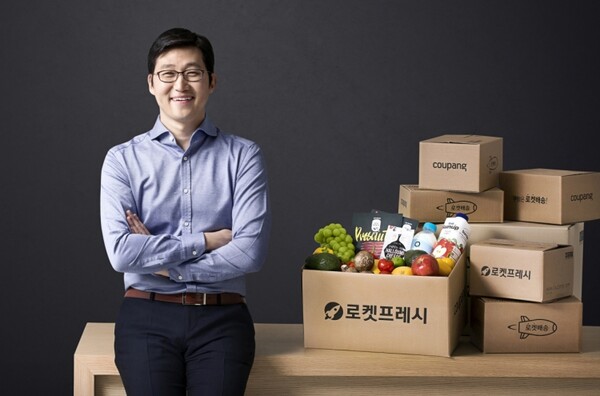
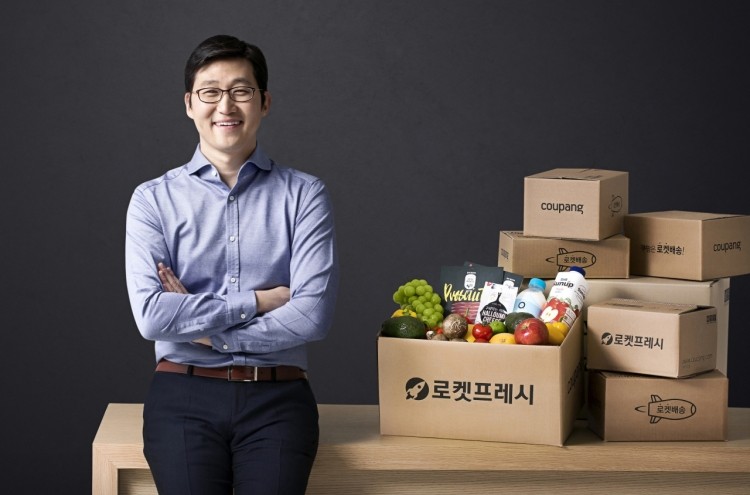
Harvard Business School drop-out Bom Suk Kim is set for one of the biggest tech IPO's for the year.  Founded in 2010, Coupang started out as a Groupon copy-cat, focusing on daily deals and has emerged into an eCommerce digital giant. The Korean born, New Englander, studied in the US, trained at Boston Consulting Group, and founded the 02138 magazine startup all before heading back to Korea to build an Amazon like "next geneartion e-commerce model".

Bom Kim @coupang

Source: Korea Daily Times

So far, the market has had a healthy reception to the listings of emerging digital giants, with AirBnB and DoorDash completing highly successful debuts.  Coupang has emerged as a pandemic and post-pandemic winner by nearly doubling its revenues to $12 billion in 2020.  As with all digital giants, the entity has an accumulated deficit of $4.12 billion as of December 2020.  Should the expected March 10th listing be successful, Korea's e-commerce darling will have a $51 billion valuation (based on $28.50 per share pricing) and emerge as one of the top 5 companies by market cap in South Korea.  The US listing will benefit Coupang with dual class voting structures, a key to a long-term mindset and one of the five tenets of building a Digital Giant. 

The Seoul headquartered company has six global offices in Beijing, Los Angeles, Seattle, Shanghai, Shenzehn, and Silicon Valley.  At the heart of Coupang is an online marketplace for merchants like Shopify, a shopping portal for consumers like Amazon, and a supply chain logistics distribution network like JD.com.  Coupang has 15,00 drivers with the largest last-mile logistics fleet in South Korea, and 100 fulfillment and logistics centers in over 30 cities. Almost 70 percent of the country lives within 6 miles of a Coupang delivery center.

Coupang has followed the digital giant model of investing for the long term with massive technology investments in machine learning and AI to deliver on personalization at scale, inventory procurement, risk management, last mile logistics, and pricing optimization.

Key investors include Softbank Vision Fund (SVF) with a 39.4 percent stake, Greenoaks Capital Partners with a 19.8 percent stake, Maverick Holdings with a 7.7 percent stake, Rosa Park Advisors with a 6 percent stake, and Black Rock with a 3.7 percent stake.  Revenue per active customer has risen from $161 in Q4 2019 to $256 in Q4 2020.  Coupang has grown active user from 9.16 million in 2018 to 11.79 million in 2019.  In 2020, Coupang reached 14.85 million active customers. Goldman Sachs, Allen & Company, JP Morgan Securities, and Citigroup Global Markets are among the nine underwriters for this IPO.

COUPANG - BUY $80

Investment relationship - NO
Individual owned - NO
Family owned- NO
Company owned - NO

The Bottom Line: This Digital Giant Dominates The Korean Market

Constellation estimates South Korea's e-commerce market to grow to $250 billion by 2026 from $129 billion in 2019.  With just a little more than one-third penetration of the 43 million South Koreans above the age of 15, Coupang has built a sizable network.  As with all Digital Giants (Get my latest book Everybody Wants To Rule The World to find out more), the business model and monetization models can expand with the investment in a a 100 year platform and strategic expansion into new offerings.  Following the lead of Asian Digital Giants (i,e. Alibaba, Baidu, JD.com, and Tencent),  expect Coupang to build on its expansion into:

  • Financial services - Coupang Pay.
  • Food delivery - Rocket Fresh

Coupang has a shot to move beyond the confines of Korea as it will need to grow its network.  Expect the IPO proceeds to be used for expansion as this emerging Digital Giant enters its next phase of growth.

Innovation & Product-led Growth Leadership Chief Experience Officer