Results

IoT Timeliness and Customer Centric Services

IoT Timeliness and Customer Centric Services
The big events by the major vendors in Autumn 2016 have been marked by the focus on using IoT to add ‘value’ in different deployments. The delivered ‘value’ usually is on the basis of the traditional IT Back Office model of using Technology for cost and efficiency improvement. However, IoT is an opportunity to create a Front Office revolution in customer interactions and satisfaction to the benefit of increased revenue at reduced sales costs. A point that under pins the much discussed transformation of the Digital Services economy.

The Salesforce annual Dreamforce continued their focus on how enterprises succeed through customers, but broader theme of using IoT connectivity and Services to change customer relationships, and business models was a dominant factor.

The technology industry, as a whole, does these events really well, and attendance remains the best way to really get a ‘feel’ for what is hot and happening even in the online age. After all if you don’t know what you don’t know it can be pretty hard to find it with a search engine! So while there can be no doubt this Autumn that the whole Technology industry gets IoT, AI and Services on the Cloud it doesn’t mean necessarily they have the same approach to Business deployment and the resulting ‘value’.

Salesforce has a reasonable claim to being a founding father of Front Office Transformation around better business engagement with the Customer., and at Dreamforce 2016 it showed. For the attendee this was as much a show to learn about Customer centric Business Models and Services, as it was a Technology company product show.

Coca Cola, General Motors, Eli Lilly, etc. all had their own sizable stands, (under their own names), to talk about their strategy in customer engagement. Most stream sessions seemed to be demonstrations by a wide variety of Salesforce customers about how they are transforming their customer interactions, (albeit with Salesforce technology). Major names in the Technology Industry, as well as new players with impressive new capabilities, were all present. 

All united by their use of Salesforce Platform(s) to deliver their capabilities resulting in something of a master class in understanding new Business Models to engage with customers. Clouds and Services may have been around for a while now, but adding IoT and AI Technologies is a further game change to up customer service levels.

Q. What is it that delights customers and is a new change factor?           

A. Timeliness…..     The fact, or quality, of being done, or occurring, at a favourable, or useful time.                        Source; Oxford English Dictionary

It is far to say that the original CRM Back Office IT systems worked in ‘computer time’, which does not correspond to the sensation of time experienced by frustrated customers, or employees. (Ever waited for the computer to find the copy of your order so you can buy the same item again?). CRM has come a long way since then, and its fair to say that Salesforce has played a leading role in its development and enjoys the respect of being thought of as a market leader.

Dreamforce as a total experience provided three big ‘strategic’ messages;

  1. In the IoT world where everyone, and everything, is part of the connected economy of Digital Services concentrate on aligning your business to the customer 
  2. Use AI to ensure that you can interpret everything from 1) smoothly and quickly to make the customer an optimized response
  3. Gaining ‘Timeliness’ of activities using 1) and 2) is an enterprise wide transformation

GM staff discussed how the customer, and not just the car, was now central to their strategy. The customer is a continuous relationship across the ownership of many cars, together with GM provided Services in areas that touch on cars and transportation. As an example earlier this year GM made an investment of $500m in Lyft citing its potential for self-driving ‘cars’ to provide ‘rides’ for its customers rather than the current individual car ownership market model.

On the next stand Eli Lilly offered the insight of their ability to support your life long ‘Wellness’ through its Services, with the role of Doctors centered around ‘event’ interactions to deal with specific health issues identified at various times. Emerson wants to look after your comfort in your home environment rather than sell you HVAC with a maintenance contract.

All of these transforming Business models rely on IoT Devices and Connectivity to provide ‘insightful’ data to trigger the ‘Timeliness’ of the interactions that provide perceived customer value. Respectively; ‘Black Box’ driving monitoring, FitBit style lifestyle activities and temperature/HVAC sensors all contribute essential data as to circumstances in ‘real time’.

The connectivity of the hundreds of devices that will make up a single personal customer profile, aggregated with the monitoring of the hundreds of thousands of devices to provide coverage across the entire customer base is a complex job. It’s not the ‘Big Data’ and BI style analysis that has become familiar from the Web. It’s a ‘Small Data’ model as individual IoT ‘event’ triggers are small data packets in a steady flow albeit in aggregate this represents a large volume.

IoT is a game change through its introduction of a new ‘Timeliness’ in reading, analyzing and orchestration reactions to events and circumstances in a time frame that can change and optimize the outcome successfully.

Salesforce, in a move that is somewhat differentiated to other Technology Players application of IoT/AI, has applied the combined capability, in association with its Cloud based Services, to the whole (complex) process of customer relationships. 

AI, better thought of as Augmented Intelligence than Artificial Intelligence, is focused on analyzing data to identify possible/optimal actions before the outcome is transacted. This is completely different approach to using ‘Intelligence’ to BI, which analyses the results of transacted Business actions.

Though announced before the event, Dreamforce was where the full impact of Salesforce AI capability called Einstein was on show for the first time. The Salesforce Einstein keynote is well worth watching to understand exactly how events are analyzed and transferred into a complex series of actions that ensure no small detail is over looked. 

Naturally all such demos will take the capability to the extreme, but that should not to deter from the significance of what Einstein is able to achieve in respect of ‘Timeliness’ of responses to Customer engagement. However, it’s not only about transforming the Front Office, and Salesforce are also increasingly seen as providing support to operate the alignment with the Back Office resources.

Looked at strategically Salesforce with its Cloud Platforms and Services architecture are well on the way to forming an Enterprise Middle Office as the operational center of managing the ‘Agile’ Enterprise; see previous blog From IT Transactions with BI to IoT Interactions with AI An argument for a ‘Mid Office’ architecture.  Add to the Dreamforce announcement that third party Services operating on the Salesforce Clouds could be remain under their own names and it seems a genuine ‘open’ platform for Services may also emerge to strengthen the Salesforce capability to act as an Enterprise Middle Office.


Addendum

Constellation Research Paper;

The Algorithm of You: How IoT Transforms Customer Experience;  by Dr Natalie Petouhoff

New C-Suite
Congratulations to the Supernova Digital Marketing Transformation Award Finalists!

Congratulations to the Supernova Digital Marketing Transformation Award Finalists!

As one of the judges for Constellation’s Supernova Awards for Digital Marketing, I had to cast my final vote a few weeks ago and it was a difficult decision with the caliber of finalists we had.  Before the winner is revealed at the SuperNova Awards dinner during next week’s Constellation Connected Enterprise, I wanted to highlight the award finalists who shared fantastic stories of Digital Marketing excellence. 


Albertsons Companies - Albertsons Companies is one of the largest food and drug retailers in the United States and in 2015 Albertsons' acquired Safeway and sought to learn from Safeway’s successful digital marketing strategy with the launch of “Just for U” mobile app and website to turn data into personalized offers for shoppers. Safeway’s 25 years of purchase data from their loyalty program provided the foundation to build algorithms to send and alert shoppers savings on the items they frequently purchased. Albertsons' marketing focused on the traditional circulars and a pilot was conducted to learn from Safeway's program. Utilizing Alation, a catalog built to search, query and collaborate on data to achieve faster, more accurate customer loyalty insights, allowed Safeway to better serve its customers by intricately and individually anticipating its customers buying behaviors, all through the help of collaborative analytics. Consequently, the marketing focus has shifted from primarily mass traditional print flyers toward a more multi-channel approach with personalized, digital advertising using the “Just for U” app and website.
 
Results achieved: 
  • Data discovery was conducted 70% faster
  • Time to execution decreased 70%
  • Personalized email resulted in 300% more redemptions than paper redemptions
  • $300,000 in additional funded redemptions
 
In four days, Albertsons Loyalty team proved the value of personalized digital marketing, delivered hundreds of thousands of dollars of additional revenue, and saw a time savings-based ROI of $30 for every $1 spent on Alation. The “Just for U” program is also rapidly being roll out across Albertsons’ full line of banner stores across the nation, to include all 2,200 stores under its umbrella.
 
 
eHarmony - eHarmony is widely recognized as a premiere relationship site with over 44 million members. Known as the scientific online dating service, it’s no surprise that eHarmony leverages data to design marketing campaigns and processes that are highly measurable. With a large budget devoted to television commercials, management wanted to find a way to utilize social media to improve targeting and re-targeting, something not possible with television. Kerianne Mellott, eHarmony’s director of social media, organized eHarmony's social media efforts with Hootsuite. Daily content was created, then scheduled and published throughout the various platforms. By reaching out to successful couples, the team activated client testimonials and wedding pictures in their digital campaigns. eHarmony used an organic and paid social media strategy to find new customers. If the content is related to a specific market, Mellott added targeting capabilities such as demographic, location, and interest to reach the most relevant audience. Based on initial performance and moderating ads, she then put promotional dollars behind various Twitter and Facebook posts. As metrics tracking was a key factor to demonstrate success eHarmony utilized Hootsuite as the publishing, scheduling, app directory and campaign performance tool.
 
Results achieved:
  • 20% more efficient in daily social media workflow, which includes an 84% response rate to community members
  • 50% increase in creative production for engaging posts and ad creative for paid campaigns.
  • 103% increase in ad spend within the last 12 months. 
  • Improved follower growth versus competition by 10%
  • Grew the overall size of the community by 24%
  • Increased community engagement by over 150%

Due to the social media transformation’s success, the team has now expanded under Mellot to include Twitter and Facebook channels for eHarmony Canada, eHarmony Español to reach the Hispanic market, and sister site, Compatible Partners. In addition, Mellott’s team also offers overall guidance for other offices in London, UK, and Sydney, Australia. They share content, campaign ideas, and best practices to adopt in their local markets.
 
 
Royal Philips - Royal Phillips produces products in diagnostic imaging, image-guided therapy, patient monitoring and health informatics. The consumer health and home care division has been a technology disruptor of “smart devices” as part of the Internet of Things (IoT) advancements. The problem that faced Philips was how to harness the hundreds of thousands of customer contacts across multiple products and touchpoints to redesign their campaign and lead management process. Then Royal Philips’ Global Vice President of Digital Blake Cahill created and launched the “Digital @ Scale” initiative, an internal strategy to transform B2B digital marketing across global business units and generate better qualified leads. They looked to the Oracle Marketing Cloud (Eloqua) as their technology platform to facilitate the transformation.
 
Results achieved:
  • More than 2 million new consumers acquired and fully engaged through digital.
  • Consumer acquisition via the website with 4% conversion into opt-ins and re-engagement rate of 35%
  • Improvement of the lead management process and creation of blueprints. In UK & Ireland, a campaign with Digital @ Scale for improved lead management processes has, within five months, generated:
    • Marketing Qualified Leads: 600
    • Pipeline Revenue: € 9M
  • The new process has given both marketing and sales clearer visibility of new leads and the status of existing leads; bringing the two departments closer together as they work through opportunities.
  • New Campaign Governance Model uptake, for the first time ever, to secure Royal Philips’ online Brand reputation.
  • New acquisition & welcome and re-engagement campaign blueprints and creation of best practices, available for all markets and business groups to support database growth and engagement:
    • New global direct marketing & privacy guidelines promoted across all markets and businesses.
    • New, mobile first, advanced emails and landing pages templates launched to speed-up digital campaign creation and boost conversion.

The Digital @ Scale initiative has since been implemented across 17 global markets in 60 countries. Cahill has led his global team to generate a significant impact on the organization, including increased revenue, pipeline, and efficiencies across all of Royal Philips’ markets and business groups. 


Seven Feathers Casino Resort - Seven Feathers Casino Resort located in Canyonville, Oregon is owned and operated by the Cow Creek Band of Umpqua Tribe. The resort’s foundation has donated $14 million to local charities and funds a full-service medical clinic for Tribal members, resort employees and their families. Due to the resort’s remote location, they utilize creative marketing promotions to attract guests. The success of these promotions is critical to the viability and future growth of the resort, which in turn sustains the local community.  In the past, the resort and the broader casino industry, has traditionally communicated with local guests through direct mail. Seven Feathers wanted to experiment with digital campaigns but recognized that both their customers and employees were not accustomed to digital offers. The resort turned to OfferCraft, a gamification platform to assist in the effort. OfferCraft makes digital incentives more fun and effective by adding game dynamics into everyday communication pieces such as emails, events social media, digital signage, etc. Seven Feathers used the platform to translate direct mail promotions into bite-sized games with personalized, interactive rewards. In a few short months, the resort’s customers not only embraced the digital offers but started to look forward to receiving them. Free game promotions posted on Facebook (not ads) has also helped to quintuple the resort’s reach organically. In addition to the external marketing benefits, the resort also utilized the gamification program internally to motivate and engage staff.  
 
Results achieved:
  • Grew daily Facebook reach by 394% with the OfferCraft gaming campaign.
  • Re-engaged over 200 inactive customers within a month.
  • All organic campaigns 

Seven Feathers has been able to transform a mainly un-digital customer base to embrace digital offers by making it fun and engaging. 
 
Please join me in extending a well-deserved congratulations to finalists Albertsons, eHarmony, Royal Phillips, and Seven Feathers Casino Resort!  I hope that you will join us at Constellation Connected Enterprise with an all-star lineup of speakers including Father of the Internet, Vint Cerf, Security and Privacy Luminary Doc Searles, Best Selling Authors Whitney Johnson, Dan Heath and more.  Visit the Constellation Connected Enterprise website here.
 
 
Marketing Transformation Chief Marketing Officer

How to Save Time and Buy the Right Enterprise Technology

How to Save Time and Buy the Right Enterprise Technology

Media Name: peoplesharinglaptop.jpg


                                              Photo: Shutterstock via TechRepublic

Shopping: It’s a Love or Hate Relationship.

Most people seem to have a love or hate relationship with the act of shopping.  It could be as simple and mundane as basic grocery shopping that happens to be a weekly necessity for those of us who believe in Maslow’s hierarchy of basic needs where food and safety are part of the foundation. On the other hand, it could be as complex and time-consuming as buying enterprise technology.

Grocery Shopping & Delivery Have Been Disrupted.

Let’s take a look at the business of grocery shopping and delivery first; everyone needs food. Choices now include Google Express and Instacart for those who’ll pay for the convenience and time savings. Even Amazon has gotten into the fray as you can see from this Recode article, Amazon is putting veteran leaders in charge of its’s big grocery delivery plans.”  If two heavyweight technology companies like Google and Amazon are investing in this, they clearly see an opportunity to fulfill unmet needs in this winner-takes-all market as R “Ray” Wang, Constellation Research’s chairman often states.

The Art of Enterprise Technology Shopping.

Now, let’s consider the art of enterprise technology shopping. Once you narrow down your options to the most likely type of technology that’s going to help you solve your business challenge, you still need to vet, procure, and then implement that technology and hope that you made the right judgement call. Careers can often be made or dismantled by this choice.

Your technology assessment could take anywhere from a few weeks to 18 months or more, depending upon your business criteria, the number of stakeholders involved, your organization’s business culture, and the complexity of the business issue that you’re trying to address. That’s precisely why we set up the Constellation ShortList™ program to help save time for buyers of large-scale technology, by making these insights freely available as a starting guide to the enterprise technology buying journey.

Technology Buyer’s Rights: How to Shorten Your Enterprise Technology Buying Cycle.

We’re releasing 40 Constellation ShortLists in our Research Library before the end of 2016. Take at these blog posts here, here, here, and here for more details on what’s been released already. That’s just for starters. Here's the full list of Constellation ShortList categories, if you're curious.

Why struggle to build a list of top contenders when you can trim that effort and start your buying process with a Constellation ShortList. You can then take consult with experts like our Constellation analysts to find out which technologies are going to be the most suitable for your business. As strategic advisors, our analysts cover a wide range of industries, including telecommunications, healthcare/medical, automotive, retail, government, manufacturing, finance/insurance, media/advertising, hospitality, and technology.

Enterprise technology shopping can be a challenge. Making the right decisions are crucial to organizational growth, and it’s not worth the aggravation to take an uneducated guess. If you take a look at R “Ray” Wang’s “Enterprise cloud buyers bill of rights,” you’ll get a sense of why he, and in fact, our entire analyst team, take your needs as a buyer seriously. 

Don’t Take our Word for It. Find Out Why It Matters.

It’s been thrilling to see the enthusiasm in the market, and we’re honored with early recognition from Ludovic Leforestier, one of the co-founders of the Institute of Industry Analyst Relations (IIAR) who is also the Director of Thought Leadership and Analyst Relations at BearingPoint. For those of you who don’t know about IIAR, it’s an independent organization that weighs in on perceptions of analyst firms on behalf of analyst relations professionals. Find out what Leforestier had to say about how Constellation’s disrupting the analyst industry with his post, "Constellation and the curse of the quadrant”. 

Constellation ShortLists Accelerate the Enterprise Technology Buying Journey.

Effective technology shopping requires forethought, planning, and expert guidance, so that you identify the pitfalls to avoid and the best practices to leverage. To streamline your efforts and maximize your business outcomes, that’s where direct advice from Constellation’s seasoned analysts can save you time and aggravation, in identifying the right technology for your business.

To get advice on matters like this when it counts and at the right time and get connected in an exclusive community for innovative leaders, a solid first step is to join the Constellation Executive Network. By joining you’ll get access to disruptive technology research, expert advice, analyst dialogues on trending topics, business insights, events, and more. 


Learn More about the Constellation Executive Network

Chief Customer Officer Chief Digital Officer Chief Executive Officer Chief Financial Officer Chief Information Officer Chief Marketing Officer Chief People Officer Chief Procurement Officer Chief Revenue Officer Chief Supply Chain Officer

SaaS Land Grab Ignites as SAP Makes Human Capital Management Solutions Available on Microsoft Azure

SaaS Land Grab Ignites as SAP Makes Human Capital Management Solutions Available on Microsoft Azure

In a follow up move to its announced partnership from May this year, Microsoft and SAP extended their partnership to the HR area, something that could have been expected, but was not necessarily a given when considering the complex multi-vendor landscape both on the SaaS and the IaaS landscape.


But let’s dissect the press release in our customary style, it can be found here:
REDMOND, Wash. – Oct. 18, 2016 – Microsoft Corp. on Tuesday announced an expanded partnership with SAP to provide public cloud services for the SAP® SuccessFactors® HCM Suite. SAP will make its cloud-based human capital management solutions available on Microsoft Azure over the next five years. This is SAP’s first move to supplement its own infrastructure and operate SAP SuccessFactors solutions in a third-party public cloud, recognizing the experience both companies have in supporting global enterprise clients. With the addition of Azure, SAP has a trusted, global cloud and a powerful data platform to help it drive companies’ human resources transformation, and the potential to dramatically improve business outcomes.

MyPOV – Good summary, correctly referring to an ‘expanded’ partnership. The timeframe of five years seems to be pretty long, but both vendors have been found to be conservative, when it comes to timelines. The concern is that 5 years is the ‘half time’ of a good architecture, so whatever SAP will use as the base for the cutoff to support Azure – it will take some time and the platform may have some years of age already. But that number also reflect a medium term commitment of both vendors to each other. But you never know how long this will take - getting demo environments in Q1 of 2017 is a good start. Good also to see the focus on global, where Azure is doing well and that is crucial from a data residency perspective for many customers.  

 
“Microsoft and SAP share a commitment to empowering digital transformation across every aspect of business,” said Judson Althoff, executive vice president, Worldwide Commercial Business at Microsoft. “The combination of SAP’s market-leading, innovative human capital management solutions with Microsoft’s intelligent cloud will equip companies around the world to help maximize the potential and skills of their most valuable asset, their people.”

MyPOV – Good statement of new on board head of worldwide commercial business, Judson Althoff.

SAP will have significant additional capacity to run operational workloads of SAP SuccessFactors solutions on Azure, beginning with demo environments, to support its continuing client user growth. Azure provides enterprise-grade security, an open developer platform and advanced data services that organizations of all kinds can use to innovate and grow. With nearly 90 percent of the Fortune 500 as customers, the Microsoft Cloud is offered in more worldwide datacenter regions than any other major cloud provider.


MyPOV – Good to learn something about the start – and its conservative – with demo environments. Demo environments are a typical first use case for similar exercises, as they are not critical from a production grade perspective. But certainly critical for the success of a vendor, and with rising demo needs and demand (e.g. from SAP SuccessFactors Partner for Profit program) – it is key for SAP to find a cheap, elastic demo platform. At the same time the create, demo and throw away nature of demo environments give Microsoft and SAP plenty of chances to learn to setup these environments, something important for the next step that usually is development and test (see e.g. where Workday is with IBM here) and then off to the ultimate goal – production. Again rightfully the press release quotes Microsoft’s coverage of large enterprises, when they are comfortable to run Office on a IaaS, they will most likely be comfortable to run HR systems on the same IaaS, too. 

“SAP SuccessFactors is the fastest growing core HR solution, and offers an unmatched depth and breadth across the entire HCM suite, of any vendor in the industry,” said Mike Ettling, president of SAP SuccessFactors. “We’ve seen exponential growth in the past two years, with 42 million users now benefiting from our market-leading solutions. In selecting Azure, we will be able to expand our reach even further, with the reliability that is required of these mission-critical applications, and continue to innovate and enhance services to meet client needs across additional environments.”
MyPOV – Good quote of Ettling, touting growth of SuccessFactors. And one of the first areas where vendors feel growth pain is… demo systems and the pieces are adding up here. Demo systems and sand boxes are vital tools for vendors to ramp up their pipeline, something that SAP SuccessFactors is working hard to do at the moment, especially when it is done via the partner channel (also the case). 
This deal builds on the longstanding partnership between Microsoft and SAP, including integrations between Office 365 and SAP SuccessFactors HCM Suite, as well as SAP Fieldglass® Vendor Management System, SAP Ariba® and Concur® solutions. The Microsoft and SAP partnership also includes broad support for the SAP HANA® platform on Azure to enable companies to deliver mission-critical applications and data analytics from the cloud. Microsoft recently announced the general availability of Azure large instances, hardware configurations specifically designed for the largest and most demanding SAP workloads. SAP now enables its customers to build and deploy custom mobile hybrid SAP Fiori® apps on SAP HANA Cloud Platform that can be managed, deployed and protected with Microsoft Intune.
MyPOV – A ‘well we have been doing this since a longtime’ paragraph – that is often found in press releases, when vendors want to show continuity, experience working together and generally make the partnership look like a big deal. Wasn’t necessary in my view, as he first pick of an IaaS by SAP SuccessFactors would be enough of headlines, but so be it. The HANA statement is key, as SuccessFactors is under the ‘Hasso Mandate’ of moving to HANA, and if Azure had not been able to run HANA, some observers would have questioned it… but that’s not the case with Azure’s recent commitment to large memory instances… and that is essential to capture long term SAP load to move to Azure. Once the SAP customers move, they most likely will be on HANA based systems on premises, or move to HANA based systems in the cloud, Microsoft wants to make it a move to Azure. And of course Microsoft has a lot more to offer to SAP and other ISVs, beyond 'just' using Azure. 

Overall MyPOV

We live in the ‘age of the load landgrab’ – which is the fight of IaaS providers like Microsoft Azure here, to capture on premises load (here from SAP). That gets overlaid by SaaS load that is looking for a new home due to a generational or platform update (here SuccessFactors moving to HANA and maybe some more things) and fueled by even large enterprise vendors like SAP, to not put up the CAPEX needed for large datacenter / IaaS rollouts. On the flipside IaaS providers (here Microsoft Azure) are more than willing to put in the CAPEX as they are bound for growth no matter what at the moment and any uniform load from on premises software or SaaS software is highly welcome, in comparison to one customer at a time projects. And SAP signaled already at Sapphire this year that its own IaaS ambitions have been scaled down (see my blog here), as the partnership with Azure was already announced in May, this is the conjugation of this very partnership towards SAP SuccessFactors load.

For customers this is generally good news. Instead of waiting for their enterprise software vendor to figure out IaaS (or not), they can move to the cloud with the help of an IaaS provider who runs cloud infrastructure for a living. An alignment with other load of the enterprise will be of course welcome, as too much fragmentation across too many IaaS provider can quickly become a headache from a performance, compliance and commercial perspective. The good news for here is that most enterprises will be in Azure due to Office gravitas one way or the other. On the concern side customers need to pay more attention now to their SaaS vendors not picking up dependencies on specific cloud infrastructures – as it will limit future portability. For SaaS vendors eager to expand their functionality e.g. in the areas of Machine Learning and AI, this maybe a tradeoff they may be happy to take in the short term, but for customers it is something they may not want to live with middle or long term. So customers need to pay attention to the IaaS capability uptake of your SaaS vendors, in this case e.g. SuccessFactors using capabilities that only Azure offers.
 
It also marks an inflection point that a 'born in the cloud' load like SuccessFactors is looking for its next 'home' - no longer in its own cloud infrastructure, but looking for a stand alone IaaS partner, in this case Azure. Those options were not around for the early SaaS pioneers, who all sit on aging, often proprietary or now 'frenemy' platforms, moving to a partner's IaaS should free up CAPEX resources and ultimately provide a better return of R&D to SaaS vendors making the move, which should translate either in (higher) profitability and / or more functionality in the product. Both are positive developments for a SaaS vendor's customers.

But for now good to see the continuity of the Microsoft / SAP partnership, at the moment it’s a win / win / win for customers who get more live software demos and likely more sand boxes (always ask for them), Microsoft gets a shot at more SAP SuccessFactors load, starting with demo systems and SAP SuccessFactors gets a lot of demo environments and a proven IaaS partner (that SAP overall had chosen already before).

Stay tuned for more on this and more enterprise vendor / SaaS player with IaaS player partnerships, below are a few of the most recent and prominent ones.
Future of Work Chief Information Officer

Bridging Digital and Analog with Digital Experience Integrated Platforms

Bridging Digital and Analog with Digital Experience Integrated Platforms

As digital transformation efforts take center stage, the requirements for the convergence of digital and analog disciplines drastically increase. Ad tech, artificial intelligence (AI), content and data management, Internet of Things (IoT), and mass personalization at scale – all of these new and changing technologies require companies to adopt digital experience integrated solutions to effectively implement disruptive programs to shake up their industries.

Today, Constellation published a Constellation ShortList™ for Digital Experience Integrated Platforms. While no complete solution exists today, it aims to catalogue these offerings as they emerge and become business-model platforms for organizations. Here are the companies that made the Constellation ShortList:

  • Acquia
  • Adobe
  • Demandware (by Salesforce)
  • Episerver
  • IBM
  • Oracle
  • Sitecore

Constellation advises early adopters using disruptive technologies on how to achieve business model transformation. Products and services named to this Constellation ShortList meet the threshold criteria for each category as determined by Constellation Research through client inquiries, partner conversations, customer references, vendor selection projects, market share and internal research.

Additional lists released today include:

Test out the Constellation ShortList, and when you’re ready, contact us to connect with authoring analyst who can then personalize the vendor selection process for you.


Constellation ShortList™ for Field Service Management

Constellation ShortList™ for Field Service Management

Constellation has announced the Constellation ShortList vendors in Field Service Management which provides the best capabilities to help employees serve customers. Field customer service occurs when resources or services are deployed onsite at a client. Field service management software enables companies to be flexible and nimble when providing service. These offerings are great at detecting problems before having to send someone to repair or fix a customer’s issue. In the event they must send someone, they can communicate in real-time with customers, provide on-site information about products and repair issues while offering relevant and timely service.

These offerings help companies improve their operational efficiencies by optimizing work-order routing and technician scheduling, which results in quicker resolution of issues. Analytics used in field services often optimize when services are deployed and how assets are tied to deployment of resources. They have advanced scheduling systems that let the customer know when the technician or field-service employee will arrive within a reasonable window of time. Helping provide an excellent customer experience is the most important aspect of field service management solutions.

The Constellation ShortList presents vendors in different categories of the market relevant to early adopters. In addition, products included in this document meet the threshold criteria for this category as determined by Constellation Research.  This Constellation ShortList of vendors for a market category is compiled through conversations with early adopter clients, independent analysis, and briefings with vendors and partners.

Constellation considers the following criteria for these solutions:

  • Good diagnostics prior to rolling out the truck
  • Resource management
  • Case management
  • Communication with the customer on the status of the technician’s arrival
  • Scheduling
  • Resource allocation
  • Inventory optimization
  • Mobile enablement.

Constellation evaluates over 25 solutions categorized in this market. This Constellation ShortList is determined by client inquiries, partner conversations, vendor selection projects, market share and internal research. These are the best-of-breed vendors that provide applications and services without bundling into another platform:

  • IFS
  • Oracle Field Service Cloud (formerly TOA Technologies)
  •  ServiceMax
  • ClickSoftware
  • PTC
  • SAP
  • Vertical Solutions.

For more information on the short lists, please see the Constellation Research site.

@Drnatalie Petouhoff, VP and Principal Analyst, Constellation Research, Covering Customer-Facing Applications

Share

Next-Generation Customer Experience Chief Customer Officer

Constellation ShortList™ Customer Service and Contact Center Software

Constellation ShortList™ Customer Service and Contact Center Software

Constellation Research is launching a new program, and I’m happy to share that the vendors that have been listed on the Constellation ShortList™ for Customer Service and Contact Center Software. The program offers buyers of technology a list of offerings to consider in their pursuit of digital transformation to provide the best capabilities to drive leading customer service.

The Constellation ShortList presents vendors in different categories of the market relevant to early adopters. In addition, products included in this document meet the threshold criteria for this category as determined by Constellation Research. This Constellation ShortList of vendors for a market category is compiled through conversations with early adopter clients, independent analysis, and briefings with vendors and partners.

Customer service and contact center software helps solve customer challenges faster by offering the right tools and support, regardless of channel or device (e.g., phone, tablet, email, chat, text, website, Facebook, other social networks). These offerings can effectively manage inbound communication for increased first-contact resolution, in addition to providing co-browse capabilities to allow visual communication for quicker query resolution. Additionally, they can support the reduction of cart abandonment and increase customer satisfaction with in-cart assistance. 

This type of software provides personalized care through the use of analytics, offering insight into customers’ behaviors for relevant, contextualized service that can predict future needs. Companies can identify new opportunities by integrating these customer insights into their companies’ innovation processes. The software also creates seamless, online experiences with a knowledge base that learns from every interaction, enabling them to match content to consumer intent, which results in higher conversion rates. The top solutions also provide smart customer self-service, allowing customers to help themselves by fostering peer-to-peer support communities and eliminating the need to reach out to the contact center.

Constellation considers the following key criteria for these solutions: Self-service capabilities, case management, natural language processing for knowledge management and search, omni-channel and device customer journeys, mobile customer service and self service, queuing and routing, workforce optimization, predictive and prescriptive rules and advice, next-best action, natural scripting, customer feedback collection capabilities, IVR, visual IVR, inventory optimization, mobile enablement, social and digital engagement simplified user design (UX/UI), reporting and customer analytics, integration to IoT (Internet of Things) platforms and devices, data dashboard and data visualization.

Each Constellation ShortList evaluation will be updated every 90 days as needed. Constellation clients may work with the analyst and research team to conduct a more thorough discussion of this ShortList. Constellation can also provide guidance in vendor selection and contract negotiation.

ShortList is determined by client inquiries, partner conversations, customer references, vendor selection projects, market share and internal research. The Shortlist includes:

• Aspect 
• Avaya
• Cisco
• Genesys
• inContact
• Interactive Intelligence
• Oracle
• Salesforce
• Verint. 

For more information about the ShortList, please visit the Constellation Research site.

@DrNatalie Petouhoff, VP and Principal Analyst, Constellation Research, Covering Customer Facing Applications.

Next-Generation Customer Experience Chief Customer Officer

Zenefits Z2 Event Report

Zenefits Z2 Event Report

I attended Zenefits’ Z2 event, which was also its first user conference. Held at the Palace Hotel in San Francisco, on October 18th the event was a small, efficient affair, with about 700 attendees present. 

 
So take a look at my musings on the event here: (if the video doesn’t show up, check here)
 
(Apologies for bad audio and even loss of video - the Palace Wifi did not perform well here.)
 
No time to watch – here is the 1-2 slide condensation (if the slide doesn’t show up, check here):
 
 
Want to read on? Here you go: Always tough to pick the takeaways – but here are my Top 3:

Zenefits has left the troubles of the past – behind. The recent troubled past of Zenefits seems to have made its transition to the history books, clients and prospects present at the event were not concerned about the colorful, recent past of the vendor. That’s a major step forward and allows Zenefits to move on, and the vendor did exactly that with the release of Z2, the 2nd release of the Zenefits system.

New capabilities in Z2 – Zenefits has given its system a new UI, that feels modern and simple to use, something crucial for its customer base of very small businesses of under 50, sweetspot is around 100 employees (but of course scales up and Zenefits has many larger customers, too). These businesses have no HR professional and the ‘HR person’ is a multitasker, who needs an easy to use software, that can be used easily and that has tons of inbuilt automation to avoid them having to spend too much time on HR matters. The 21st century workforce is mobile and Zenefits supports iOS and Android for all key processes, kudos to support both platforms, even much larger vendors based in Silicon Valley have stepped into the ‘iOS for all trap’, that doesn’t’ work for HR in the era of BYOD. The focus on core HR processes and onboarding is no surprise. And a marketplace with over 17 partners makes it easy to use Zenefits as the leading system to integrate into a wide range of productivity, expenses, performance management, payroll accounting, engagement and more vendors. Close to its core competency, Zenefits has improved the benefits enrollment and selection experience.

Zenefits Payroll is here – starting with California – To no surprise, Zenefits unveiled its new Payroll offering, at the moment only working for California. But 9 other states are planned in the coming quarters. It’s a V1 product in terms of scope and capabilities (e.g. garnishments need to be handled manually when it comes to payments) – but it’s a good start for Zenefits. Customers are very positive on Zenefits Payroll capabilities, another indicator how much integration concerns bog down even part time HR professionals.

MyPOV

A good event and a very good first user conference for Zenefits, that has left the troubles of the past behind and has morphed from its benefits origins all the way to become a small HR suite of products for very SMB. It still offers product capabilities for free, the ‘price list’ fits on one slide, but it also is adding products that have a seat cost / employer cost, e.g. Payroll. That’s a good development in my view, as it takes away the competitive / disruptive relationship to the rest of the industry, which Zenefits leadership has rightfully identified as necessary partners, to have a broader scope of HCM automation for is customers (thanks to the marketplace). But Zenefits doesn’t’ shy away from services either, the new HR Advisor capability, where the SMB HR practitioner can talk to a Zenefits expert, is a valuable offering.

On the concern side, Zenefits has lost some time to restart its offering. In the meantime, the competition has not stood still, and has equally simplified its products (e.g. Paychex) or extended its footprint (e.g. partner Gusto). And payroll is crucial to get right for enterprises small and large. A bad payroll run derails equally all work at an enterprise of any size. So expanding payroll footprint should be a priority for Zenefits.

But overall a good launch event and a good first user conference for Zenefits the vendor to watch and consider when you are a very small business. Stay tuned.


Want to learn more? Checkout the Storify collection below (if it doesn’t show up – check here).


Future of Work Chief People Officer

Constellation's AstroChart For Business Trends, Q4 2016

Constellation's AstroChart For Business Trends, Q4 2016

Move Beyond The Hype In Business Trend Cycles

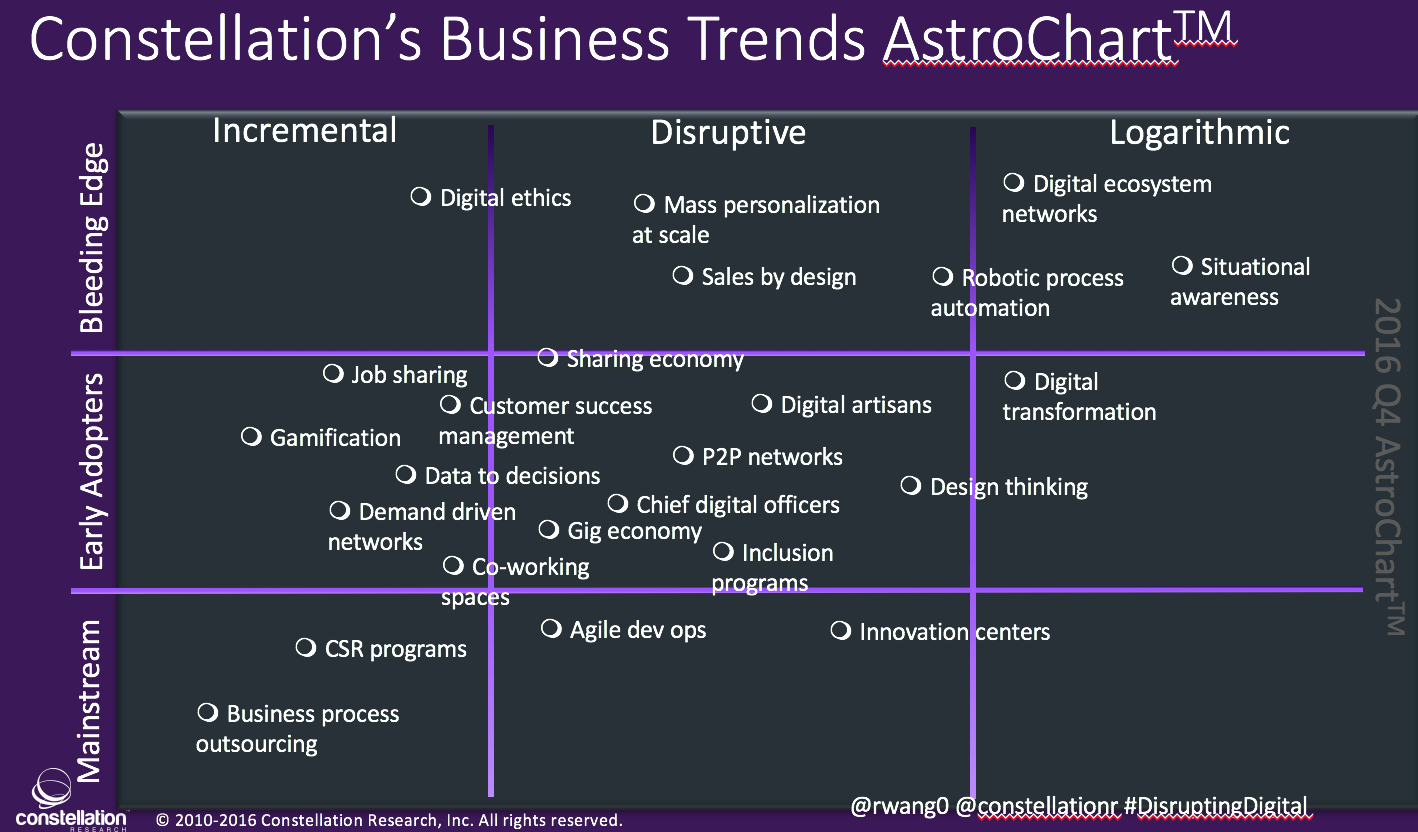
Constellation’s AstroChartTM for Business Trends provides market leaders and fast followers a visual guide to business trends and their adoption.  The vertical access rates adoption from mainstream to early adopters to bleeding edge.  The horizontal access estimates the impact on an organization’s business model. from incremental to disruptive to logarithmic.   The intent of an AstroChartTM is to move beyond both the hype and constraints of a 2 x 2 grid.

From over one hundred interviews with boards and CXO’s, Constellation has brought together an AstroChart of how various business trends play out.  These trends will be updated every 180 days or sooner but reflect what’s placed into our Futurist Framework and PESTEL model as well as various inquiries and primary research.

Figure 1. Constellation’s AstroChartTM for Business Trends Shows What’s Hot In the Boardroom

Constellation's Business Trends AstroChart Q4 2016

Nine Categories Show The Power Of Boardroom Trends

Analysis of the nine categories provides input into strategic planning for Market Leaders and Fast Followers.  The nine categories include:

  1. Bleeding edge – Logarithmic.  Brand new startups and innovation teams are building to digital ecosystem networks and situational awareness.
  2. Bleeding edge – Disruptive.  Mass personalization, robotic process automation, and sales by design drive this category.
  3. Bleeding edge – Incremental.  Digital ethics plays a role among early pioneers.
  4. Early adopter – Logarithmic. Digital transformation remains high on this list in the search for growth and the avoidance of digital disruption.
  5. Early adopter – Disruptive.   The majority of trends currently are in the early adopter category and include sharing economy, digital artisans, P2p networks, design thinking, chief digital officers, gig economy, and inclusion programs.
  6. Early adopter – Incremental.  Customer success management, job sharing, gamification, co-working spaces, demand driven networks, and gamification show incremental improvement as they fall from being disruptive to incremental.
  7. Mainstream – Logarithmic.   There are no topic areas here but total quality management from the 1980’s and Six Sigma from the 1990’s would be an example.
  8. Mainstream – Disruptive.  Innovation centers and agile dev ops are now mainstream adoption and disruptive.
  9. Mainstream – Incremental.  CSR programs and business process outsourcing remain mainstays and mainstream incremental.

The Bottom Line: Plan Out Corporate Strategy With The Constellation’s AstroChartTM for Business Trends

Stay abreast of the latest business trends by adoption rates and business model impact using the Constellation’s AstroChartTM for Business Trends.  Use the AstroChartTM to develop your overall board room strategy and to benchmark your organization’s adoption.   Constellation observes the following:

  1. Organizations should take an assessment of their board room priorities and use the AstroChart to determine portfolio management.
  2. Market leaders tend to bet 50% of their portfolio on disruptive projects
  3. Market leaders tend to bet 30% of their portfolio on bleeding edge projects
  4. Fast followers tend to bet 80% of their portfolio on early adopter projects
  5. Logarithmic – bleeding edge bets require a very informed or founder driven board.

Your POV.

Ready to take advantage of the Constellation’s AstroChartTM for business trends?  How have you built out your strategic investment map?  Learn how non-digital organizations can apply a business trends roadmap and the PESTEL futurist framework to disrupt digital businesses in the best-selling Harvard Business Review Press book Disrupting Digital. 

Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org.

Please let us know if you need help with your Digital Business transformation efforts. Here’s how we can assist:

  • Developing your digital business strategy
  • Connecting with other pioneers
  • Sharing best practices
  • Vendor selection
  • Implementation partner selection
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing


Data to Decisions Digital Safety, Privacy & Cybersecurity Future of Work Marketing Transformation Matrix Commerce New C-Suite Next-Generation Customer Experience Tech Optimization Innovation & Product-led Growth Leadership Chief Customer Officer Chief Digital Officer Chief Executive Officer Chief Financial Officer Chief Information Officer Chief Marketing Officer Chief People Officer Chief Procurement Officer Chief Revenue Officer Chief Supply Chain Officer Chief Experience Officer

Oracle OpenWorld - The HCM Perspective

Oracle OpenWorld - The HCM Perspective

We had the opportunity to attend Oracle’s OpenWorld mega event a few weeks ago, a busy fall schedule has not allowed us to sum up the key findings, though we posted them on YouTube (see here) and Slideshare (see here) right away. Let’s look at the HCM side of the Oracle offering. As usual the HCM sessions were held at the Palace Hotel, off from Moscone, and for the first time, the number of users attending outnumbered the number of prospects.


Tough to pick the top 3 takeaways – but here you go:

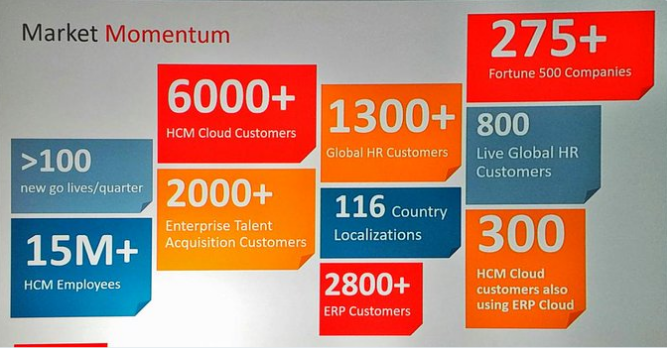
Oracle HCM is … growing fast – Chris Leone walked through the first 6 years of Oracle HCM, and what was humble beginnings back in 2010 (20 Global HR customers, 30 Talent customers), has developed over the last 6 years into what is now one of the large, if not the largest part of the worldwide HCM market share for SaaS based HCM (with 6000+ HCM Cloud customers, 1300+ Global HR customers (800 live), and 2000+ Talent Acquisition customers. Over 100+ go lives pro quarter and 15M+ HCM employees are other indicators that the substantial investment (about 2500 employees in products – excluding Peoplesoft) is paying off for Oracle. With an equally substantial sales and marketing investment – the next 12 months will have to show if Oracle can move out of the Top 3 in the HCM market, and become a clear leader in customer adoption. For now, you can still slice and dice the Top 3 (including SAP and Workday) as they please. 


Oracle HCM Market Momentum


New Talent Acquisition in the works – For the longest time Oracle HCM product leadership has shied away from touching the old Taleo functionality. Along the lines ‘the world doesn’t need another / a new recruiting’ product, Oracle provided integration and worked around the regular beat from Workday on the ‘single’ platform, the power of one etc. And one can make the point that in the SaaS world integration is the vendor’s challenge, not the customers, but the concern on integration risk, cost and overall speed of innovation will always be brought up. So the really big news from OpenWorld is, that Oracle is building new Talent Acquisition capabilities, with a focus on functionality for customers using the suite first. This is big news as it takes out the ‘Jockey Club’ that Taleo was for Oracle HCM. Anyone who does not know, visit Las Vegas and watch from the Bellagio hotel toward the Cosmopolitan – you get it. Obviously Oracle has not shared much more details, I’d expect to learn more at next year’s HCM World. But truly an important step to bring together all of HCM automation for Oracle customers and prospects. 
 
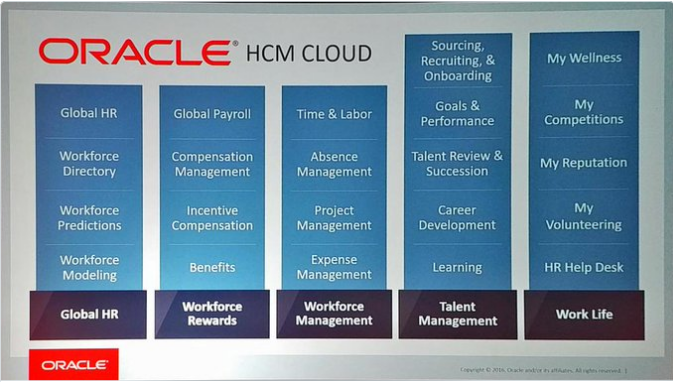
Oracle HCM Footprint
 

Adaptive Intelligence – for HCM - We are in the fall of AI where no conference cannot have a stab at Artificial Intelligence, Oracle has been no exception announcing its suite of Adaptive Intelligence applications, one of them being in HCM. Not surprisingly the functional content of the HCM adaptive intelligence application will be on …. Talent Acquisition. And that all makes sense, when you rebuild your Talent Acquisition capabilities (see above) – you want to give customers a reason to move, and build on the latest and greatest capabilities…. So for a 2017 product that need to have an AI / ML play. But its early days for all of Adaptive Intelligence, for now Oracle is ‘just’ rounding up what it had in its portfolio from the Datalogix et al acquisitions (see the take of my colleague Doug Henschen here) and coming out of the gate with that. The HCM Adaptive Intelligence application is coming later, in 2017.
 

MyPOV

A very quiet OpenWorld from the HCM team, the strategy reminds me of Teddy Roosevelt’s ‘speak softly and carry a big stick’ – in the sense of not making big announcements, but building big things. Very un-Oracleish and maybe a first step of Oracle becoming a more gentle, friendly, easy to do business with Oracle. That will be a substantial change in DNA, but given the investment Oracle is doing in R&D in general and in HCM in specific, a little change. Starting in HCM, given the tender nature of relations in the industry is certainly a good first step. But overall kudos to Oracle to start addressing the multi-year ‘elephant (named Taleo) in the room’, adding an AI wrinkle with ‘Adaptive Intelligence’ – so it will be interesting to learn more in 2017. Stay tuned.
 

The Storify of the Hurd keynote can be found here - Ellison's is here, the Day 2 keynote can be found here. Don't miss the HCM Keynote Storify below, or here

 
Recent blog posts on Oracle:
  • First Take - Early Oracle OpenWorld 2016 Keynotes - read here
  • Event Preview - Oracle OpenWorld 2016 - What to expect, what to watch for ... will IaaS start Clicking? - read here
  • Market Move - Oracle acquires NetSuite - Oddly consolidation means more options for customers - read here
  • News Analysis - Oracle Unveils Suite of Breakthrough Services.. or short: Oracle Cloud Machine - read here
  • Progress Report - Oracle Cloud - More ready than ever, now needs adoption - read here
  • Event Report - Oracle Openworld 2015 - Top 3 Takeaways, Top 3 Positives & Concerns - read here
  • News Analysis - Quick Take on all 22 press releases of Oracle OpenWorld Day #1 - #3 - read here
  • First Take - Oracle OpenWorld - Day 1 Keynote - Top 3 Takeaways - read here
  • Event Preview - Oracle Openworld - watch here

Future of Work / HCM / SaaS research:
  • Event Report - Oracle HCM World - Innovation around the Core - read here
  • Event Report - Oracle HCM World - Full Steam ahead, a Learning surprise and potential growth challenges - read here
  • First Take - Oracle HCM World Day #1 Keynote - off to a good start - read here
  • Progress Report - Oracle HCM gathers momentum - now it needs to build on that - read here
  • Oracle pushes modern HR - there is more than technology - read here. (Takeaways from the recent HCMWorld conference).
  • Why Applications Unlimited is good a good strategy for Oracle customers and Oracle - read here.

Also worth a look for the full picture
  • Event Report - Oracle PaaS Event - 6 PaaS Services become available, many more announced - read here
  • Progress Report - Oracle Cloud makes progress - but key work remains in the cellar - read here
  • News Analysis - Oracle discovers the power of the two socket server - or: A pivot that wasn't one - TCO still rules - read here
  • Market Move - Oracle buys Datalogix - moves more into DaaS - read here
  • Event Report - Oracle Openworld - Oracle's vision and remaining work become clear - they are both big - read here
  • Constellation Research Video Takeaways of Oracle Openworld 2014 - watch here
  • Is it all coming together for Oracle in 2014? Read here
  • From the fences - Oracle AR Meeting takeaways - read here (this was the last analyst meeting in spring 2013)
  • Takeaways from Oracle CloudWorld LA - read here (this was one of the first cloud world events overall, in January 2013)

And if you want to read more of my findings on Oracle technology - I suggest:
  • Progress Report - Good cloud progress at Oracle and a two step program - read here.
  • Oracle integrates products to create its Foundation for Cloud Applications - read here.
  • Java grows up to the enterprise - read here.
  • 1st take - Oracle in memory option for its database - very organic - read here.
  • Oracle 12c makes the database elastic - read here.
  • How the cloud can make the unlikeliest bedfellows - read here.
  • Act I - Oracle and Microsoft partner for the cloud - read here.
  • Act II - The cloud changes everything - Oracle and Salesforce.com - read here.
  • Act III - The cloud changes everything - Oracle and Netsuite with a touch of Deloitte - read here


Want to learn more? Checkout the Storify collection below (if it doesn’t show up – check here). Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my YouTube channel here.
Future of Work Innovation & Product-led Growth Event Report Executive Events Chief People Officer