Results

Report: Software Challenging the Status Quo in the Way People Work

Report: Software Challenging the Status Quo in the Way People Work

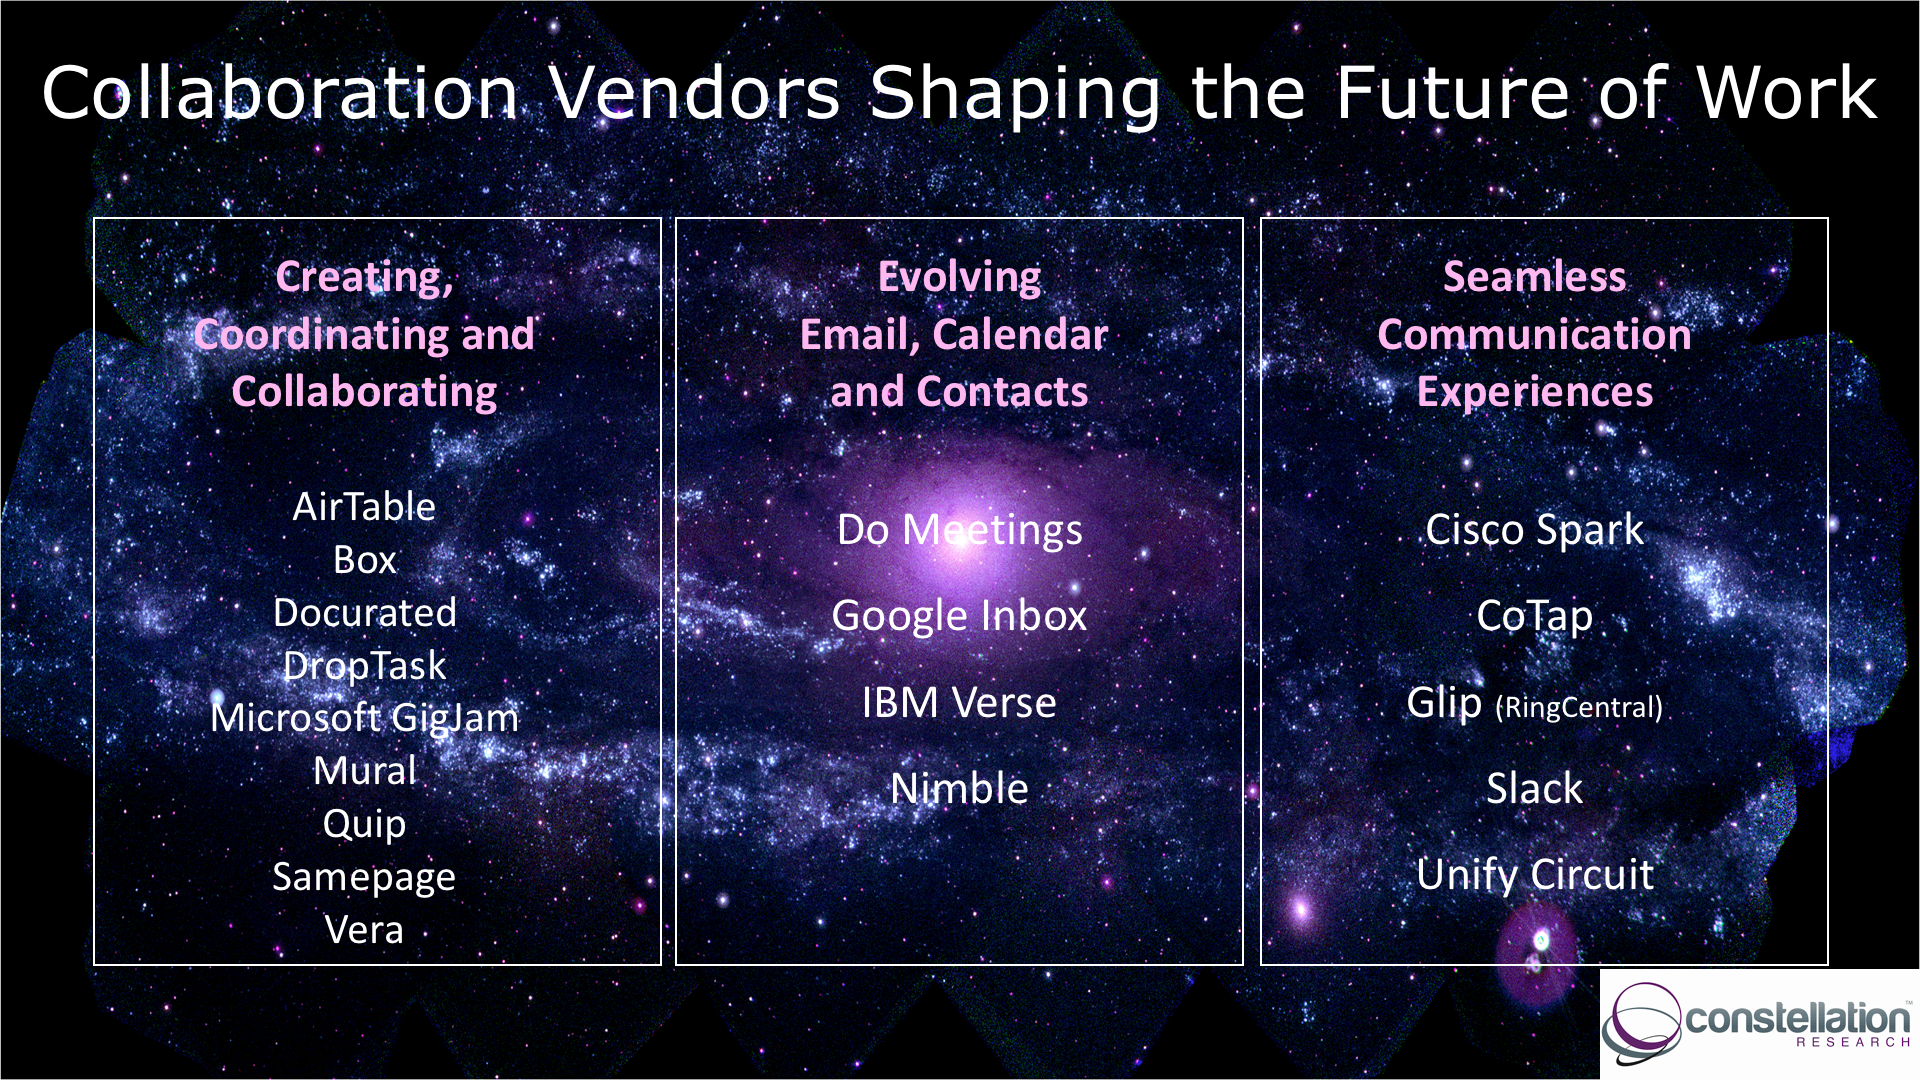
One of my favourite parts of my job is meeting with collaboration software vendors to discuss with them how they are going to improve, or in the rare case change, the way people work. I have hundreds of briefings each year, some with billion dollar software companies and others with brand new startups. To organize all their products, I've created three categories:

  • Evolving Email, Calendar and Contacts
  • Creating, Coordinating and Collaborating
  • Seamless Communication Experiences

In my new report, Collaboration Vendors Shaping the Future of Work, I've highlighted 18 products that show vision in improving the way people get work done. These companies were chosen based on the number of inquiries from Constellation Research customers, information gathered via company and product briefings, customer references stories, growth in partner ecosystem, and breadth of coverage and momentum in the press. Not all of these products will become market leaders. Some may fade away, some may be acquired, some may rise to the top... but all of them deserve accolades for attempting to shape the future of work. 

In the report we take a quick look at each product, discuss what they are doing and list a few of their competitors. Of course no list is ever complete. What is your favourite new product that is doing something a little bit different to make it stand out from the crowd?

Click here to purchase: Collaboration Vendors Shaping the Future of Work.


Future of Work Marketing Transformation Next-Generation Customer Experience Revenue & Growth Effectiveness Data to Decisions Innovation & Product-led Growth New C-Suite Digital Safety, Privacy & Cybersecurity Tech Optimization Chief Marketing Officer Chief People Officer Chief Revenue Officer Chief Experience Officer

The IoT Market – 2015 laid down the direction for 2016 Massive numbers of well-financed IoT startups are attacking current market leaders

The IoT Market – 2015 laid down the direction for 2016 Massive numbers of well-financed IoT startups are attacking current market leaders

Back in January it seemed as though 2015 would be the year of Hype for the Internet of Things, as industry pundits competed to claim how many billions of IoT devices there would be in the coming years. At the end of 2015 many people in IT can state that for them there was no sign of IoT happening, and if you work in the IT department that’s arguably true. IoT is happening, and just like the Internet after the 2002 bust, it’s changing some sectors slowly but surely.

If IoT is happening then why do many people in the IT industry see no sign of it, making Industry analysts’ predictions look like so much hype? The simple answer is just like Social Marketing its not led by, or even happening very much within, the IT industry.

The most obviously visible IoT markets are consumer, but that doesn’t mean IoT isn’t happening elsewhere. Smart Homes top the list as in 2015 consumers drove this market into furious growth deploying a wide range of IoT Devices delivered via Smart Phone or Tablet based Apps that made their lives easier or more fun. A very conservative estimate, based on multiple Venture Capital Investment tracking reports indicates more than $1 billion has been invested in over 250 startups in the Smart Home, or Buildings sector.

Current consumer market leaders are well aware of this new market factor and have joined together in different consortiums each seeking to maintain their members market dominance through a new standard. Sadly ambitious consortium goals coupled to a membership more normally in competition with each other take time, and investment to achieve.

A closer examination of this market suggests that 2016 might be remember for being the year when the startups dismembered and disrupted the market leaders status faster than they could adapt. Its not only speed that is on the startups side, its also the amount invested. IoT Startups have more to spend on product development than market leaders are able to allocate for their IoT initiatives.

Smart homes are a well-researched sector able to provide some interesting feedback to other sectors and markets concerning key principles as to the disruptive progression of IoT based Smart Services. Whether a Consumer or Business markets the following characteristics can be seen;

  • A wholly new set of ‘values’ over turns traditional grounds for choice of product          
  • There are many startup players creating a wave of interest within the market
  • Smart Apps delivered on Smart Phones and Tablets are the user interface
  • Considerable Venture Capital Investments are supporting these disruptive players.

It’s the stunning amount of investment creating a massive number of startups covering any, and all, aspects of IoT that is the most striking feature of 2015. Venture Capitalists clearly believe not only in IoT, but that it will be a disruption to existing markets and create much new business value. The total across all aspects of the IoT provides more than enough investment to attack the current market and sector leaders across their entire product ranges, as well as introduce innovative new capabilities.

A recent Venture Capital investment report analyzed Honeywell’s product range in the building controls industry to name 31 startups specifically targeting one or more Honeywell products or changing their functions to Smart Services. In the Automotive sector another report named more than 600 startups vying for parts of the market, and overall there is a claimed $8.3 billion of investment in IoT.

The obvious question is why should the startups succeed against the established market leaders who have experience, resources and a customer base on their side? Some would argue that their very legacy positioning and experience makes it difficult to tackle such a level of disruption. This is not true as the example of John Deere detailed later shows. More pragmatically levels of investment in IoT startups is running several orders of magnitude ahead of the investments the existing players can afford to make. Added to this is the speed with which the startups can react and seize opportunities constantly innovatively and optimizing their products. The startups have skills, fast decision making, and most important of all, the democracy of the Internet on their side.

Time and again within a few quarters a new innovative Smart Service from an unknown startup has been catapulted into a scale of market awareness that conventional Brand based marketers can only dream about. The democracy of the Internet allows the meritocracy of a product, usually an innovative Digital Service, in outperforming the previous alternatives to be recognized, and promoted globally, fast!

Even those Enterprises born out of the Internet and Digital Business era such as Google, Facebook, and others, now risk being out classed in some important aspect of their business by a well-focused startup. Fortunately their corporate culture of fast reactive leadership, coupled with a buoyant share price, allows acquisitions as a strategy to aggregate their leadership. Intel and Cisco standout for their early stage investment programs that encourage promising startups that can add value to their business in one way or anther, but can traditional Enterprises manage the same, or is there another route?

The obvious question for 2016 in respect of current sector, and market, leaders is their ability to acquire the key IoT startups diminishing the most successful attackers, and accelerating their own market disruptive transformations? If not the alternative suggests that the startups will succeed in breaking the traditional competitive market pattern of two or three leaders holding 80% plus of the total market to create a new Internet meritocracy market place in its place.

In support of this argument remember that the number of Black Swans, or Unicorns, defined as companies that rise above a $1 billion valuation has never been higher as Digital Business introduces new market opportunities. A point that is clearly driving Venture Capitalists willingness to invest!

That’s not the only way and there are examples of sector, and market, leaders who have realized how to use the IoT startup market to reinforce their own value rather than allow an alternative platform, or a clutch of startups to triumph. In these cases there is an understandable progression in their use of each wave of new technology to create business value. In the last five years the route has been through Mobility into Smart Phone Apps and recognizable innovative Services, as part of this journey the adoption of IoT sensors has seemed a natural inclusion. These three stages of development characterize a three, or even five, year journey of growing experience; today at the start of 2016 this has to be an eighteen-month fast follower transformation to remain competitive.

Market place transformation is often initiated by customers, this certainly true in respect of the uptake of Apps, and App Shop distribution following the uptake of Smart Phones and Tablets. In parallel Mobility projects may have been more Enterprise focused providing useful experience, and often even more valuable data, in a wide range of sectors. A strategy to rapidly move into IoT Smart Services can successfully build on these foundations as the following example in the Farming Agri Business sector proves.

Farmers were quick to move into Mobility and Smart Phone, or Tablet Apps, with examples such as mobilefarmer.com described as ‘written by farmers for farmers’, or mobilefarmapps.com. As in other markets the arrival of these Apps stimulated the interest in, and acceptance of ‘Digital’ capabilities. Over time new Apps got smarter, more comprehensive and better integrated.  The use of sensor and sensing technology added new functionality and became a feature of a new generation such as efarmer.mobi. Starting with the multi sensing functionality of a Smart Phone for location, (as with so many Smart Services, i.e. Uber taxi cabs), efarmer.mobi and others built a range of more sophisticated real time services.

Venture Capitalists have been quick to see the opportunities in using IoT to transform farming with $269 million invested in 41 startups in Q3 2015 alone. As is the case in other sectors existing IoT Technology startups such as ThingsWorx have been quick to extend their core IoT Platform capabilities to include a focus on farming ecosystems. The terminology Smart Farming, or Precision farming, is now the generic recognized term. As in other sectors a host of startups are now competing with various forms of IoT sensor based Smart Services placing market leaders under attack.

It’s not only Farmers and Startups driving the market, other Agri-Business such as Farm Supplies have seen a competitive advantage in helping their customers to gain more yield at lower cost by precision control of seeds, fertilizers, and sprays. To discover exactly what form this takes read the story of Wilbur Ellis' Agribusiness division developing it’s own Smart Service platform complete with labor task management and worker collaboration tools. The platform was built  by Aditi a new breed of IoT technology integrator whose case study provides the story.

In might be a very different set of markets to the Smart Home/Buildings sector, but it’s a similar story with large numbers of well-funded startups surrounding and attacking established market leaders. (The common story that will become visible through 2016).  In this case a market leader, John Deere farm machinery, has turned the presence of IoT Startups to their advantage in creating their own market place disruption against their new and traditional competitors as well.

John Deere executed a classic Mobility to Smart App to IoT Platform progression strategy through a series of tactically beneficial business moves. The third stage, creating an IoT Market Sector Platform is crucial to both maintaining market leadership and creating a new innovative competitive IoT ecosystem that provides unique value to the whole industry market from end customer to other market suppliers.

There is urgency to introducing Smart Services as experience shows users are reluctant to delete and load a latter competitive App even if it has new features. Late entrants, even as fast followers, will find it very difficult to persuade users to change to their Smart Services, and even more so their new IoT Ecosystems platform.

There is true first mover advantage in establishing an Industry Sector, or local Market, IoT Ecosystem Platform and attracting as many as possible IoT Smart Services Startups to use your Platform. Early winners see numbers of connections, data points and complex event processing capabilities multiplied ever faster leaving later followers, unable to create the necessary volume.

IoT Smart Services are totally dependent on an adequate volume of events and data flows to be able to provide the basis to calculate Smart actionable insights. Startups and Smart Service developers will flock to an IoT Ecosystem Platform that can provide them with the best quality volumes. The John Deere IoT Ecosystem Platform has succeeded by aggregating the data, connection and Apps together with earlier Telematics and Mobility activities to create the necessary volume.

John Deere started in 2011 with the introduction of the John Deere Strategy around using sensors and data to increase the value that that ‘JDLink telematics’, as it was referred to at the time could add to John Deere customers. The valuable experience gained led smoothly into improved delivery and user interactions with the launch in 2012 of John Deere Mobile Farm Manager. Farmers showed themselves to be more than willing to adopt the advantages of Smart Phones and Tablets to run a new generation of Sensor based Mobility capabilities and associated Apps all of which were able to directly contribute to more profit per acre/hectare. By 2013 John Deere was realizing the power of connecting up its own ecosystem of John Deere dealerships into a range of Smart Services for reliable operational maintenance branded as John Deere Farm Sight.

By the end of 2013 John Deere was ready to go ahead with opening its myjohndeere platform to the agri-business industry as a whole creating a data and connection rich IoT Ecosystem platform that would attract Startups and established Agri-Businesses to make use of its unique positioning and capabilities.

It would be nice to end this journey with John Deere recording record revenues and profits, but Farming is a tough business with the last couple of years seeing farm prices for a wide range of commodities falling, as have sales of farm equipment. Against this background John Deere have performed as well as could be expected and are the 70th most valuable brand in the global brands survey. The question is what would have happened if John Deere had not taken action to transform themselves, their sector and value offered to their customers? The best answer lies in the story published by Data Science which charts the change from “Farming to big data; the amazing story of John Deere” in reading this article reflect on how many other market sectors the story applies to as well!

2015 looks to have been the year for IoT startups to build their products with 2016 becoming the year that a series of market visible disruptions will occur. Collectively well-financed startups will certainly be present in many sectors and localized markets in 2016, the extent that this will impact Market leaders is the big question. How many global sector leaders will seize the initiative to become IoT Ecosystem disruptors is the second question.

As ever predictions are hard, but as its the customers who are driving the market disruptions as they see new business values change is certain to occur, it’s the extent that is the real question.

New C-Suite

Unit4 announces integration with Slack - News Analysis

Unit4 announces integration with Slack - News Analysis

This morning Unit4, a rising ERP player with European origins, announced its partnership with the 'hot' collaboration startup Slack. As such its the first partnership of Slack, which has covered more than mindshare in SiliconValley, becoming the 'de-facto' collaboration tool for many local enterprises, and an enterprise software vendor. So well worth a blog post. 


So let’s take apart the press release in our customary style (it can be found here):
 
Utrecht, Netherlands, January 12, 2016 – Unit4, a fast growing leader in enterprise applications for service organizations, today announced a new integration with Slack.com, the messaging app for business teams. Slack delivers service industry professionals using Unit4’s people-centric ERP software a useful communications extension so that updates in Unit4’s Communities workspace become part of their Slack stream and vice versa.
MyPOV – Good synopsis of the partnership. Unit4 has put collaborative capabilities into it platform for people centric ERP, and the collaboration spaces of the platform are now getting integrated with Slack streams. Remarkably it’s a bi-directional interface and information from Slack finds a home in Unit4. Bi-Directionality is important to enable the way how people work, with two solutions and no need for manual synching.
 
The two-way integration enables Unit4 customer teams to bring together all communications in one place, replacing the need for project-related in-team email. Teams can organize conversations in open channels related to a specific project, topic, team or customer for example, increasing productivity and efficiency. As Unit4 achieves its vision of self-driving ERP, where applications self-learn to deliver real business insight, in-team collaboration and rapid response to opportunities will become a competitive differentiator.
MyPOV – Good formulation of the need for rigidity for scale (as often found in ERP software) and the flexibility for agility (as often found in collaboration software) and how Unit4 plans to deliver on these. Mastering the integration in a light weight ‘automagical’ fashion in one of the holy grails in enterprise software – often searched for – not really fully reached - so far.
 
Both Slack and Unit4 Business World are available via mobile applications making this a powerful solution for distributed teams across different geographies.
MyPOV – Good to mention the mobile aspect. More than half of work of business professionals now happens in a mobile setting and enabling work in a mobile setting is key. Achieving efficient mobile integration is not trivial – so it will be interesting to see

“Slack has become a popular collaboration tool for business as it is simple to use and ties together the many other disparate tools we use today like Dropbox, Google Docs and Twitter etc.,” said Erik Tiden, Unit4 CTO. “It won’t replace business email anytime soon but is a powerful alternative to in-team email. Teams can be up and running in seconds working together in open and private groups around any project or initiative. It again underlines our people-centric approach to ERP. For service teams working with our Business World ERP, it means they don’t always have to be logged into the system but can keep up on project status through the Slack.com mobile app, and conversations can be extended to customers and other external stakeholders.”
MyPOV – Good summary by Unit4 CTO Erik Tiden, supporting the people centric vision of Unit4.
 

Overall MyPOV

A good move by Unit4, delivering a proof point of people centric ERP. A compelling vision is one thing, delivering on it is harder but key to create both value for customers and differentiation in the marketplace. Slack is the collaboration tool that has captured a lot of mind share and is highly desirable for enterprise users to use. Traditionally both enterprise IT and enterprise vendors have been slow at offering support for these tools, creating frustration in the user base. With Unit4 supporting bi-directional integration with Slack it not only shows people centricity in product, but also in user appreciation. A welcome change for enterprise software and hopefully an inflection point creating a new attitude of both corporate IT and traditional enterprise software (ERP) vendors to people needs. 

This capability is a win for both vendors, more importantly for busy users in enterprises that need to connect their enterprise processes with collaboration capabilities. 

 
More on Unit4:
  • News Analysis - Unit4 picks Microsoft Azure for ‘Self-Driving’ ERP vision - Cloud, Machine Learning, Office and PaaS are the attractors - read here
  • Progress Report - Unit4 lays out a big vision - now it needs to execute - read here
  • News Analysis - Unit4 acquires Three Rivers Systems - read here

More on Future of Work
  • Musings – Time to re-invent email – for real! - read here
  • Musings - Future of Work – Is voice part of it? Post Cortana debut reflections.... - read here


For much more on the Future of Work, with a focus on social business and collaboration, check out my colleague Alan Lepofsky's blog here.


Find more coverage on the Constellation Research website here and checkout my magazine on Flipboard and my YouTube channel here
Tech Optimization Future of Work Innovation & Product-led Growth Next-Generation Customer Experience New C-Suite Marketing Transformation Digital Safety, Privacy & Cybersecurity Data to Decisions unit4 Chief Information Officer Chief Marketing Officer Chief Customer Officer Chief People Officer Chief Human Resources Officer

Salesforce Reboots Wave Analytics, Preps IoT Cloud

Salesforce Reboots Wave Analytics, Preps IoT Cloud

Salesforce Analyst Summit 2016 highlights Wave Analytics Cloud makeover and work in progress on the Internet of Things strategy and Salesforce Thunder.

Salesforce has successfully rebooted its Wave Analytics Cloud. It’s also apparent that company is trying to avoid the sorts of missteps that plagued Wave as it prepares Salesforce Thunder and the Internet of Things (IoT) strategy.

These are my two key takeaways from the January 5-7 Salesforce Analyst Summit in San Francisco, where executives discussed the company’s strategy and laid out product roadmaps for 2016. Execs also acknowledged some of the mistakes that were made in the launch of Wave, which was introduced 15 months ago at Dreamforce 2014.

The first iteration of Wave was, by most accounts, too expensive, too enterprise focused and packaged too much like a traditional BI platform. Starting with a platform (rather than pre-built apps) was essential, execs here insisted, because partners and customers would ultimately want and need a way to build vertical-industry and custom apps. But the market balked at the cost and complex packaging of the first-generation offering.

The second generation of Wave, introduced in September at Dreamforce 2015, is greatly simplified. For starters, Salesforce ditched separate Builder and Explorer licenses (priced at $250 and $125 per-user, per-month, respectively) and settled on an all-purpose platform license priced at $150 per user, per month. The company also introduced Sales Wave, the first of several planned prebuilt apps priced at $75 per user, per month. The apps are designed to speed and simplify deployment with user- and task-specific data flows and dashboards and templates for customizable analyses and actions.

Sales Wave templates, for example, provide a head start on analyzing sales levels, team performance and pipeline health. Prebuild historical analyses assess revenue by quarter, year-over-year rep productivity, and the length of sales cycles, among other measures. Administrators can set up triggers for recommended actions, such as resetting forecasts or prioritizing deals.

Detailing the Wave roadmap for 2016, Stephanie Buscemi, COO of the Analytics Cloud, said the previously announced Service Wave app will be available in April while a Marketing Wave app is in development. On the platform front she said Salesforce is working on a data-connector framework as well as scheduling capabilities and self-service data-prep options for Salesforce data.

MyPOV on Salesforce Wave

I believe Salesforce is finally on target with Wave’s packaging, pricing and a tighter, clearer focus on offering what Buscemi called “the best analytics option for Salesforce.” Some of the original attractions of Wave, including its user-interfaces and native mobile apps, still stand apart. And from what I hear about the appeal of prebuilt Wave apps (both from Salesforce and from customers), I expect the Salesforce Wave reboot to be a success.

Stay tuned on this front as Salesforce recently hired Microsoft veteran Bob Stutz to service as Chief Analytics Officer. Stutz won’t start until February, but I’d expect more tweaks to Wave as soon as April if adoption isn’t building as quickly as Salesforce would like. Keep in mind that third-party vendors BIRST and GoodData, among others, have been working on their versions of “the best analytics for Salesforce” for quite some time, but they would stress that they can provide insight beyond Salesforce.

Salesforce Thunder and the IoT Strategy

Salesforce announced its IoT Cloud Powered by Salesforce Thunder at Dreamforce 2015. The company even announced initial customers, but at that stage Thunder and the IoT Cloud were nowhere close to testing, let alone general availability. Last year I predicted we wouldn’t see Thunder until Dreamforce 2016, and based on IoT presentations and discussions at the Analyst Summit, I’m convinced that timing will hold.

What’s taking so long? Well, for starters, Thunder had its first customer pilot tests over the recent holidays, according to Adam Bosworth, Salesforce's Chief Strategic Officer, who is spearheading the development of Thunder and the IoT Cloud. (Bosworth is a storied veteran of Microsoft and Google who’s “a Johnny Appleseed of sorts in the tech industry,” according to a recent profile in the New York Times.)

Bosworth stressed at the Summit that the company “has many months to go” before Thunder and the IoT cloud will be ready. For now he says he’s asking early customers “lots of dumb questions,” like how they intend to make money off of IoT. With so many firms “wallowing” with big data investments, he said Salesforce is intent on starting with practical, revenue-driving use cases.

Salesforce Thunder was described as a kind of enterprise service bus capable of handling high-scale batch data as well as data streaming at rates in excess of 50,000 events per second. Thunder is based on open-source components including Kafka, Cassandra and Spark, but the point is not to establish Salesforce as an IoT infrastructure player.

“When we work with industrial, automotive and connected-device companies, what they are lacking is a way to drive [IoT] adoption,” said Alex Dayon, president of products. “We have to connect IoT with the customer business processes. Our value proposition is to bridge the IoT world – the signals from the machines — with the experience of the customer.”

Talking to execs at the Analyst Summit, it clear that there’s still internal debate about just what Salesforce will deliver with its first-generation IoT offerings. There’s a real danger with IoT offerings, said Bosworth, that customers will expect much more than what companies will be able to deliver. He cited the example of his wife’s connected car, which needs to go to the shop much more frequently than his much older analog car of the same brand. What’s more, the dealer never offers predictive insight into what’s wrong with his wife’s car even though the vehicle is loaded with so-called “smart” sensors.

MyPoV on Salesforce Thunder and the IoT Cloud

Meeting high customer expectations is one challenge. But Salesforce also has formidable internal technical obstacles to overcome. For example, overnight data latency is currently the standard where Wave insights are concerned, while cutting-edge deployments have reduced that data-update latency to about one hour. The trouble is that many IoT scenarios will demand near-real-time analytics, and that’s something Salesforce is still working on.

Dayon and others said the company’s IoT play will be focused exclusively on CRM-centric use cases, but in my book, big-data scalability, streaming-data processing and related analytical capabilities all have to be there as Wave and IoT platform-level capabilities. It’s another area where Salesforce will have to decide what it can should offer itself, what it can leave to partners and where, in future, it might have to rely on hyper-scale cloud partners such as Amazon or Microsoft Azure.

We’re venturing deeper, here, into questions that relate to the future of the entire company (and why there was talk of a Microsoft acquisition last year). Where our data-to-decisions research is concerned, suffice it to say that Salesforce has to do more than dabble with IoT and data-science capabilities.

Related Insights:

Salesforce Makes Wave Analytics More Accessible, Affordable
Salesforce IoT Cloud Awaits Thunder Real-Time Engine

The CMO Club and Oracle Deliver New Solution Guide to Help CMOs Transform Their Marketing Organization

The CMO Club and Oracle Deliver New Solution Guide to Help CMOs Transform Their Marketing Organization

The complexity of marketing has increased exponentially. The question on many CMO’s mind’s range from:

  • Do I have the right technology?
  • Am I using what I have well?
  • What else do I need?
  • Are my processes efficient and effective to take advantage of the technology?
  • Do my people have the right skills, mindsets and capabilities to deliver on all the various aspects marketing has expanded into – from SEO, to demand gen, to lead conversion, to e-commerce, to branding, storytelling and brand personas, to email, social and digital marketing…?
  • Are my strategies going to create the kind of lead conversion rates that will enable to expansion of my team and the respect that they should garner from the senior leadership team?
  • Do I have the right customer analytics strategy and can I execute on the data and data warehouses that are required to really know my customer and service real-time information where (channels & devices) when they need it?

To help CMOs meet skyrocketing customer and boardroom expectations, The CMO Club, along with Oracle,  released “The CMO Solution Guide for Building a Modern Marketing Organization.” The guide, which is based on interviews with CMOs and digital marketing leaders from major brands including Dow Chemical, JetBlue Airways, MasterCard, PayPal, Quiznos, The Hershey Company and Viking River Cruises, includes insights and best practices that CMOs can apply to build customer-first marketing teams that drive measureable results.

Screen Shot 2016-01-08 at 1.22.49 PM

To help marketers successfully manage this transformation, the new CMO Solution Guide provides practical advice from 20 in-depth interviews with CMOs and digital marketing leaders from organizations of various sizes and different industries.

Pete Krainik, CEO, The CMO Club said, “While the number of tools and amount of data available to marketers continues to multiply, the age old challenge of capturing and leveraging the right data to create engaging customer experience across all channels still exists. The first step they must take is to establish the appropriate organizational alignment to successfully create this type of customer experience. While no organization is exactly the same, this guide helps provide easy-to-implement changes that any marketer can use to drive transformation.

While there is no organizational model that fits every company universally, four key themes emerged during the course of the interviews that informed the organizational decisions that CMOs make: Acumen, Alignment, Agility and Accountability. More on those below:

  • Acumen: To become more effective modern marketers, respondents reported that enhancing the skills within their department has become a top priority. From developing valuable customer insights through data mining to investing in content creation and the need for greater evaluative analytics, leading marketers are investing heavily in helping their teams learn new skills.
  • Alignment: From top to bottom and across all functions, the guide shows that it is critical for all departments to follow the same processes and company culture in order to effectively engage customers across all touchpoints.
  • Agility: To meet consumer demands for exceptional customer experience, the guide noted how important it is for businesses to have strong cross-functional teams and the flexibility to pilot something new to test and learn best practices.
  • Accountability: To demonstrate marketing’s impact on the bottom line, the guide recommends establishing the right measures from the outset and instilling a culture of personal accountability around those parameters.

Along those lines is a larger question that looms in most organizations. That question is who should be the general manager of the overall customer experience? CMO’s are well positioned to be that person, but there are risks as well as rewards in taking on that responsibility. I’ve outlined some of them in a new report Should the Chief Marketing Officer Oversee the Whole Customer Experience? And I look forward presenting  the accompanying webinar coming up later 2016.

Should CMO Lead The Whole Customer Experience

While most brands may not realize it, they are competing on one important variable: customer experience. With all other things being equal, we are in a service economy and there’s nothing that is more important than the experience customers have with companies. And it’s not the brand promise creating by marketing that makes up that customer experience, but also the experience customers have with sales, service and back office operations. It’s not an easy question, but one that must be answered by every senior leadership team and their board of directors. That is what digital disruption is all about and companies not understanding this will go out of business or be acquired or merged for their customer list and cash flow. Poor customer experience, no business. Period. It’s that simple.

@DrNatalie, VP and Principal Analyst, Constellation Research

Covering Customer Facing Capabilities of Organizations to Deliver on Better Customer Experiences

Marketing Transformation Chief Marketing Officer

News Analysis: In Search Of Growth Amidst Digital Disruption

News Analysis: In Search Of Growth Amidst Digital Disruption

Organizations In Search Of Growth Must Consider Macro Forces

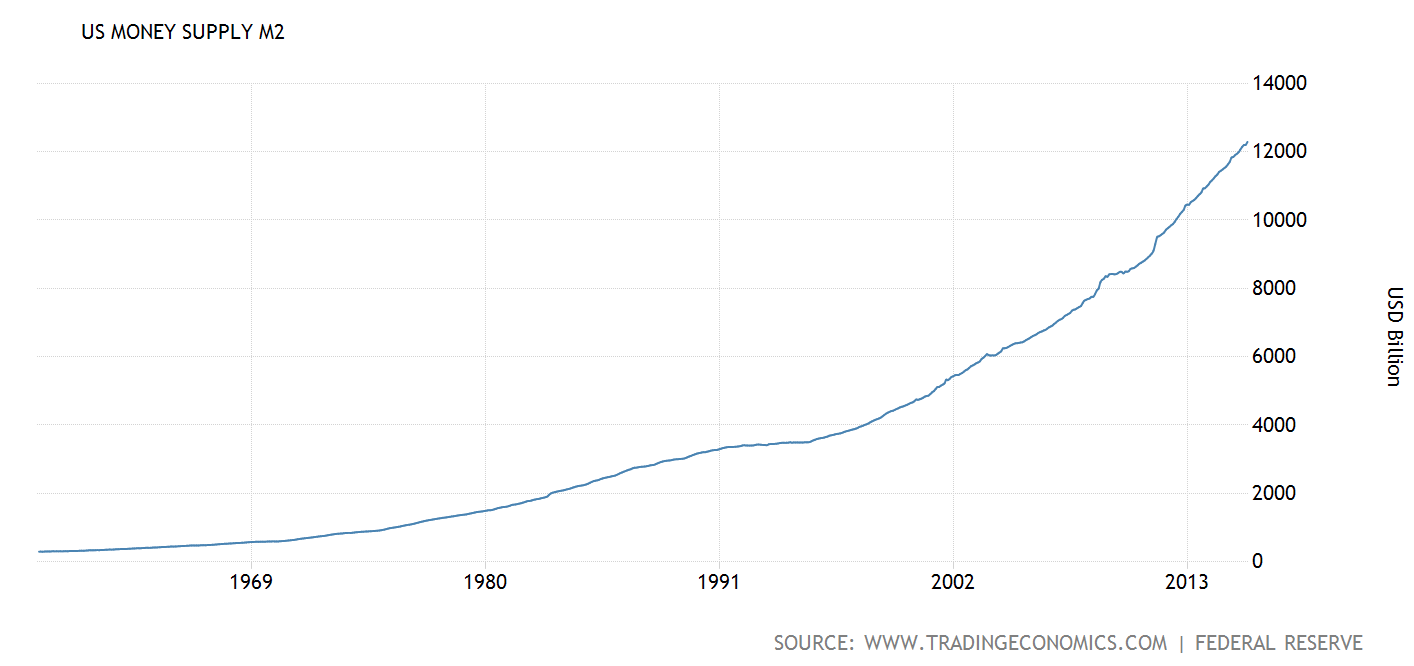
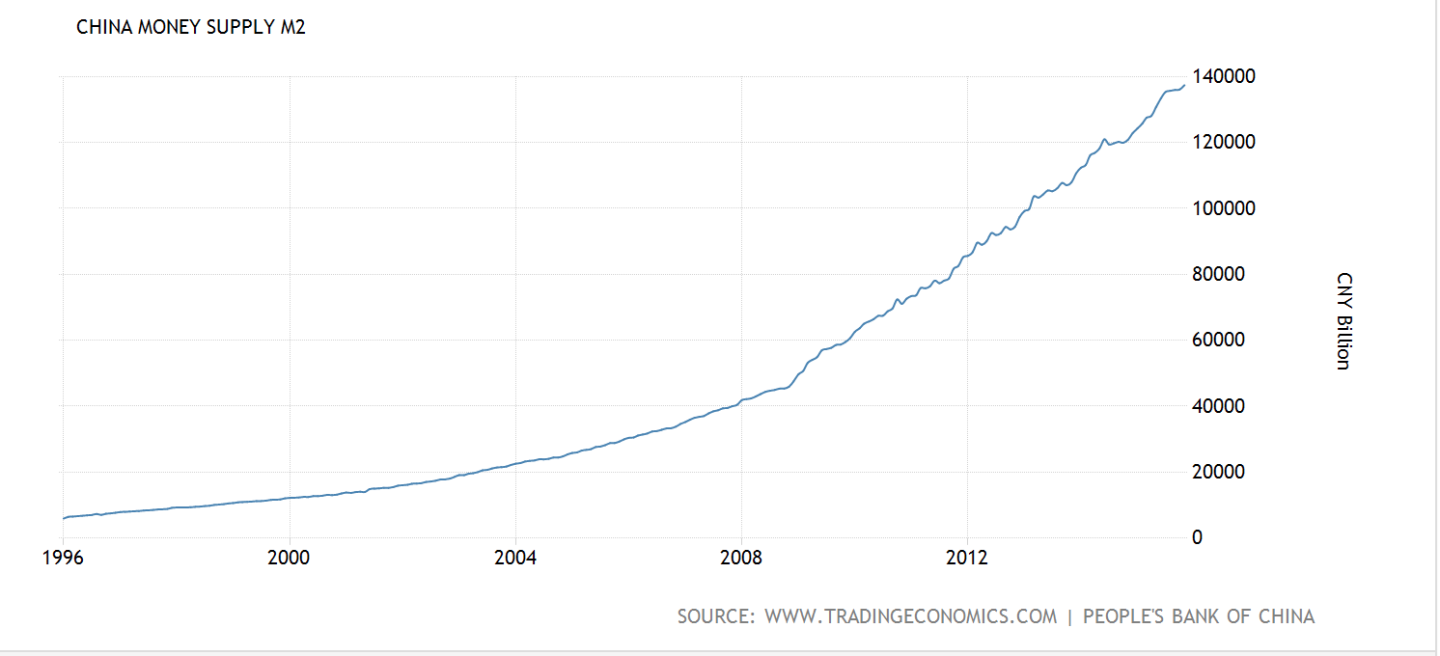
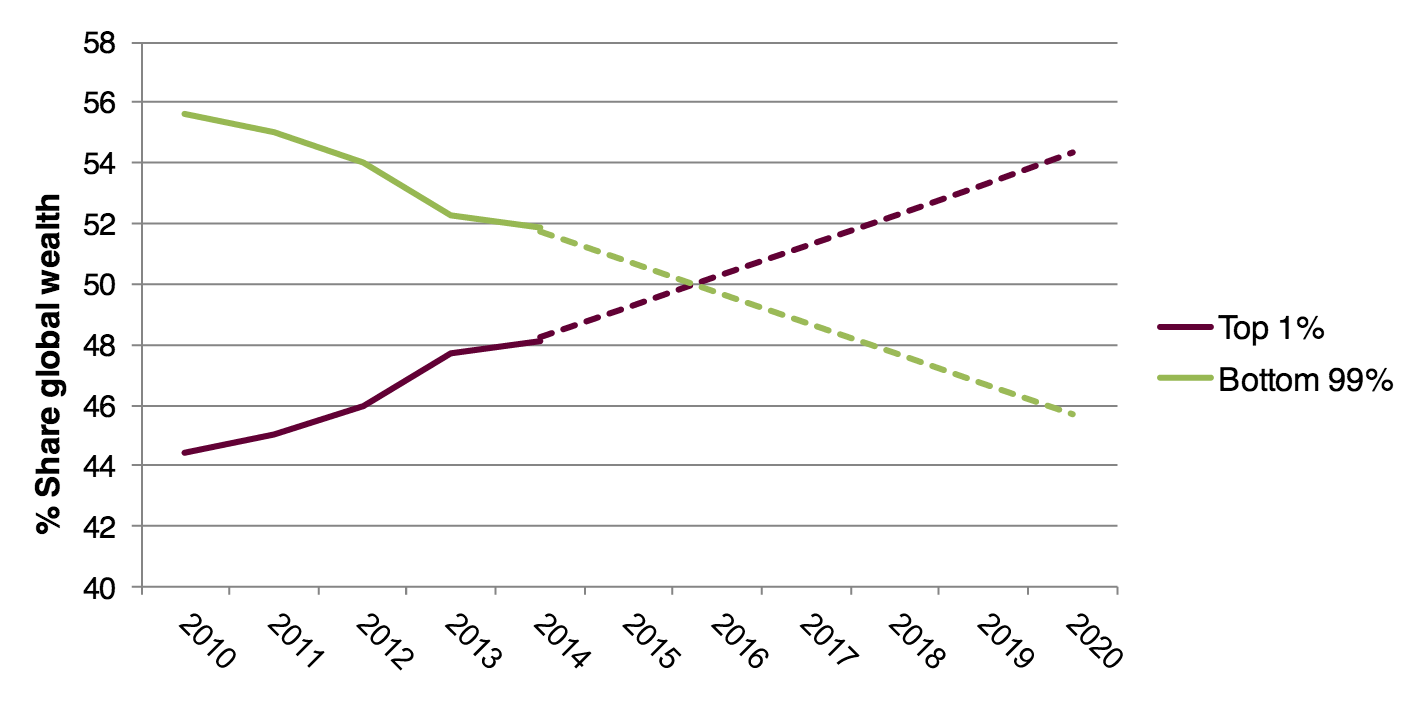
Burgeoning money supplies in both the US and China have fueled an indefensible growth post Global Financial Crisis.   Since 2000, the money supply has tripled from $6000 USD billion to 12288.10 USD billion in November of 2015 (see Figure 1).   Since 2005, china’s money supply has grown 7X from 20000 CNY Billion to 137400 CNY Billion in November of 2015 (see Figure 2).  While this level of money supply growth would normally cause inflation, income inequality has played a key role in keeping inflation in check because the richest 1% of people in the world now own more than 50% of global wealth (see Figure 3)

20160107 News Analysis: In Search Of Growth Amidst Digital Disruption from Constellation Research on Vimeo.

Figure 1. Massive Growth In US Money Supply M2 Shows Tripling since 2000

Money Supply United States

Figure 2. Chinese Money Supply (M2) Has Increased Seven Fold Since 2005

Chinese Money Supply

Figure 3. By 2016, The Top 1% Will  Have More Than 50% Share Of Global Wealth

Wealth Inequality 2016

Lesson 1 – Transform Business Models And Engagement

Lesson 2 – Keep The Brand Promise

Lesson 3 – Sell The Smallest Unit You Can

Lesson 4 – Know That Data Is The Foundation Of Digital Business

Lesson 5 – Build For Insight Streams

Lesson 6 – Win With Network Economies

Lesson 7 – Humanize Digital With Digital Artisans

Lesson 8 – Democratize Distribution With P2P Networks

Lesson 9 – Deliver Intention Driven, Mass Personalization At Scale

Lesson 10 – Segment by Digital Proficiency Not Age

Digital Disruption, Technology Startups, And Mergers Drive Growth

Investors tasked to achieve growth have mostly approached the challenge by:

  1. Pushing for mergers and acquisitions
  2. Investing in technology startups
  3. Investing in startups with disruptive business models

The result has been an average age of company on the S&P 500 down from 60 years to 15 years and 52% of the Fortune 500 merged, acquired, gone bankrupt, or fallen off the list since 2000.   Even worse, the proliferation of bets in these three categories is exacerbating the number of organizations in the market and reducing the number of growth options

The Bottom Line: Digital Darwinism Is Unkind To Those Who Wait

Organizations focused on jump starting growth must begin their transformation to a digital business.  With fewer and fewer companies surviving as margin based businesses, those organizations building new digital business models will be rewarded with growth valuations.  As the winner takes all market continues, digital transformation is a key lever in the ability to grow profits, expand markets, and dominate a market.

Get The Book Now Before Digital Darwinism Impacts You

Purchase on Amazon
Bulk Orders: contact [email protected]
About Disrupting Digital Business

Join the Digital Disruption Tour. Events in San Francisco, Atlanta, London, and Amsterdam!

Your POV.

Are you ready to disrupt digital business?  Have you ordered the book?

Add your comments to the blog or reach me via email: R (at) ConstellationR (dot) com or R (at) SoftwareInsider (dot) org.

Please let us know if you need help with your Digital Business transformation efforts. Here’s how we can assist:

  • Developing your digital business strategy
  • Connecting with other pioneers
  • Sharing best practices
  • Vendor selection
  • Implementation partner selection
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Resources

Reprints

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales .


New C-Suite Innovation & Product-led Growth Tech Optimization Future of Work Data to Decisions ML Machine Learning LLMs Agentic AI Generative AI Robotics AI Analytics Automation B2B B2C CX EX Employee Experience HR HCM business Marketing Metaverse developer SaaS PaaS IaaS Supply Chain Quantum Computing Growth Cloud Digital Transformation Disruptive Technology eCommerce Enterprise IT Enterprise Acceleration Enterprise Software Next Gen Apps IoT Blockchain CRM ERP Leadership finance Social Healthcare VR CCaaS UCaaS Customer Service Content Management Collaboration M&A Enterprise Service Chief Information Officer Chief Technology Officer Chief Digital Officer Chief Data Officer Chief Analytics Officer Chief Information Security Officer Chief Executive Officer Chief Operating Officer Chief Experience Officer

Social and Digital Media Requires Brands to Become Publishers

Social and Digital Media Requires Brands to Become Publishers

I think most brands, when they started in social and digital media didn’t realize the commitment they were heading into to be content creators or essentially publishers. But what the recent past has shown is that engaging customers in digital and social is that great content is key – for  engagement, interaction, thought leadership, social selling and being on customer’s radar as relevant and authentically genuine in this new digital era. And interesting chart by SmartInsights, shows what happens every 60 seconds:

Content management positing dr natalie

Potential and current customers use social and digital media to research and compare products and services. The chart shows that from 2013- to 2016 the amount of content created and posted is growing nearly exponentially. The difficulty for brands is that there’s some much content out there, that it can be difficult to ensure that the content they are creating is cutting through all the noise and is not only noticed but taken seriously. It’s a whole lot of creative going to waste otherwise. And that’s one of the reasons it is so important for brands to really understand storytelling and the mix of content they are using — it can’t be all “buy our stuff.” It has to be a combination of inspiration, motivational, information, humor as well as fun.

Part of the reason that the type of content brand’s publish is so important is that studies show that people have limited attention spans and time to pay attention to all the content that is posted. It’s not possible for humans to cognate all the digital and social content being posted. And research by Moz and Buzzsumo shows that the majority of content marketing has limited impact with 75% of blog posts they analysed getting fewer than 10 social shares and zero links from other domains. It also presents an issue for marketers who are researching best practice in different areas, as often there are so many different messages it is hard to know where to begin. And that’s where storytelling, branding and brand personas come into play. That’s part of what I teach in my UCLA course in digital media. And it’s not just important to marketing, customer service and sales and other departments need to be paying attention to this content conversation. If your brand was a person, what would its voice be like? Snarky? Smart, Goofy? Funny? Brainiac, Sweet, Kind…. Those are only the beginnings of what storytelling and brand personas need to be considering….

If you are a brand, it’s time you looked at your content, and your content and digital engagement strategies (marketing, sales and service) and make sure you are providing what customers need and want to stand out in a very crowd space.

@drnatalie, VP and Principal Analyst, Constellation Research

Covering customer experience in the digital era of a service economy

Share

Marketing Transformation Next-Generation Customer Experience Chief Customer Officer Chief Marketing Officer

Salesforce 2016: Intelligence, Analytics and IOT

Salesforce 2016: Intelligence, Analytics and IOT

Earlier this week Salesforce held their 2016 Analyst Summit. At this event, they shared information about their product and marketing plans, we heard customer stories, and we were able to ask questions to several top executives. In the video below I provide an overview of the Salesforce product portfolio, explain some of the terminology they use (ex: Lightning, Thunder, Wave, Salesforce1), and highlight some of their strengths in the collaboration market. 


While not covered in the video, there are areas I would like to see Salesforce improve in their collaboration portfolio, such as:

  • Better project/task management
  • Real-time communication (1:1 or group video chat)
  • Long form content creation (i.e. notes/documents that are longer than Chatter posts)

I asked about each of these, and while I am not able to disclose Salesforce's replies, I can tell you they are aware of each of these shortcomings. In some cases these areas will be addressed by Salesforce building new features, some by product acquisition and some things will be solved by integration with partner products.

I look forward to seeing Salesforce's progress in 2016 around personal productivity, team collaboration and customer engagement. I'll be keeping a close watch on how they leverage intelligence (AI), analytics, and the Internet of Things (IOT) to improve each of these areas.


Marketing Transformation Next-Generation Customer Experience Revenue & Growth Effectiveness Data to Decisions Future of Work Innovation & Product-led Growth New C-Suite Digital Safety, Privacy & Cybersecurity Tech Optimization Chief Customer Officer Chief Digital Officer Chief Executive Officer Chief Information Officer Chief Marketing Officer Chief People Officer Chief Procurement Officer Chief Revenue Officer Chief Experience Officer

Happy New Year 2016! Looking forward to a sweet 16 year for Supply Chains

Happy New Year 2016! Looking forward to a sweet 16 year for Supply Chains

Happy New Year to all, I hope that your 2016 is already off to a great start. Looking forward to this year there are some exiting changes as well and continued progress in other areas. Here are some trends we are focusing on for 2016:

  • Retailers will continue to seek new solutions and services to empower their stores: in 2015 we started seeing greater efforts and emphasis on the role of brick and mortar stores. Written off as irrelevant, even a burden a few years ago, retailers’ views of their real estate assets has taken a turn. Brick and mortar stores’ role in the retail supply chain will continue to grow in importance. This momentum is due to the evolution of how stores are being leveraged by retailers. Embracing show rooming, leveraging stores as distribution centers, creating contextual experiences within the store to drive traffic to name a few indextrends, are all making stores matter again. Most significantly the redefinition of the store’s role allows traditional retail to tackle the pure eCommerce players. 2016 will continue to see this evolution of the store. Gaining improved inventory visibility, empowering store associates with greater information, enhanced operational data to allow more business processes to be tested and adopted are all areas where retailers will be seeking appropriate solutions. Look for retailers to lean on their solution and service providers to bring them the necessary technology and business processes that can allow retailers to continue to transform their physical assets. Solution and service providers must work with their retail clients to not only provide technology or business process solutions, but to also offer strategic insights and ideas. Technology is not the panacea but the enabler for new ideas and processes.
  • Logistics continues to feel the strain: Your supply chain is only as strong as your ability to minimize the friction associated with moving inventory and products throughout your supply chain. This burden falls on logistics – rail, ocean, air, trucks even bicycles and donkeys are all part of our logistical network. This past holiday season witnessed another situation where the strain on the logistics network can rear its ugly head. eCommerce retailer Jet.com had to apologize to some of their clients for falling short on being able to deliver products in time for Christmas. Logistic giants FedEx and UPS had to jump through some hoops to meet the delivery crush. Coincidentally, over the holidays,  eCommerce giant Amazon announced it is exploring adding an air cargo arm to their distribution assets. While eCommerce is growing at a steady 1o-15% year over year since 2012, the strain it is placing on logistics is disproportionate – due in large part to seasonal aspect of certain package delivery. The strain is also starting to pop up in places such as college campus mail rooms where they are being overwhelmed by services such as Amazon Prime. This trend is not going to disappear once the calendar flips to 2016. Transportation and warehousing will continue to feel the strain of keeping up with the accelerated evolution of supply chain in 2016. Look for continued efforts from service and solution providers to work with their customers to continue to find innovate manners to handle the crush of logistics.
  • Explosion of disruptive technologies continue to grow: Whether it is IoT (internet of things), robotics, drones, 3d printing or virtual reality to name a few, these disruptive technologies will continue to grow in importance within supply chains. IoT is already well entrenched within manufacturing and logistics, in 2016 look for this technology to grow in importance with regards to the retail supply chain. Robotics are also well know within manufacturing, but look for this technology to play a greater role in places such as customer service and inventory management in retail. Drones are getting much attention, somewhat negative, post holidays as those who unwrapped them as gifts are wondering if they need to register with the FAA, there was even a near disaster during a World Cup skiing race when a drone literally fell from the sky, click here for video. Reality is drones have a role to play in our supply chains – the genie is out of the bottle and properly leveraged they can reduce friction from our supply chains. As indextechnology giants Amazon and Google continue to push on how to leverage these machines to address last mile delivery. Additive manufacturing will continue to play a role in the manufacturing process, but will also create new business models. Companies such as Lowes are already experimenting with 3D printers in their stores, allowing customers to have custom products manufactured on site.  3D printing is already playing a significant role with manufacturers such as Airbus and Boeing, but we are only at the cusp of how this disruptive technology will play in our supply chains. Finally virtual reality will continue to play a role in places such as retail – allowing customers to experience product as well as in supply chain design and CAD software. As mentioned above, we see warehousing and other logistics being strained as more companies look to add more of these assets, leveraging virtual reality allows for better testing and understanding of how these capex projects will turn out. Imagine being able to test and try out a full scaled model of a plant or warehouse via virtual reality. Look for these technologies and others continue to grow in importance within our supply chains.

Every year at this time it is always interesting to look back and see what the prior year held for us and more fun to look forward to the coming year. As I have become more of an optimist as I have grown older (is that normal?) I am looking forward to 2016 and some of continued evolution of these technologies and trends.

Happy New Year to you and your loved ones!


Tagged: 3D printer, Drones, IOT, Logistics, Retail, Robotics, Supply Chain, Warehouse

Matrix Commerce Chief Information Officer

IoT, Smart Cities and Virtual Reality with $29.99 Goggles A serious yet slightly fun piece to kick off 2016!

IoT, Smart Cities and Virtual Reality with $29.99 Goggles A serious yet slightly fun piece to kick off 2016!

A first post for 2016 aiming to start the year with a mix of fun and a serious point concerning a $29.99 virtual reality ‘toy’ that will have been Christmas present for a lot of kids. The View-Master is a toy only because it is being marketed that way, it is actually a quality product based on Google Cardboard. This is mass consumer market Virtual Reality ideal for Smart City Services!

View-Master provides a set of goggles for $29.99 into which most popular current Smart Phone fit making Virtual Reality a cost effective proposition to add value to many tasks, or to Smart Cities projects. A link in the last paragraph instructs on how to make a City weather map in Virtual Reality.

It’s not too easy to see in this photo, but there is a Smart Phone encased in the goggles providing a split image for the eyepieces. The genius of the approach is to make use of that most readily available piece of Technology; a Smart phone, to collect the images and deliver to the eyepieces.


For kids with non-techie fathers there are conventional round discs of photos, but a simple download gives the Smart Phone the ability to take photos, or download photos, before turning them into Virtual Reality scenes. Suddenly it doesn’t take huge expensive headsets to deliver Virtual Reality, instead the ubiquitously to hand Smart Phone acquires yet another useful function.

The use of pictures, which includes time lapse from Web Cams, would offer many possibilities for sharing information in a Smart City environment. In addition Virtual Reality also provides additional information when linked to IoT events, and actionable outcomes. As and example traffic and travel information on new road layouts of often includes 2D photos, how much better to be able to navigate the new junction in Virtual Reality.

For a Service Engineer receiving a call out on their Smart Phone, the notion of popping the Smart Phone into low cost Virtual Reality goggles to actually see location and other machine details makes sense. 

Asset Digitization implementations can readily include Photographs for Virtual Reality along with a mass of other data aligned to the specific IoT sensor reporting the event.

View-Master is based on the Virtual Reality approach pioneered by Google under the name of ‘Google Cardboard’. The picture shows the name to be descriptive of the innovative low cost approach taken to constructing the usually prohibitively expensive V-R Goggles, or Headset.  Google Cardboard was meant to be a game-changing move with a low cost mass-market uptake to encourage adoption in the consumer market.

Google offers a full range of support options including Software Developer Kits, though currently limited to Android, through to the Google Cardboard


blogs to share ideas and experiences. (View-Master also supports

Apple iOS 6 as well as Android, suggesting that this cannot be too difficult to achieve). The notion of Cardboard goggles may seem a little weird, even whacky, but the principle of creating highly affordable mass market Virtual Reality could well become achievable by this approach.


There is a further separate site apparently offering similar support to the Google Cardboard nominated above, but under the Chrome Browser heading, billed as Chrome Browser Virtual Reality experiments. A further useful link is the PC Advisor list of the twelve best consumer apps providing a good starting point to see some ideas of what can be achieved with the Technology. If you want to get started then there are recommendations for DoDocase as the place to buy the basic cardboard viewer, see some Apps, as well as get some support.

Over recent years many of the technologies that have transformed Business have started out as a consumer technology before being adopted by business. It would seem that Virtual Reality might be set to enter the mainstream in the same way.

Returning to conclude with the topic of Smart Cities; there is no shortage of research papers concerning the benefits that Virtual Reality can bring to Smart Cities.  (try googling Virtual Reality Smart Cities to see a good selection). The drawback has, up till now, been the cost and complexity of Virtual Reality goggles, or headsets. This is a problem conveniently bypassed by the Google Cardboard approach, which though not as sophisticated a solution, does bring the cost and availability down to suit consumers, or citizens.

This paragraph is for those technically interested enough to want to try out building a Virtual Reality App for City weather forecasts using Google Cardboard.  It’s fully spelt out as to how to write this App in detail by Patrick Catanzarti at Site point in a post entitled Bringing Virtual Reality to the Web using Google Cardboard.
The Internet of Things primarily provides awareness of remote events and situations that call for actions. As more and more devices provide visual data it is logical that Virtual Reality will become increasingly popular providing that a price point can be reached. View-Master and Google Cardboard bring that point within reach, and Smart Cities are a likely starting point for new Apps.

New C-Suite