Results

Oracle's List of 100-Plus Cloud Applications

Oracle's List of 100-Plus Cloud Applications

Oracle has now responded to analyst requests for a list of the 100+ cloud applications that Larry Ellison claimed in his Oracle Cloud presentation last week. I've just checked, and his exact words were "Over 100 enterprise-grade applications running in the cloud."

But the email cover for the list sent this morning refers to them as "100+ application services." As I speculated last week, Oracle is defining "application services" at very fine-grained level, almost down to individual programs.

For example, within "Oracle Fusion Customer Relationship Management - Marketing" is "Fusion Marketing Segmentation - up to 500,000 records" really a separate and distinct application from "Fusion Marketing Segmentation - up to 1,000,000 records?"

Update 1: Upon further review, I'm wondering why Oracle CRM On-Demand, a multi-tenant SaaS application, is missing from Oracle's list.

Update 2: I'm also wondering, using Oracle's definition of "applications," how many does SAP have?  In his presentation, Ellison said, "SAP only has SuccessFactors." Leaving aside my point that Ellison did not credit Business By Design or SAP's line of business applications as cloud apps, how does "SuccessFactors" count as one application, but Oracle's Taleo counts as 24 (see list below)?


Here is the complete list of what Oracle claims as its 100+ cloud applications:

Oracle RightNow

Oracle RightNow Dynamic Agent Desktop Cloud Service: Seats
Oracle RightNow Standard Dynamic Agent Desktop Cloud Service
Oracle RightNow Enterprise Dynamic Agent Desktop Cloud Service
Oracle RightNow Enterprise Contact Center Dynamic Agent Desktop Cloud Service
Oracle RightNow Standalone Chat Dynamic Agent Desktop Cloud Service
Oracle RightNow Dynamic Agent Knowledgebase Cloud Service
Oracle RightNow Chat Cloud Service
Oracle RightNow Cobrowse Cloud Service
Oracle RightNow Cobrowse Remote Support Cloud Service
Oracle RightNow Contextual Workspaces Cloud Service
Oracle RightNow Guided Assistance Cloud Service
Oracle RightNow Agent Scripting Cloud Service
Oracle RightNow Desktop Workflow Cloud Service
Oracle RightNow Product Registration Cloud Service
Oracle RightNow Social Monitor Cloud Service


Oracle Taleo

Taleo Enterprise Cloud Service Platform
Taleo Platform Cloud Service
Taleo Analytics Cloud Service
Taleo Recruiting Cloud Service
Taleo Recruiting High Volume Cloud Service
Taleo Onboarding Cloud Service
Taleo Performance Management Cloud Service
Taleo Goal Management Cloud Service
Taleo Succession Planning Cloud Service
Taleo Development Planning Cloud Service
Taleo Learn Cloud Service
Taleo Learn External User Cloud Service

Taleo Enterprise Recruiting Assessment Content
Taleo Hourly Assessment Content Cloud Service
Taleo Store Manager Assessment Content Cloud Service
TBE Recruiting Standard Active User Cloud Service
TBE Recruiting Premium Active User Cloud Service
TBE Recruiting Manager Cloud Service

Taleo Business Edition - Per Employee
TBE Recruiting Premium Cloud Service
TBE Smart Sourcing Base Cloud Service
TBE Smart Sourcing Per Posting Cloud Service
TBE Onboarding Cloud Service
TBE Compensation Cloud Service
TBE Performance Management Cloud Service

Taleo Business Edition - Learn
TBE Learn Cloud Service
TBE Learn External Trainees Cloud Service


Oracle ATG

Oracle ATG Live Help
Live Help Interactions On Demand
Live Help Chat On Demand
Live Help Email On Demand
Live Help Cobrowse Chat On Demand
Live Help Cobrowse Phone On Demand
Recommendations Single-Channel On Demand
Recommendations Multichannel On Demand
Recommendations Additional Catalog On Demand
Recommendations Large Catalog On Demand


Oracle Fusion Applications

Oracle Fusion CRM Base Cloud Service
Fusion CRM Base Standard Offering Cloud Service
Fusion CRM Base Enterprise Offering Cloud Service
Fusion CRM Base Premium Offering Cloud Service
Fusion Transactional Business Intelligence for Customer Relationship Management Cloud Service
Fusion Enterprise Contracts Management Base Cloud Service
Fusion Incentive Compensation Cloud Service
Fusion Opportunity Landscape Cloud Service
Fusion Quota Management Cloud Service
Fusion Sales Campaigns Cloud Service
Fusion Sales Predictor Cloud Service

Oracle Fusion Marketing Cloud Service
Fusion Marketing, Enterprise Edition Cloud Service
Fusion Marketing, Additional Volume Cloud Service
Fusion Marketing, Additional Email - 500,000 Messages

Oracle Fusion Partner Relationship Management Cloud Service
Fusion Partner Relationship Management for Channel Managers Cloud Service
Fusion Partner Relationship Management for Partners Cloud Service
Fusion Territory Management for Channel Managers Cloud Service

Oracle Fusion Customer Data Management Cloud Service
Fusion Customer Data Steward Cloud Service
Fusion Customer Management Foundation for Organizations Cloud Service
Fusion Customer Management Foundation for Persons Cloud Service
Fusion Data Quality Address Cleansing Cloud Service
Fusion Data Quality Matching Cloud Service
Oracle Fusion Human Capital Management Cloud Service
Fusion Human Capital Management Base Cloud Service
Fusion Transactional Business Intelligence for Human Capital Management Cloud Service

Oracle Fusion Human Capital Management Cloud Service Options
Fusion Global Payroll Cloud Service
Fusion Goal Management Cloud Service
Fusion Payroll Interface Cloud Service
Fusion Performance Management Cloud Service
Fusion Talent Review Cloud Service
Fusion Workforce Compensation Cloud Service
Fusion Workforce Lifecycle Manager Cloud Service
Fusion Workforce Predictions Cloud Service

Oracle Fusion Talent Management Cloud Service
Fusion Talent Management Base Cloud Service
Fusion Transactional Business Intelligence for Talent Management Cloud Service

Oracle Fusion Talent Management Cloud Service Options
Fusion Goal Management Cloud Service
Fusion Performance Management Cloud Service
Fusion Talent Review Cloud Service
Fusion Workforce Compensation Cloud Service

Oracle Fusion Financials Cloud Service
Fusion Financials Cloud Service
Fusion Expenses Cloud Service
Fusion Advanced Collections Cloud Service
Fusion Automated Invoice Processing Cloud Service
Fusion Financial Reports Center Cloud Service
Fusion Transactional Business Intelligence for Financials Cloud Service

Oracle Fusion Procurement Cloud Service
Fusion Purchasing Cloud Service
   Option: Fusion Supplier Portal Cloud Service
   Option: Fusion Sourcing Cloud Service
Fusion Procurement Contracts Cloud Service
Fusion Self Service Procurement Cloud Service
Fusion Enterprise Contracts Base Cloud Service
Fusion Transactional Business Intelligence for Procurement Cloud Service

Oracle Fusion Project Financial Management Cloud Service
Fusion Project Financial Management Base Cloud Service
Fusion Project Control Cloud Service
Fusion Project Billing Cloud Service
Fusion Project Contracts Cloud Service
Fusion Enterprise Contracts Base Cloud Service
Fusion Project Performance Reporting Cloud Service
Fusion Transactional Business Intelligence for Project Financial Management Cloud Service

Oracle Fusion Project Execution Management Cloud Service
Fusion Project Management Base Cloud Service
Fusion Collaborative Project Management Cloud Service
Fusion Transactional Business Intelligence for Project Execution Management Cloud Service
Fusion Project Resource Management Cloud Service

Oracle Fusion Risk and Control Management Cloud Service
Fusion Risk and Control Management Base Cloud Service
Option: Fusion Risk and Compliance Management Cloud Service
Option: Fusion Risk and Compliance Intelligence Cloud Service
Option: Finance Controls Cloud Service
Option: Procurement Controls Cloud Service
Option: Human Capital Controls Cloud Service
Option: Fusion Controls On-Premise Connector Cloud Service

Oracle Fusion Supply Chain Management Cloud Service
Fusion Inventory Management Cloud Service
Fusion Product Hub Cloud Service
Fusion Transactional Business Intelligence for Supply Chain Management Cloud Service

Oracle Hyperion Cloud Service
Hyperion Planning Plus Cloud Service

Oracle Fusion Cloud Service Additional Add-On
Fusion Applications Extensibility Framework Cloud Service

Oracle Fusion Financials
Fusion Accounting Hub
Fusion Advanced Collections
Fusion Automated Invoice Processing
Fusion Expenses
Fusion Financial Reports Center
Fusion Financials
Fusion Transactional Business Intelligence for Financials

Oracle Fusion Procurement
Fusion Procurement Contracts
Fusion Purchasing
Option: Fusion Sourcing
Option: Fusion Supplier Portal
Fusion Self Service Procurement
Fusion Transactional Business Intelligence for Procurement

Oracle Fusion Project Portfolio Management
Fusion Project Billing
Fusion Project Contracts
Fusion Project Control
Fusion Project Costing
Fusion Project Integration Gateway
Fusion Project Performance Reporting
Fusion Transactional Business Intelligence for Projects

Oracle Fusion Human Capital Management
Fusion Benefits
Fusion Global Human Resources
Fusion Global Payroll
Fusion Global Payroll Interface
Fusion Goal Management
Fusion Performance Management
Fusion Talent Review
Fusion Transactional Business Intelligence for Human Capital Management
Fusion Workforce Compensation
Fusion Workforce Directory Management
Fusion Workforce Lifecycle Manager
Fusion Workforce Predictions

Oracle Fusion Supply Chain Management
Fusion Distributed Order Orchestration
Fusion Distributed Order Orchestration User
Fusion Global Order Promising
Fusion Inventory Management
Fusion Product and Catalog Management
Fusion Product Hub
Fusion Product Hub Data Steward
Fusion Product Hub for Communications
Fusion Product Hub for Retail
Fusion Transactional Business Intelligence for Supply Chain Management

Oracle Fusion Customer Relationship Management - Sales
Fusion CRM Base
Fusion CRM Desktop
Fusion Enterprise Contracts Base
Fusion Incentive Compensation
Fusion Opportunity Landscape
Fusion Quota Management
Fusion Sales Campaigns
Fusion Sales Catalog
Fusion Sales Predictor
Fusion Smart Phone Edition
Fusion Territory Management
Fusion Transactional Business Intelligence for Customer Relationship Management

Oracle Fusion Customer Relationship Management - Marketing
Fusion Email Marketing Server
Fusion Marketing
Fusion Marketing Segmentation - up to 500,000 records
Fusion Marketing Segmentation - up to 1,000,000 records
Fusion Marketing Segmentation - up to 3,000,000 records
Fusion Marketing Segmentation - up to 5,000,000 records
Fusion Marketing Segmentation - up to 10,000,000 records
Fusion Marketing Segmentation - unlimited records

Oracle Fusion Partner Relationship Management
Fusion Incentive Compensation for Channel Managers
Fusion Partner Relationship Management for Channel Managers
Fusion Partner Relationship Management for Partners
Fusion Territory Management for Channel Managers

Oracle Fusion Customer Relationship Management - Customer Data Management
Fusion Customer Hub Data Steward
Fusion Customer Hub for Organizations
Fusion Customer Management Foundation for Organizations
Fusion Customer Hub for Persons
Fusion Customer Management Foundation for Persons
Fusion Data Quality Address Cleansing
Fusion Data Quality Matching

Oracle Fusion Application Tools
Fusion Applications Extensibility Framework

Oracle Fusion Governance, Risk and Compliance
Fusion Application Access Controls Governor
Option: Fusion Application Access Controls for Fusion Applications


Related Posts

Oracle's Behavior Undercuts Its Own Cloud Accomplishments

Tech Optimization
Oracle's Behavior Undercuts Its Own Cloud Accomplishments

Oracle's Behavior Undercuts Its Own Cloud Accomplishments

Oracle held a much anticipated "Oracle Executive Strategy" update event for its Oracle Cloud services yesterday. With Larry Ellison leading the presentation, there was much thunder and lightening--but not much rain. This is unfortunate, because Oracle has put together an impressive set of cloud services. Ellison's inability to resist slamming the competition led him to overstate what Oracle has actually delivered, and to minimize the success of Oracle's competitors.

This post serves as a summary of the key points I gleaned from the webcast and from an analyst question and answer session afterwards with Thomas Kurian, Oracle's EVP of Product Development, who is always a pleasure to listen to.

Is There Anything New?

On Twitter and in back channel Skype conversations with other analysts, many of us were questioning: what exactly is being announced today? Nearly everything presented had been previously been presented at Oracle Open World in 2011.

Reading carefully through the pre-event summary document and scanning through my notes, I can only come up with two things that are new:

  1. Oracle is announcing new Oracle Fusion cloud applications and services in addition to those  announced during Open World (which were CRM, HCM, Social Network, Java Service, and Cloud Service). Larry Ellison indicated that Oracle now has 100 cloud applications and services.
     
  2. Oracle demonstrated some of the social marketing functionality from its Vitrue acquisition, which Oracle announced in March. 

Other than that, it's difficult to find anything that Oracle had not announced or presented earlier. So the event was largely a re-presentation of Oracle's cloud services, some demonstration, and a healthy dose of competitor-bashing.

Essentially, the 90 minute event fell into a pattern of presentation that is becoming all too familiar in the past several Oracle Open World conferences. There are too many issues to list individually, but I'll point out what I see as some of the things I found most troubling in Oracle's presentation.

Oracle Exaggerates Its Cloud Apps Availability

Oracle claims 100 Oracle Fusion cloud services but provides no list of the applications. Seeing that Oracle announced five during Open World, it's difficult to understand how it is now claiming 100, unless it is talking about very small pieces of functionality. During the post-event analyst briefing, I believe Tom Kurian did promise to deliver a list--so we'll have to wait for that. Update: Oracle has provided the list.

Furthermore, not all of the capabilities that Oracle showed or referred to during the event are in general release. Tom Kurian did review what products were generally available, but I was not able to capture that information. Again, we'll have to wait for some public clarity from Oracle on what customers can buy today and what is still waiting for general availability.

Oracle's Developer Cloud Still in Controlled Availability

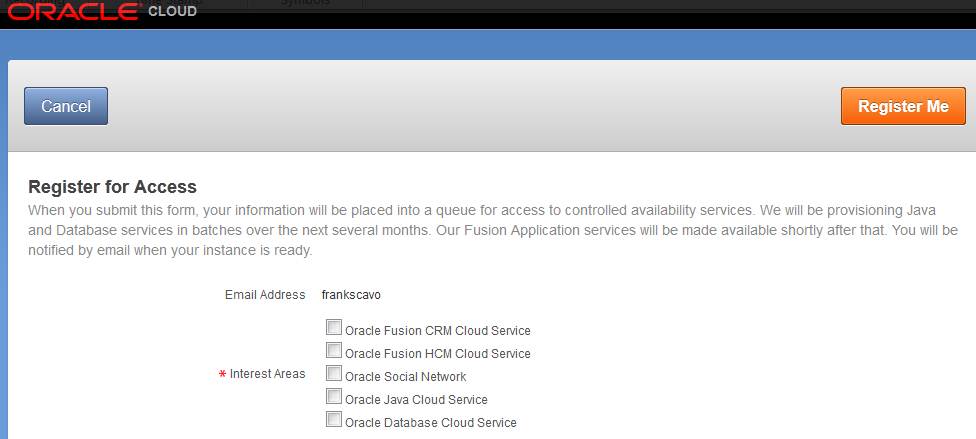
Specifically, Oracle Java Service and Database Service are not yet available via customer self-service, as shown in the screen shot below. With a public cloud infrastructure service, you should be able to walk up to the website, submit a credit card and gain instant access to a development environment, run it for a few hours or days, then shut it down. Amazon Web Services has offered this for years.

A quick test on the Oracle website shows that if you try to sign up for cloud services, you are led to a screen as shown below, where you can leave your contact information. The message on that page reads,

When you submit this form, your information will be placed into a queue for access to controlled availability services. We will be provisioning Java and Database services in batches over the next several months. Our Fusion Application services will be made available shortly after that. You will be notified by email when your instance is ready.

I questioned Tom Kurian on this point and he indicated that this is a temporary measure during the ramp-up period. He said that Oracle is currently signing up about 150 development customers a week for its Java and database services and that by the end of August, the sign up process should be available entirely on a self-service basis. But today-there is still friction at the point of sale.


Ellison is Rewriting History

At the beginning of his presentation, Ellison claimed that Oracle began to rebuild all of Oracle's applications for the cloud, calling it Project Fusion. But some of us have a long memory, and we've written blog posts on Oracle's Fusion program over the years.

At the beginning, Oracle did not pitch Fusion as a cloud program but as an integration strategy for its disparate applications. Fusion would be the successor to Oracle's E-Business Suite, PeopleSoft, J.D. Edwards, and Siebel systems. As Oracle made many acquisitions, it needed a strategy, using middleware, to integrate these applications with one another and a successor set of applications based on the best features of each of its acquisitions.

See my many posts at the end of this post, and try to find one where Oracle ever used the word "cloud" in talking about Fusion. Oracle has not been working on cloud applications for seven years. It has only been in the past year or two, as Salesforce.com and Workday began eating Oracle's lunch that Oracle responded with its own cloud pronouncements.

I have heard off-the-record that the early leaders in the Fusion group made sure to architect the product to allow cloud deployment. But Ellison's early presentations indicated that Fusion would be a traditional sold-as-a-license product, deployed on-premises, not a cloud service. To now claim that Fusion was a 7-year cloud development effort is simply not true.

Ellison's Characterization of Competitors is Out-of-Bounds

For example, Ellison claims that SAP has done nothing in the cloud except for its acquisition of SuccessFactors, and that it will have nothing otherwise in the cloud until 2020. He conveniently overlooks SAP's five or seven year effort to develop Business ByDesign, a full-suite multi-tenant cloud ERP system, which SAP has has sold to over 1,000 customers.

Whether SAP has met its objectives for ByD is not the point: Oracle has by its own numbers claimed only 200 sales of Oracle Fusion. So, even by Oracle's own numbers, SAP has sold more cloud customers with its own developed products. (Ellison also conveniently ignores SAP's own cloud-based line-of-business applications.) SAP may have its own problems in transitioning its business to the cloud, but Ellison's mockery of SAP is simply unfair and inaccurate. 

Ellison's slamming of the competition continued with a mis-characterization of Workday's in-memory technology and a straw-man argument that other SaaS providers tell customers "not to worry about security." Can Ellison point to any cloud competitor that has told its customers "not to worry about security?"

Oracle Exaggerates Adoption of Fusion Apps

Oracle claims just 200 sales of Oracle Fusion Apps, and it refuses to break down that number into how many are CRM, HCM, and so on. Although Oracle will not release that information, I have reason to believe that most of those sales are for HCM and that there have been few new sales of Fusion CRM.

Tellingly, there were no customers on stage with Ellison or Hurd. Except for a couple of slides with logos of companies that Oracle claimed as wins over its competitors, there were no customer mentions, no customer testimonies.

Oracle Customers Choose Cloud Because of Fusion Complexity

Back-channel discussions indicate that nearly all Oracle Fusion application sales are for cloud deployment, not on-premises. It appears that this is the case not because Fusion can only run in the cloud  (like Salesforce.com or Workday) but because Fusion technical requirements are so complex that virtually no organization wants to deploy Fusion Apps on-premises. It is easier to simply turn over the infrastructure and application management activities to Oracle.

On a Positive Note

The dissatisfaction felt by many of the event attendees is unfortunate. Oracle does have an impressive array of cloud services, although some are still in the process of roll-out.

  • Specifically, I like the fact that Oracle is offering a full and complete IaaS platform, similar to Amazon's (although Oracle's is limited to Oracle technologies).
     
  • I also like that everything in Oracle's cloud is based on public standards, such as SQL, Java, and HTML5. 
     
  • I like that customers can freely move applications (Oracle's apps, or custom apps) from Oracle's cloud to on-premise deployment, or to other public clouds such as Amazon's--without modification. I questioned Kurian on this point, and he confirmed that there is no intent to lock in customers to Oracle's cloud. This is, in fact, a differentiator against Salesforce.com as a development platform, which because it is based on proprietary languages, does not offer portability. 
     
  • Finally, the user interface or Oracle Fusion Application is cutting edge. From what I saw in the Ellison's demonstration, along with other Fusion apps I've seen demonstrated, Oracle has set a high bar for ease-of-use, embedded BI, and integration.

Oracle has fallen into a pattern in its public events of overstating its successes, misrepresenting its competitors, and touting statements-of-direction as accomplishments. This is unfortunate because it causes observers to discount what is in fact some very impressive technology. I hope that, in the future, Oracle will take a more understated approach that will do justice to its people, products, and services. 

Related Posts

Oracle's roadmap for Fusion Apps (2009)
More on Oracle's Fusion strategy
Oracle's Fusion strategy: clear as mud
Fusion to build on Oracle's E-Business Suite
Oracle going dark
Oracle's new reseller strategy and speculation on the future of JDE
Is Oracle's Fusion really half complete?
SAP slams Oracle's strategy as, Project Confusion

Tech Optimization

SuperNova Awards – Deadline Extended!

SuperNova Awards – Deadline Extended!

Good news for all the procrastinators (myself included) out there: we’ve extended the deadline for submissions for the SuperNova Awards! Please find the revised SuperNova Awards timeline below.

Timeline
- Submission deadline 6/22
- Judges Review 6/22 - 7/20
- Semifinalists announced and invited to Connected Enterprise 7/27
- Voting opens to the public 8/13
- Voting for finalists deadline 10/30
- SuperNova Awards winners announced 11/9


Procrastinators rejoice; you now have a few more weeks to submit your application! Overachievers also rejoice; you now have a few more weeks to submit additional entries in other categories!


The SuperNova Awards

The SuperNova Awards celebrate and recognize leaders and teams who have overcome the odds to successfully apply emerging and disruptive technologies within their organizations.  This annual search for innovators includes an all-star judging panel, substantial prizes, invite-only admission and speaking opportunities at Constellation's premier innovation summit - Connected Enterprise.


Download the SuperNova Award application.


We’re looking for innovators in the following categories:

  1. From Data to Decisions - Big Data, Data Quality, Decision Management, Insights, Information Management, Internet of Things, Master Data, Visualization Technologies
  2. Consumerization of IT (CoIT) and the New C-Suite - ByOD, Business Led Technology, Innovative IT and Business Collaboration, Shadow IT Co-Existence, Technology Strategy for C-Suite Execs.
  3. Future of Work - Collaboration, Getting Work Done, HCM, HR Technologies, Mobility in the Workspace, Productivity Apps, Social Business, Workspaces,
  4. Matrix Commerce - Demand Driven, Marketing Automation, Mobile Commerce, NFC, Payment Technologies, Perfect Orders, S&OP, Supply Chain, Virtual Goods,
  5. Next Gen Customer Experience - Context Services, CRM, Customer Loyalty, Customer Service, EFM, Gamification, Interactive Advertising, Location Based Services, Mobile Marketing, Reputation, Social CRM, User Experience And Design
  6. Technology Optimization and Innovation - Application Lifecycle, Business Value Frameworks, Cloud Strategies, Digital Identity and Security, Mobile Device Management, Outsourcing, Storage Strategies, Third Party Maintenance, Virtualization


Press Release: Constellation Research Appoints new Director of Lead Generation and Sales

Press Release: Constellation Research Appoints new Director of Lead Generation and Sales

Boston - May 22, 2012 Constellation Research, Inc., the award-winning research and advisory firm focused on helping clients navigate emerging and disruptive technologies, announced today the appointment of Sherrie King to the position of Director of Lead Generation and Sales. 

King is an accomplished technology sales professional with a ten-year track record of success. Previously King worked as Account Director at VDC Research where she worked with leading technology suppliers of automatic identification technologies. King also served as VP of Sales and marketing at Experture/Robert Frances Group where she led new sales development in Key F1000 accounts and coordinated research distribution networks across North America. 
 
Comments on the appointment:
“I am excited to be on the forefront of the next evolution of business advisory services," said Sherrie King, Director of Lead Generation and Sales at Constellation Research, Inc. " Constellation Research has built a service and delivery model that caters to the way enterprises leverage information in the 21st century.  I look forward to working with our top-notch analysts to deliver real personalization and value to our client partners.”
 
R "Ray" Wang, CEO, Constellation Research, Inc. said, "We're excited to have Sherrie on board.  Today we've been fortunate to have many word of mouth client referrals.  However, as we evolve and expand, we need Sherrie's expertise in crafting lead generation programs that attract clients who seek innovation beyond what today's legacy IT analyst firms provide.  We'll be adding more folks in this area and Sherrie's part of our longer term growth strategy." 
 
ABOUT CONSTELLATION RESEARCH, INC.
Constellation Research, Inc. is a research and advisory firm focused on disruptive and emerging technologies. This renowned group, led by R “Ray” Wang, focuses on business themed research including the Future of Work, Next Generation Customer Experience, Data to Decisions, Matrix Commerce, Technology Optimization and Innovation, and Consumerization of IT and the new C-Suite.

Constellation's collection of prestigious analysts bring real world experience, independence, and objectivity to client solutions that span cross-role, cross-functional, and cross-industry points of view. Clients join Constellation Research for a fresh and business focused perspective.

Unlike the legacy analyst firms, Constellation Research is disrupting how research is accessed, what topics are covered, and how clients can partner with a research firm to achieve success. Over 100 clients have joined from an ecosystem of buyers, partners, solution providers, c-suite, board of directors and vendor clients. 

For more information about Constellation Research, please visit http://www.constellationrg.com.

 
Contact the team directly at Contact[at]ConstellationRG[dot]com. 

***
Constellation Research, Constellation SuperNova Awards and the Constellation Research logo are trademarks of Constellation Research, Org. All other products and services listed herein are trademarks of their respective companies.

Monday's Musing: Avoiding Social Media Fatigue Through Engagement

Monday's Musing: Avoiding Social Media Fatigue Through Engagement

Social Media Moves From Ubiquitous Usage To Relevant Rationalization

Have we hit a social media plateau?  In recent client conversations on usage of social media, the trendsetters appear to be “socialed out”.   Most early adopters seem to be overwhelmed with their personal (Facebook, Google+), corporate (Yammer, Jive, Chatter, SharePoint), and professional (LinkedIn) social networks.  In fact, respondents feel that adding any additional network for anything social is quite overwhelming.  While early adopters are moving from ubiquitous usage to relevant rationalization, the majority remains in ubiquitous usage (see Figure 1).  Recent data on number of users at the Big 4 of social media show that we are in the middle of ubiquitous usage:

  • Facebook (901M users as of Feb 2012)
  • Twitter (500M users as of March 2012)
  • LinkedIn (161M users as of March 2012)
  • Google+ (100M users as of Feb 2012)

Early Adopters Facing Social Media Fatigue

As early adopters start rationalizing their networks, some are even pulling out.  From loss of interest in Google+, Empire Avenue, to even FaceBook, people have started to selectively choose networks to combat overload and social media fatigue.  The common theme – relevant rationalization by self-interest.   These trends parallel those for mail, phone, email, web and other disruptive technologies.  Going forward, users will move towards desensitization when the advertisers and companies abuse the channel by spamming users with an unwanted deluge of irrelevant offers.

The Bottom Line: Engage Users To Combat Fatal Fatigue In The Disruptive Tech Adoption Life Cycle

Every new medium or technology goes through this life cycle. To combat Phase 4, Fatal Fatigue and cross over to Revival and Rejuvenation, organizations must engage their users during relevant rationalization in order to keep customers through Fatal Fatigue and Revival and Rejuvenation.  Here’s the five phases of the disruptive technology life cycle:

  • Phase 1: Eager early adopters. Users eagerly experimented in the newness of the medium.   Early adopters attempt to apply the medium to everything.
  • Phase 2: Ubiquitous usage. Rapid adoption put the medium in the hands of the masses.  Adoption exceeds 50 million users.
  • Phase 3: Relevant rationalization. Brands and enterprises apply the medium to the right business use cases and processes.
  • Phase 4: Fatal fatigue. Inundated with marketing, bombarded with irrelevant content, and tired of the newness of the medium, customers begin tuning out.
  • Phase 5: Revival and Rejuvenation. Maturation of the medium ushers an improved era of engagement apply the Six C’s of Engagement.

Success will require organizations to engage their customers and employees.  Find out more in the Harvard Business Review blog post here.

Figure 1. Disruptive technologies follow an adoption life cycle that must overcome fatigue to succeed

Your POV.

Ready to avoid Fatal Fatigue? Have a story on how you’ve achieved engagement? Add your comments to the blog or send us a comment at R (at) SoftwareInsider (dot) org or R (at) ConstellationRG (dot) com

Please let us know if you need help with your Social CRM/ Social Business efforts.  Here’s how we can assist:

  • Assessing social business/social CRM readiness
  • Developing your social business/ social CRM  strategy
  • Vendor selection
  • Implementation partner selection
  • Connecting with other pioneers
  • Sharing best practices
  • Designing a next gen apps strategy
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Related Research:

Reprints

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales .

Disclosure

Although we work closely with many mega software vendors, we want you to trust us. For the full disclosure policy, stay tuned for the full client list on the Constellation Research website.

* Not responsible for any factual errors or omissions.  However, happy to correct any errors upon email receipt.

Copyright © 2001 – 2012 R Wang and Insider Associates, LLC All rights reserved.
Contact the Sales team to purchase this report on a a la carte basis or join the Constellation Customer Experience!


New C-Suite Marketing Transformation Future of Work Innovation & Product-led Growth Leadership Chief Experience Officer

NetSuite Manufacturing: Right Direction, Long Road Ahead

NetSuite Manufacturing: Right Direction, Long Road Ahead

As one of the first cloud ERP providers, NetSuite is looking to grow its customer base across multiple industries and up-market to larger customers. Those efforts include NetSuite’s renewed focus on the manufacturing sector, as unveiled at NetSuite’s annual user conference, which I attended this week.

Bottom Line: NetSuite is making the right decision and good progress to build out manufacturing functionality as part of its core system, but there is still much work to be done to achieve functional parity with other cloud and on-premises solutions in the marketplace. Nevertheless, the rapid development capabilities of NetSuite's platform offer hope that it will get there quickly.

From Partner Solutions to a Core Offering

Until recently, NetSuite’s approach to serving manufacturers was to provide what it called “light manufacturing,” coupled with customer-specific customizations, supplemented by partner solutions such as Rootstock when heavier manufacturing functionality was required. But this approach could only take NetSuite only so far.

  • Support for manufacturers is essential in light of NetSuite’s product strategy. As explained by Zach Nelson in a small group briefing, the customer order is central entity in NetSuite, and NetSuite wants to “own” anything that is input into, or output from, the customer order. In the manufacturing sector, this would include production work orders. It makes no sense, therefore, for NetSuite to hand off these business processes to partners.
  • At the same time, the manufacturing sector represents a large potential market for NetSuite. There are more manufacturing companies—especially small manufacturers—in the US than in any other sector. Inadequately serving such a large potential market made no sense as NetSuite looked to accelerate its growth.
  • However, some basic features for manufacturers have been missing. For example, standard costing were not addressed in the core product, and few prospects would be willing to customize their implementations for such a fundamental need.

As a result of this realization, NetSuite in 2011 began work in earnest to build out its manufacturing functionality. In a briefing during NetSuite's conference I met the key players hired for this mission. They include:

  • Roman Bukary, Head of Manufacturing and Distribution Industries. Roman previously worked for SAP, Baan, and other software companies. Earlier in his career, he was a manufacturing engineer.
  • Ranga Bodla, Director, Industry Marketing. Ranga held product management positions at SAP and Pilot Software.
  • Thad Johnson, Sr. Product Manager for Wholesale Distribution and Manufacturing Verticals. Earlier in his career, Thad was a product manager at QAD and also held several materials management positions in industry.
  • Frank Vettese, Practice Manager. Frank has manufacturing software experience with IFS and Effective Management Systems.
  • Gavin Davidson, Vertical Market Expert, Manufacturing. Gavin’s experience includes implementation work with manufacturing systems from Baan, Epicor, Microsoft Dynamics, and Visual.

I’m pointing out the experience of these individuals to show that NetSuite’s push into manufacturing is more than a marketing campaign. It has put together a serious team of individuals to lead the product development effort for this vertical.

An Expanding Footprint

In terms of manufacturing methods, NetSuite is primarily targeting discrete manufacturers although it intends to provide some support for process manufacturing down the road. An ideal prospect would be a discrete manufacturer that does a mix of in-house and contract production.

Let’s take a look at some of the manufacturing functionality that NetSuite has recently added or will be adding. From these few points we can get a sense for where NetSuite is in its current and near-term ability to better support manufacturing customers.

  • Standard costing. As mentioned above, the lack of this capability in the past was a showstopper for many manufacturing prospects. But NetSuite reports that it added this capability in 2011, along with standard cost rollups.
  • Bills of material. NetSuite has had BOM capabilities for some time, and it will soon support revision levels on BOMs along with effectivity dates. Users can also set a default scrap percentage on BOM components. Support for alternate BOMs is not in the roadmap.
  • Routings. NetSuite added production routings to the standard system in 2011. These, of course, are used to create production work orders. Alternate routings will not be provided. .
  • Cycle counting. Standard NetSuite code will now support cycle counting of inventory by ABC code.
  • Material Requirements Planning (MRP). NetSuite now does a BOM explosion, but it does not generate reschedule messages for purchase orders or production work orders. Neither does it support all types of lot-sizing methods.
  • Unit of measure conversions for purchasing, receiving, and inventory management have been part of the standard system for some time.
  • Multi-facility planning. It appears that NetSuite will allow customers to maintain separate material plans for multiple facilities while still providing a global view of inventory. If so, this would go beyond what is typically offered in most Tier III on-premises manufacturing systems.
  • Labor reporting. The team demonstrated a basic clock-in, clock out process using a tablet computer that can be used to report production completions and labor from the shop floor. This capability is currently in proof-of-concept.
  • Capacity Planning will be supported, based on the NetSuite’s “demand plan,” but it does not appear that it will highlight capacity constraints as it will not track available work center capacity.
  • Inventory Allocations and Available-to-Promise (ATP). This basic capability—to allocate available inventory and scheduled receipts against customer orders, and to provide visibility into projected inventory availability—is also scheduled as part of standard NetSuite functionality. (Kudos to NetSuite CTO Evan Goldberg for providing a layman’s explanation of ATP during his keynote.)
  • Lot and serial number traceability. The team claims capabilities in tracing lot numbers and serial numbers from receipt through production into finished goods. I did not have a chance to verify this functionality, but if present, it would be of interest for a number of manufacturing sub-sectors such as high tech electronics and medical devices.

I believe that NetSuite means business in pursuing the manufacturing sector. However, as can be seen, many of these capabilities (e.g. routings, cycle counting, labor reporting) are very basic manufacturing requirements, things that have been present in systems such as ManMan, AMAPS, BPCS, and others back into the 1980s. Furthermore, some of the planned capabilities will lack key things that a manufacturing prospect would expect. For example, the team characterized NetSuite’s material planning system as a “lean manufacturing system,” which to me is a polite way of saying, “minimal.”

Contrast this with NetSuite’s current capabilities and roadmap for eCommerce (SuiteCommerce) or support for back-office processes of software vendors, which go far beyond what most other ERP providers offer.

Now, it may be that the major opportunities for NetSuite will not be in the hard-core job shops or industrial manufacturing companies. Inasmuch as many manufacturing companies in the United States and elsewhere in the world are outsourcing much of their heavy production processes, it might be that the feature set in NetSuite’s roadmap will be enough to satisfy the majority of its target manufacturing market.

The Time and Place for Customization

One thing that I do not think will satisfy such prospects, however, is the use of customization to fill basic functionality gaps. NetSuite promotes its ability to augment its standard processing with customer-developed or partner-developed customizations, without modifying standard NetSuite code. During his keynote, Evan Goldberg gave an impressive demonstration of the latest version of NetSuite’s development platform, SuiteCloud. I continue to be impressed with the ease-of-use that providers such as NetSuite and Salesforce.com are delivering with their Platform-as-a-Service offerings.

However, the ability to customize and extend the solution should not be taken as an excuse for not offering expected features/functions in the standard product. When prospects need full-blown work center capacity planning, for example, the last thing they want to hear is, “Oh, we can use SuiteCloud to build whatever you need.” For customer-unique requirements, SuiteCloud is a powerful attraction. For what should be standard functionality, no.

Rapid Progress Possible

I’m encouraged by NetSuite’s renewed interest in serving the needs of the manufacturing sector. However the feature set currently in the roadmap does not go as far as I would like to see in building comprehensive functionality for manufacturers. Nevertheless, I believe NetSuite will see success with its product strategy for two reasons. First, as mentioned earlier, it may be that a comprehensive footprint is really not needed to serve the majority of prospects. Second, NetSuite’s cloud platform—like other PaaS systems—offers a rapid development environment. NetSuite will certainly make more rapid progress in filling out its feature set than it would if it were a traditional on-premises vendor.

Compared to the services industries, the number of cloud ERP providers for manufacturers has been limited. But with NetSuite’s renewed focus, the list is now getting a little longer.

Disclosure: NetSuite paid for my travel expenses for its user conference in San Francisco

Related Posts

NetSuite a Viable Alternative for SAP Customers
Key success factor for SaaS suites: functional parity
Kenandy: A New Cloud ERP Provider Emerges from Stealth Mode
The Simplicity and Agility of Zero-Upgrades in Cloud ERP

Tech Optimization

Friday's Features: Using Attensity Analyze 6.0 To Compare Customer Sentiment For @united @southwestair @virginamerica

Friday's Features: Using Attensity Analyze 6.0 To Compare Customer Sentiment For @united @southwestair @virginamerica

A Travelers’ Tale of Two Airlines (@united vs @southwestair)

A hurried shower, followed by a hastily packed bag.  Then, the race to the taxi stand (Figure 1).  Should be easy to get a cab at 5:45 am in Las Vegas, right? Only the late night crew roll into a casino this late or early in the morning on a Tuesday.  Who’d be flying out so early?  So much for that theory.  A line forms 50 deep outside. Eveyone is half asleep, and headed to McCarran – Las Vegas airport from Caesar’s Palace at 5:30 am.  I figure Southwest 2286 takes off at 6:25 am, should be plenty of time.  I keep consoling myself.  At 5:50, I get into my cab. I instruct the driver not to take the freeway and to go local.

Figure 1. Just Another Day At The Las Vegas Taxi Stand

I get to the self-service kiosk to check in. I get the dreaded .  I’m told my bag will be checked late and it could risk being sent on a later flight.  At 6:00, I’ve missed all normal cut-off windows.  Most airlines cut you off at 30 minutes prior and I am really late.  I’m ready to accept my fate.  I’m ready to be told to get on the next flight.  Strangely enough, the gate agent notices that I’m late and does everything to hurry me on-board.  She tells me that there is a chance my bag won’t make it but they’ll do their best.  She kindly reminds me check-in is 30 minutes prior and suggests I take another security entrance to improve my odds of passing through TSA in time.  She also lets me know that she’s told the gate agent I may be late.  I finally get through TSA and get to the gate with 2 minutes to spare.  The aircraft door isn’t closed. In fact, it’s open and waiting for me to board. I hop on, pass out, and arrive in San Jose.  In some modern day miracle, the bag also has arrived with me.  I thank the travel gods.

Flash back one week earlier, the same morning sequence occurs in Las Vegas.  This time with rental car in tow, I head to the rental car return center at 4:00am for a 5:30 am flight.  A staffing issue occurs with the “consolidated rental center transportation” and no buses arrive until 4:30 am.  I think to myself, I still have time.  I rush to catch United Airlines 479 to San Francisco.  The bus arrives at 4:45 am.  I rush to the kiosk and arrive for check-in at 4:47 am.  The kiosk tells me to see an agent. I wait another 3 minutes in the uber premium line (a.k.a. Global Services).   The agent looks at my ticket and tells me in a stern and disapproving voice, I have to wait for the next flight which is at 11:49 am.

I flash my Global Services card in a last ditch attempt for empathy.  The agent tells me that policy is policy.  United can’t check me in as I miss the cut-off.  She tells me that I should know better and come to the airport earlier.  The Las Vegas airport is so big, the bag would never get to the plane on time.  They won’t let me take off without my bag.   There’s no point in arguing at this point. I have a speech at 11:00 am to get to.  I rush over to the Southwest counter to find the next flight.  The agent asks me what’s wrong. I tell her I need to get on the 6:30 am.  She says, no problem.  I give her all the details and she issues me a ticket in 5 minutes.  I make it to the keynote but I’m very bitter about United and how they have treated me.  I was a happy Continental flyer before the merger, you can read all about it here.

Social Data Quantifies Qualitative Experiences – United Ranks Last Among The Three Carriers

By now, most folks have seen what happened when “United Breaks Guitars“, the tale of an awful customer experience for Dave Carroll who had his guitar broken.  When the airline failed to take responsibility, he took to the web.   With over 11.9M views as of this blog post, this social media epic fail epitomizes what happens when companies ignore their customers and shirk responsibility for resolving legitimate complaints.  But what happens when an airline completely chooses to ignore social media as a channel? Do customers go away? Do they just jump to another channel?  Are these social analytics tools reflective of the general customer base?

Using Attensity Analyze 6.0, a comparison was made among the three airlines.  We selected two best in class low cost carriers (i.e. Southwest Airlines and Virgin America) and United Airlines to answer this question (Figure 1).  Analyze 6.0 took 12,863 public comments from Facebook, Twitter, blogs, forums (user forums, discussion forums, LinkedIn Answers, etc) YouTube videos, mainstream news and more to gather this data (see Figure 2).

Figure 1. Twitter Accounts For The Three Airlines

Figure 2.  Attensity’s Analyze 6.0 In Action With Feedback Analysis On Three Select Airlines

In the social media feedback analysis, the Attensity Analyze report measured 3 major performance indicators:

  1. Share of voice. At about 40%, the bulk of the mentions come from Virgin America, with United at about 35%, and Southwest a bit over 20% in category share.  Virgin’s share of voice is disproportionately higher than United’s who has a larger network more routes, more destinations, more planes (see Figure 3).  Southwest Airlines has almost 11 times the followers of United.  Both Southwest Airlines and Virgin America have put out 3 times more tweets than United.

    Figure 3. Despite Size, Virgin Has Huge Share of Voice

  2. Sentiment by airline. The low cost carriers appear to have cracked the customer service challenge in social media better than United and other legacy airlines.  Virgin America’s positive sentiment hovers above 75% positive while Southwest Airlines held at slightly over 70% positive (see Figure 4).  United’s sentiment shows an inverse with around 26% positive sentiment and 74% negative sentiment.  The public tweets posted per follower (between .007 and .027) for United is comparable to Southwest Airlines.  Ironically, Virgin America has a lower public tweets posted per follower count, but has higher positive sentiment than United.

    Figure 4. Virgin and Southwest Have Overwhelmingly High Positive Sentiment While United’s Negative Sentiment Sets It Apart

  3. Detailed sentiment (positive or negative).  The solution automatically creates categories that users can modify or leave as-is for further analysis (see Figure 5).  A text preview allows users to quickly scan the comments related to the twitter stress.  In United’s case, poor sentiment translates into three major areas for massive improvement: customer treatment, flight schedules, and hate airline rounded up the Top 3 negative sentiments.

    Figure 5. United’s Detailed Negative Sentiment

The Bottom Line: Companies Such As United Airlines Can’t Hide In A Transparent World

In this shift from transactions to engagement, social business and customer experience shifts the priorities of major organizations.  Organizations must staff, train, and enhance how their front office employees work with prospects and customers in multiple channels.  Social media makes everything transparent and any competitor can monitor your company’s social presence.  Hoping that folks will ignore you if you ignore social media is a sure way to drive negative sentiment for your customer base.  While United Airlines may feel insulated by its corporate contracts, expect many individuals to tell their procurement organizations to switch carriers this year as the negative sentiment for United grows.  In fact, companies such as United Airlines better wake up to the reality of social media or face an eroding customer base.

Recommendations:  Always Start With Listening Before Engagement

All social business projects should start with an analytics strategy.  The following advice comes from client best practices in our client research panels:

  • Scan your base for correlations to the analog world. Make sure results in social tie have relevance to not only a segment, but also the rest of the customer and prospect base.  A industrial ball bearing manufacturer for heavy machinery probably will not find strong correlations and adoption to their FaceBook page.
  • Identify new markets by listening in on your competitors’ customers. Understand thyself first but understand thy competitors and find out what product categories, vertical markets, geographies, and sentiments are hot.
  • Add dimensionality. Take analytics to the next level and aggregate inputs and signals from all source types.  Tie back data to existing customer systems.
  • Move from insight to action. Determine the next steps once armed with insights.  Improve the quality and timeliness of decisions.
  • Refine. Remix. Repeat. Identify points of failure. Improve on these areas. Test out new areas with new hypotheses.

Your POV.

Considering social analytics? Are you ready to take the plunge? Tell us how we can assist?  Add your comments to the blog or send us a comment at R (at) SoftwareInsider (dot) org or R (at) ConstellationRG (dot) com

Please let us know if you need help with your Social CRM/ Social Business efforts.  Here’s how we can assist:

  • Assessing social business/social CRM readiness
  • Developing your social business/ social CRM  strategy
  • Vendor selection
  • Implementation partner selection
  • Connecting with other pioneers
  • Sharing best practices
  • Designing a next gen apps strategy
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing

Related Research:

Reprints

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales .

Disclosure

Although we work closely with many mega software vendors, we want you to trust us. For the full disclosure policy, stay tuned for the full client list on the Constellation Research website.

* Not responsible for any factual errors or omissions.  However, happy to correct any errors upon email receipt.

Copyright © 2001 – 2012 R Wang and Insider Associates, LLC All rights reserved.
Contact the Sales team to purchase this report on a a la carte basis or join the Constellation Customer Experience!


Matrix Commerce Next-Generation Customer Experience Innovation & Product-led Growth Leadership Chief Experience Officer

Cisco's Customer Collaboration Analyst Event Highlights

Cisco's Customer Collaboration Analyst Event Highlights

Two themes emerged from  Cisco’s Collaboration Analyst event were the delivery  and execution of strategic initiatives announced previously and the strong push to grow market share at Avaya’s and Genesys’ expense.  The highly packed agenda did a good job of presenting Cisco’s current market plans and major areas of focus.  By selling the “Cisco” story, the company hopes to drive higher adoptions for its customer collaboration contact center line of products, while also validating the improvements and enhancements made in its contact center product line during the last five years.

Cisco has done a remarkable job of expanding its market share and divides its customers into three segments:

  • High touch customer segment.  These are the large enterprise customers that want full featured and highly customized solutions.  This is the area that has been dominated by Avaya for many years, followed by Genesys.  Cisco’s product for this segment is the Contact Center Enterprise edition.
  • Mass Market segment.  These are mid-sized and large customers that require the scalability and features of the contact center enterprise but have less need for a highly customized solution.  Cisco’s product for its mass market customers is the Contact Center Enterprise Packaged edition.  By packaging several of its applications, Cisco can reduce its list price by 20% and offer a simpler solution for its services partners to install.
  • Attached market.  These are the customers who buy Cisco’s Unified Communication Manager and have smaller contact centers.  Cisco sells its Contact Center Express package to this segment.  An advantage of its Express is the large number of certified resellers, making it easier for more partners to sell and install.

Cisco’s next release (9.0)  coming out next month offers several enhancements but does not reveal any surprises  The four pillars that make up the Cisco customer collaboration experience include the following:

  • Mobile connectivity.  Cisco embraces the adoption of mobile devices by its customers and wants to provide secure access to information and people.  They have a new mobile application for administrators or supervisors that allow them to make changes in agent assignments directly from their mobile device.   With strong support for mobile devices and tablets, Cisco’s offers solutions to support customers anywhere.  However, Cisco does not have a productized offering for mobile application support that would connect customers directly from the mobile app into the contact centers. 
  • Social Customer care.  This offering provides social media agent support across all market sizes and includes queuing of social media contacts as email notifications.
  • Visual Support.  This enables customer collaboration on video from kiosks, smart phones, and desktops to support rich media interactions.  Cisco views video as a growing market with strong opportunity but admits video is still relatively small for contact center interactions today.
  • Virtual support.   Cisco offers server and desktop virtualization with Finesse Agent and Supervisor desktops, which reduces costs for hardware and system management.  Virtualization is also important for extending contact center connectivity to the expanding population of home agents.

Cisco’s announcements show progress in shrinking its product gaps in areas, such as reporting and analytics, email and Web integration and precision routing.  These are all positive moves that will improve its competitiveness in the market.  While advances on its core product are extremely important, I did not see a lot of innovation with customer examples but expect its extensive developer community will continue to create inventive improvements for its product line.  For Cisco competitors, I think there is something to be learned by Cisco’s intense focus to build up market share in the contact center.  Competitors cannot ignore the smaller end of the market and only focus on the higher end, as Cisco continues to gain strength across all its market segments.

Next-Generation Customer Experience

The Simplicity and Agility of Zero-Upgrades in Cloud ERP

The Simplicity and Agility of Zero-Upgrades in Cloud ERP

I am coming to the conclusion that a primary benefit of cloud ERP is the reduction or complete elimination of version upgrades. This observation was reinforced again this week in my one day attendance at the Plex Systems user conference in Indianapolis. Plex is a great example of what a cloud ERP vendor can accomplish by taking what I call a “zero upgrades” product strategy.

The Goal: Zero Upgrades

Originally founded in 1995, Plex went through a complete product overhaul in 2001, when it completely rewrote its ERP system as a cloud offering. At the time, NetSuite was the only other product that came close to cloud ERP and even then, NetSuite was largely a financials-only service.

Interestingly, in my interview this week with CEO Mark Symonds, becoming a “cloud ERP” provider was not their primary goal, but rather a means to an end. Passing through the client-server era, Plex grew tired of the difficulty in getting customers upgraded to new versions and rolling out patches and fixes to its installed base. The move to an online system (Plex Online)—the term “cloud computing” had not yet been coined—was the means by which Plex would to solve this problem. Customers would not have their own installations of the system. Rather they would access one central instance of Plex, which would be developed and maintained directly by Plex. Customers would never have to upgrade.

Implications of Zero Upgrades

Actually, I've known about the Plex approach for some time. But the implications of this strategy became more apparent as I sat through the keynote and some of the individual workshops.

  1. You Like It? You’ve Already Got It. A good part of the opening keynote included the announcement and live demo of a new embedded report writer, called IntelliPlex. Now I wouldn’t say that the demo blew me away. It's good. It has an easy drag-and-drop method to allow users to create their own reports, generate charts and graphs, calculate new columns based on formulas, produce pivot tables and cross-tabs—all good stuff. Is it as powerful as the embedded BI capabilities that other vendors have demonstrated recently? In some cases, no.

    But here’s the catch. Every Plex customer watching that demo knew that they could immediately log on to their Plex system and have access to that report writer. They don’t need to order it, pay separately for it, install it, or be on a certain version of Plex to use it. Perhaps that’s the reason I didn’t see a single person walk out early from that keynote.
     
  2. Functionality is Front and Center. I attend a lot of vendor conferences. Many of the sessions are taken up with subjects such as “Planning for Version X,” “What’s New in Release 7.2.345b,” “Prerequisites for Migrating Product X to Version Y of Database Z.” The Plex conference has none of these tactical, infrastructure-type subjects. All attention is on what the software does, not what you need to do to get it to do those things.

    For example, I sat in on part of a presentation on work center production scheduling—not a subject that I would consider a major draw. In much larger vendor conferences, I might see 20 or 30 people in this sort of presentation. But, as shown in the photo nearby, there were about 150 (out of 800 total) conference attendees in this session. Because Plex users do not have upgrades to deal with and plan for, they can devote all of their time to learning how to use the functionality that they already have access to. There appeared to me to be a much greater percentage of line-of-business users than I see in many vendor events.
     
  3. User-driven Enhancements. Plex’s approach frees it from having to spend time managing multiple versions of its product, creating sandboxes, and phasing in customers from one version to the next. This gives its developers more time to work on product enhancements, which are largely driven by customer-funded requests. Although one customer may fund a change, all customers have the option to “flip the switch” and use it if they so choose, without having to schedule a version upgrade. All new functionality is delivered with the switch set “off,” so that individual customers can choose what and when to implement it.

Ultimately, the zero upgrades strategy enables business agility for customers. This point was stressed to me in an interview I did with Plex customer Ben Stewart of Inteva. His company has a growth-by-acquisition strategy and needs to be able to bring new plants and new locations on-board quickly. Plex’s zero upgrade approach and rapid response to his change requests (e.g. enable a new EDI partner) supports this strategy of agility to accommodate rapid change. Other customers report Plex implementations of new plants in timeframes of weeks, not months.

Are There Downsides?

I have discussed the zero upgrades approach with other cloud ERP vendors, and many of them disagree. They maintain that ERP is different from CRM or other non-critical applications, that cloud customers want control over their environments, that they want to choose when to upgrade and to be able to regression-test their business processes against new versions. In some cases, I think this is simply a legacy of the on-premises world: we’ve always released new functionality as version upgrades. In other cases, I believe that this position is taken for the vendor’s convenience, especially when their cloud ERP systems are using the same code base as their on-premises systems. Because the on-premises customers have to have version upgrades, the cloud ERP customers of the same system must also have version upgrades. Otherwise, the two classes of customers do not have the same code base.

This does not mean I am against the hybrid model—allowing a customer to run the same system on-premises and in the cloud, or to go from one deployment model to another. I have written that there are some advantages to the hybrid model. But forcing customers to do version upgrades is not one of them.

There is one scenario, however, where version upgrades are desirable, and that is in a regulated environment, an area I have some experience in. For example, current US FDA regulations require pharmaceutical and medical device manufacturers to demonstrate that they have control over software configurations that are used to support regulated processes. This does not necessarily rule out use of cloud computing, but it does make it difficult to claim that the user has control over the system if the vendor is changing it on a daily basis. In such cases, it is easier to defend the use of a cloud ERP version that is frozen in its configuration, where the customer can choose when to upgrade and can run testing to confirm acceptance of the new version prior to upgrade. In non-regulated environments, however, I believe that the Plex practice of delivering new functionality “with the switch turned off” is better, as it promotes agility.

Some may argue that the Plex approach may lead to bugs being introduced into the production system on a daily basis. For example, Plex may implement a new feature in one part of the system and it may affect processing in another part of the system—even though a customer may not flip the switch for the new functionality. One long-standing Plex customer indicated that this does happen from time to time, but still he is strongly in favor of the zero-upgrades approach. I would add, I have seen many cases where traditional on-premises vendors ship code that notoriously bug-ridden, where they are shipping “patch releases” for months, even years, later. At least with the Plex approach, when bugs are discovered, they can be fixed in a few hours.

One final issue has to do with the practice of letting customers drive new enhancements. This approach may have worked well when Plex was small, but I question its wisdom as Plex scales. If uncontrolled, this can lead to many one-off enhancements being introduced into the core system, which only pertain to a single customer.

Fortunately, I heard two things during the conference that mitigate this problem. One is that Plex is establishing a formal product management function to review and clear all customer change requests and to evaluate which ones have merit for multiple customers. Second, Plex has introduced a web services platform capability called VisionPlex, which allows customers and partners to develop their own enhancements to interoperate with Plex, but outside of the core systems. This capability is just being rolled out in several pilot projects, but if successful it will go a long way toward keeping one-off enhancements out of the core system. It also has the benefit of enabling an ecosystem of Plex partners to build on Plex as a platform—something that has been lacking to date in Plex’s strategy.

Plex is not a large cloud ERP vendor, having only about 750 customers. It is narrowly focused on a few manufacturing industries, such as automotive, industrial products, plastics, electronics, and a few others. However, it is showing strong and steady growth—30% revenue growth in 2011 and expecting 20% growth in 2012. Furthermore, it is an existence proof for the principle that a zero-upgrades product strategy has major benefits for both customers and the vendor.

Related Posts

Plex Online: Pure SaaS for Manufacturing
Computer Economics: Cloud Players Storm the Gates of ERP
Key success factor for SaaS suites: functional parity

Tech Optimization

News Analysis: Informatica Launches MDM 9.5

News Analysis: Informatica Launches MDM 9.5

New Product Addresses The Social, Mobile, Cloud, and Big Data World

The convergence of social, mobile, cloud, big data (analytics), and video/unified comms changes the playing field from transactional applications to engagement applications.  The result – a sea change of new data types from structured and unstructured sources.  With greater volumes of data, demand for information shifts from real time to right time inside and outside the enterprise.  Context by process, by roles, by location, and by any other segmentation requires a robust MDM solution to improve the return on #bigdata.  Unfortunately, many master data management solutions have not been designed to handle this new world of business led requirements.

Enter Informatica’s MDM 9.5 product launched May 15th, 2012 at Informatica World (#IW2012).  Some key features in 9.5 highlight the move to social, mobile, cloud, and industries:

  • Versioning – effective dates deliver timelines. The new product delivers effective dating to define and manage past, current, and future versions of a record.  Delivered at the base object level, relationships are automatically version-enabled.

    Point of View (POV): Future analysis of social and mobile data will require the ability to segment and correlate by time.  The solution can model hierarchies and entities by past, present and future. More importantly, versioning provides rich compliance information that will serve as a backbone for information governance of a wide variety of data types and sources..
  • Social MDM – Facebook apps connect to customer profiles. The new Facebook and MDM connectivity provides a social graph of the customer and friends of the customer. Users gain bi-directional connectivity.

    Point of View (POV): Connection to Facebook not only brings rich profile information, but also delivers key multichannel connections.  This linkage exposes and identifies common interests and relationships which build richer customer profiles.  Customers should work hard to drive data out of Facebook and not into Facebook, reducing the trading of privacy for convenience.
  • Mobile MDM – iPad app changes the user experience. Informatica 9.5 MDM delivers mobile location based services with master data for location specific customer information.  Solution accounts for social features including website access and Twitter.

    Point of View (POV): Mobile has emerged as the predominant user interface of choice.  Users expect to gain any time, anywhere access to key data.  More importantly, MDM 9.5  prepares users for a world of social, mobile, and geo location convergence.
  • MDM Solutions For Industries. Informatica’s delivered updates to industry solutions in Counterparty (Financials), Pharma, and Reference Data Management.  MDM 9.5 adds a new SFDC MDM gateway and Insurance 1.0 solution.

    Point of View (POV): The move to industries makes sense for customers looking to jump start their implementations.  Expect retail, CPG manufacturing, consumer electronic goods, oil & gas, healthcare, and public sector to show up next on the road map.  Industry specific deployment models provide significant advantages for partners to build on top of Informatica MDM 9.5

The Bottom Line: Informatica’s Building MDM For The Next Generation Of Engagement

The road from transaction to engagement requires strong master data management to bring order and business value to the chaos of #bigdata. Constellation predicts that 87% of organizations will enter best of breed “cloud hell” by the end of 2013, the challenge of data integration must meet strong information governance. Master data management remains a critical skill set required for enterprises to deliver on business agility and provide the needed infrastructure for adopting disruptive technologies and new business models.

Your POV.

Have you deployed social, mobile, or cloud?  Are you ready to take your master data management to the next level?  Got a question?  Add your comments to the blog or reach me via email: R (at) ConstellationRG (dot) com or R (at) SoftwareInsider (dot) com.

Please let us know if you need help with your Social CRM/ Social Business efforts.  Here’s how we can assist:

  • Assessing social business/social CRM and master data management readiness
  • Developing your social business/ social CRM  and MDM strategy
  • Vendor selection
  • Implementation partner selection
  • Connecting with other pioneers
  • Sharing best practices
  • Designing a next gen apps strategy
  • Providing contract negotiations and software licensing support
  • Demystifying software licensing


Related Research

Reprints

Reprints can be purchased through Constellation Research, Inc. To request official reprints in PDF format, please contact Sales .

Disclosure

Although we work closely with many mega software vendors, we want you to trust us. For the full disclosure policy, stay tuned for the full client list on the Constellation Research website.

* Not responsible for any factual errors or omissions.  However, happy to correct any errors upon email receipt.

Copyright © 2001 – 2012 R Wang and Insider Associates, LLC All rights reserved.
Contact the Sales team to purchase this report on a a la carte basis or join the Constellation Customer Experience!


Data to Decisions Tech Optimization Innovation & Product-led Growth Leadership Chief Experience Officer