


Snowflake Q2 growth surges on AI and data demand
Snowflake's revenue growth accelerated to 37% in the second quarter as the company continues to see strong demand for its data platform due to AI.
The company reported a second quarter net loss of $191.7 million, or 55 cents a share, on revenue of $1.546 billion. Non-GAAP earnings were 62 cents a share.
Wall Street was looking for non-GAAP earnings of 45 cents a share on revenue of $1.48 billion.
CEO Sridhar Ramaswamy said "AI continues to compound our advantages, creating a flywheel effect across the business. CoWork and CoCo are driving transformational outcomes for our customers, while fueling rapid adoption, user growth, new workloads, and overall platform consumption."
- Snowflake to add dynamic model routing to Cortex AI Gateway
- Constellation ShortList™ Customer Data Platform (CDP)
- Constellation ShortList™ Metadata Management & Data Governance
- Constellation ShortList™ Semantic & Context Management for Analytics and AI
- Snowflake Summit 2026: Redrawing the Boundary Between Data, Context, and Action
- Snowflake Summit 2026: Context, custom model training, Iceberg V3
By the numbers:
- Snowflake CoCo topped 9,100 accounts in the second quarter and Snowflake CoWork had 5,800 accounts.
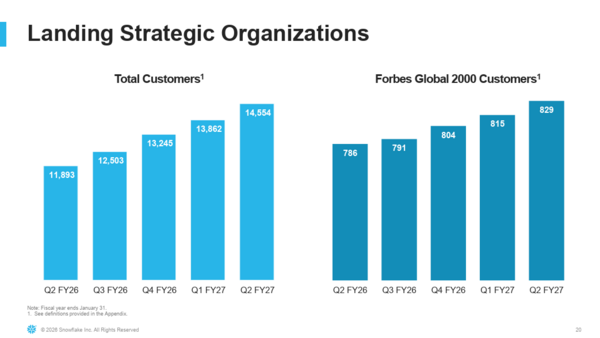
- The company added 692 net new customers in the quarter.
- Snowflake reported 828 customers with trailing 12-month product revenue topping $1 million, up 27% from a year ago.
- Remaining performance obligations were $9 billion, up 30% from a year ago.
As for the outlook, Snowflake projected third quarter product revenue of $1.588 billion to $1.593 billion, up 37% to 38%. Non-GAAP operating margins will be 15.5%.
For fiscal 2027, Snowflake projected product revenue of $6.07 billion, up 36% from a year ago. Operating margins will be 14.5%. Both targets were higher than previous guidance.
Ramaswamy outlined the demand picture on the earnings call. Here's what he said:
- "AI is compounding Snowflake's advantage across 3 reinforcing dynamics. First, AI is bringing new workloads onto the platform. To power their AI initiatives, enterprises need a governed, unified foundation for data and context, and companies across industries are turning to Snowflake to power that foundation. Second, our first-party AI products, CoCo and CoWork, continue to see rapid adoption. As customers build and deploy agents on Snowflake, we are expanding our role into the agentic control plane and creating new opportunities for growth. Third, AI activation continues to lift overall platform consumption. Customers using AI on Snowflake consume more across the data platform, creating a structural multiplier for our business."
- "The more our customers build on Snowflake, the more they lean in. In fact, 65 customers have now crossed $10 million in trailing 12-month product revenue, demonstrating how our largest customers continue to go all in on Snowflake."
- "We see the acceleration come from a very broad swath of customers. It is not concentrated, for example, with, let's say, AI-native companies. They continue to be a small part of our overall revenue stream. And I think the thing that's also materially different this time around with folks that are investing is that products like CoCo make optimization far, far easier than before. You can point CoCo at a query that's taking too long to run or you can basically have it debug the top 10 longest-running queries or the most idle warehouses. Things like that are a lot easier to do. And in fact, our cost management skill in CoCo is a top 10 skill."
- "We are absolutely seeing a lot of interest in being able to switch between different models and also to optimize cost. And this is also where open source models come in. There's obviously been several generations of these open source models, and we support many of them within Snowflake. And yes, we have pretty different economics when it comes to open source models since we run the inference ourselves. So that offers a lot of potential for future optimization. And within our harnesses, many of the requests that we get from customers come in this mode that we call auto, where we can pair up the task with the model that is most appropriate for that particular task. And that gives us a lot of leeway in being able to optimize tasks for our customers."
Constellation Research's MIke Ni's point of view
Snowflake’s latest quarter gave the Street what it wanted: accelerating product revenue growing 37% to $1.49B, RPO reaching $9B, and higher full-year guidance. Importantly, management also said AI products have accounted for roughly half of recent growth acceleration.
The story: Snowflake is aggressively pushing its AI vision, and buyers are approving.
Since its bevy of announcements at Snowflake Summit in June, Snowflake has added model routing, agent governance, MCP connectivity, context services and AI development tooling around its data platform. Snowflake has been clear: it wants to sit between enterprise data and AI execution.
Databricks is pushing toward the same control point.
For CDAOs and CIOs, the platform decision keeps shifting as consolidation continues, with each player approaching from its starting point.
MyPOV:
-
The question is no longer just where data is stored or analyzed … Snowflake is shaking off the perception that it's anchored in warehouse economics. The question is increasingly where AI gets its context, permissions, model choice, and rules for action.
-
What you should do: keep ownership of your data, context, policies, and decision logic clear. Preserve model optionality. Be deliberate about where the AI execution control point lives.
Snowflake’s growth is the headline today, but the story I am following is that the data platform is moving closer to the decision layer.
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Read morePublished
Author
