


Anthropic's IPO roadshow video takeaways: From the absurd to interesting
Anthropic posted its IPO roadshow video with CEO Dario Amodei making bold predictions along with some color on the compute model and financial picture.
The IPO roadshow video was posted to Anthropic's site and here's a look at the takeaways. First, let's roll with the absurd. If Amodei delivers on curing cancer, Alzheimer's, heart disease and mental illness in a decade, he'll be a hero. However, there's a certain amount of hubris with making those predictions in the first place.
- Anthropic rounds out its office ambitions with Claude Sheets, Whiteboards and more
- Anthropic's IPO on deck: You can't say you weren't warned
Here's the quote:
"If today we look at things like cancer, Alzheimer's, heart disease and mental illness, these will be relics of the past in I think less than a decade. I believe that the company which gets the risks right will also be the company that has the license to operate that society trusts and society believes can build the benefits in the right way. I think if we do this right, we can create an age of miracles where humanity is able to solve problems that that have eluded us for millennia, we have to make sure that all the risks, all the ways that things can go wrong with this technology, we very carefully address those risks as we bring the benefits and as we have a viable business at the same time, and I invite you to join us on the next phase of this journey."
That's some pitch to buy an IPO and you can't say Amodei doesn't aim high. For the rest of us cynical types, here are some other comments from the video worth noting.
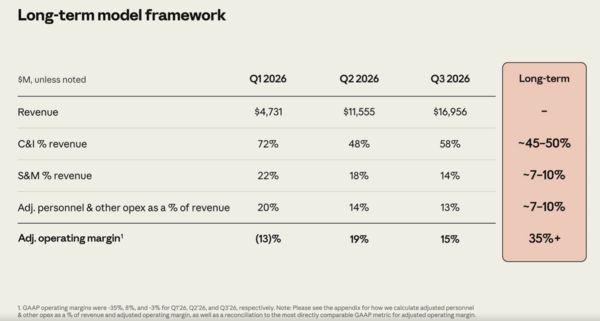
The long-term targets are for an adjusted operating margin above 35%, compute and infrastructure at about 50% of revenue and sales and marketing at 7% to 10%.
My view: Beware the adjusted talk given that training costs are often omitted. And you thought SaaS accounting was somewhat made up...
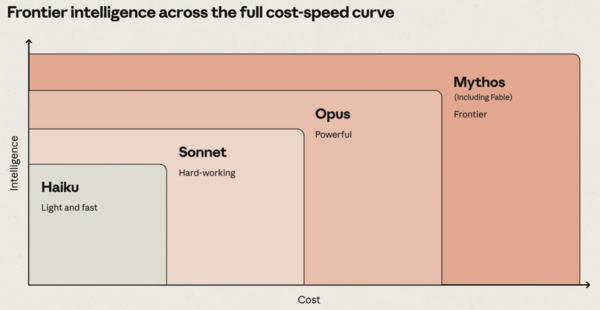
Anthropic sees model-led growth as its mantra. The smarter the models get, the more customers find value and the more revenue Anthropic lands.
My view: This model-growth will work until it doesn't. Good enough will work for most enterprises.
The company sees compute as its core advantage. Anthropic trains and runs Claude on all four major chip families and treats them as "one fungible pool of compute." Anthropic believes $1 of its compute "goes further than $1 at any other frontier lab."
My view: This claim is the second most absurd thing Anthropic said. And I'm sure that Google and Meta have something to say on the matter. The comment may have also been adjusted to only include OpenAI as the other frontier lab.
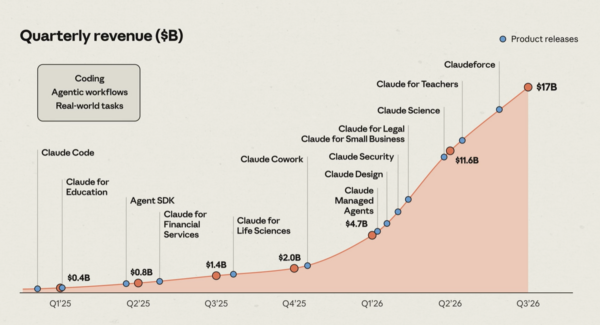
Compute multipliers. Anthropic noted that Claude set itself up to work on AMD GPUs. Anthropic credits compute multipliers for 45x revenue growth with 10x compute costs over six quarters.
My view: Anthropic's section on compute multipliers, or algorithmic gains that build on each other, is worth pondering. Anthropic's backward looking view, however, doesn't account for nearly $1 trillion in future computing commitments.
Anthropic is diversifying away from the cloud. The company outlined Anthropic Direct, which is an approach that leases chips and runs them in data centers built for Anthropic rather than only buying cloud capacity.
My view: Smart move to ensure Anthropic isn't a hostage to hyperscale cloud providers.
Anthropic has a twist on land and expand. Anthropic said more than half of the Fortune 500 spends more than $100,000 a year on Claude and there's upside for wallet share gains. The typical path is Claude Code for developers, an expansion into knowledge work followed by automated processes and then Claude built into new products.
My view: Anthropic's token bills may have put off this land and expand strategy given enterprises are wary of being locked into any one model provider. Why would you pay a toll to build Claude into new products?
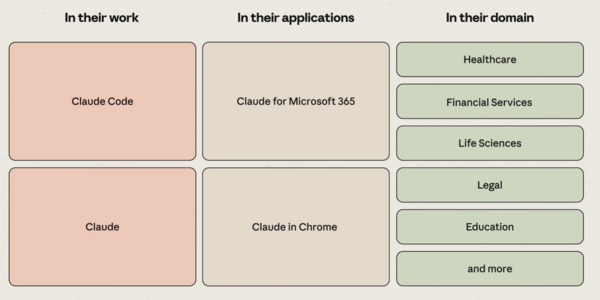
Anthropic sees industries as the way to grow. The company frequently cited Claude gains in legal, healthcare, financial services and life sciences.
My view: Anthropic is a shadow SaaS provider and the strategy makes sense given its focus on enterprises.
Safety is a business advantage. Anthropic hammered home the safety and alignment theme and the company has the high ground on OpenAI.
My view: That positioning is likely to resonate amid political change in the US, but it's not clear that Anthropic is safer than any of the enterprise incumbents like Google, AWS or Microsoft.
Larry Dignan is Editor in Chief of Constellation Insights at Constellation Research, where he leads editorial coverage focused on enterprise technology, digital transformation, and emerging trends shaping the future of business. He oversees research-driven news, analysis, interviews, and event coverage designed to help technology buyers and vendors navigate complex markets with clarity and context. ...
Read morePublished
Author
